MNI US OPEN - US Payrolls Expected Cleaner, But Not Fogless
EXECUTIVE SUMMARY
- MNI US PAYROLLS PREVIEW: CLEANER, BUT NOT QUITE FOGLESS
- POTENTIAL TODAY FOR SUPREME COURT DECISION ON LEGALITY OF IEEPA TARIFFS
- TRUMP CANCELS SECOND ATTACK ON VENEZUELA, CITES COOPERATION
- MODI’S FAILURE TO CALL TRUMP DERAILED TRADE DEAL, LUTNICK SAYS
- TSMC SALES BEAT ESTIMATES IN UPBEAT OUTLOOK FOR AI SPENDING
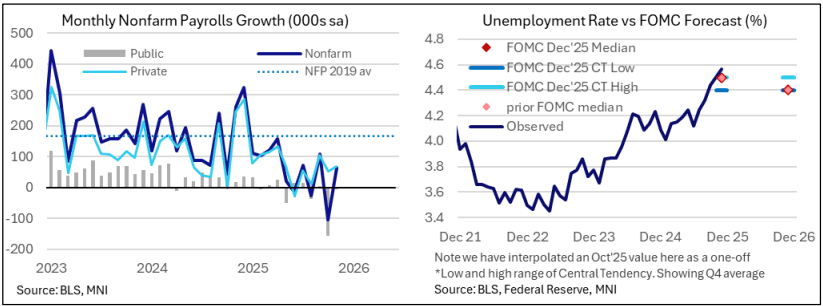
Figure 1: Recent US labour market developments
NEWS
MNI US PAYROLLS PREVIEW: Cleaner, But Not Quite Fogless
Friday’s nonfarm payrolls report for December (released 0830ET) should see a return to a more normal update, after last month’s dual payrolls figures and single month for the household survey in November with its missing October values and well-touted technical issues clouding it. Consensus looks for nonfarm/private payrolls growth of 69k/75k with primary dealer analysts a touch higher for nonfarm. It would see similar monthly rates to those in November after nonfarm payrolls fell heavily in October on federal government deferred resignations showing up.
US (RTRS): Importers Brace for $150 Billion Tariff Refund Fight if Trump Loses at Supreme Court
Company executives, customs brokers and trade lawyers are bracing for a Supreme Court ruling on the legality of President Donald Trump's sweeping global tariffs - and a potential fight over obtaining perhaps $150 billion in refunds from the U.S. government for duties already paid by importers if he loses. Anticipation that the court will strike down the tariffs Trump imposed under the International Emergency Economic Powers Act of 1977 rose after the November arguments in the case when conservative and liberal justices alike voiced skepticism about whether that law gave him the authority to levy the duties. The court is expected to issue rulings on Friday but, as is customary, has not said what case or cases will be acted upon.
US/VENEZUELA (BBG): Trump Cancels Second Attack on Venezuela, Cites Cooperation
US President Donald Trump said a second wave of attacks on Venezuela has been canceled, citing improved cooperation from the country. Venezuela is “working well” with the US on rebuilding its oil and gas infrastructure and releasing “large numbers” of political prisoners, Trump wrote in a social-media post on Truth Social on Friday. That means another wave of strikes doesn’t appear necessary, he said.
US/VENEZUELA (BBG): Trump to Meet Machado in Opening for Venezuela Opposition
President Donald Trump said he planned to meet with Venezuelan opposition leader and Nobel Peace Prize recipient María Corina Machado as soon as next week, his first show of support for her in the days since last weekend’s operation to capture strongman Nicolas Maduro. “I understand she’s coming in next week sometime, and I look forward to saying hello to her,” Trump said in an interview Thursday with Fox News host Sean Hannity.
US/INDIA (BBG): Modi’s Failure to Call Trump Derailed Trade Deal, Lutnick Says
US Commerce Secretary Howard Lutnick said a trade deal with India did not materialize last year because Prime Minister Narendra Modi did not call President Donald Trump. Speaking on a podcast, Lutnick said India was given “three Fridays” to clinch a trade deal with Washington last year and that Modi had to call Trump to close it. Lutnick said there had been an expectation that a deal with India would be sealed before those with Vietnam or Indonesia, which were signed in mid-2025, but the effort was derailed because New Delhi was “uncomfortable” setting up a call between Modi and Trump.
US/CHINA (Axios): GOP Effort to Thwart Chip Sales to China Gains Steam
House China hawks are pressing ahead with efforts to prevent Beijing from accessing sensitive U.S. technology as the Trump administration green-lights chip sales. Congress is looking to rein in President Trump on chip sales, even as most Republicans avoid public criticism. Republicans are largely toeing the line publicly on the president's decision to allow AI chips to go to China, but that's masking growing unease privately, two sources familiar with the matter told Axios.
US (BBG): Intel CEO Meets With Trump, Who Hails Gain in US Chipmaker Stake
President Donald Trump met with Intel Corp. Chief Executive Officer Lip-Bu Tan on Thursday at the White House, where the two men discussed the company’s progress on its new line of processors following the US government’s purchase of shares in the chipmaker. In a post to his Truth Social network, Trump hailed what he called progress at Santa Clara, California-based Intel, whose shares are up more than 70% since plans emerged last year for the federal government to buy as much as 10% of the company. So far, the US has amassed a roughly 5.5% stake, with more set to be acquired.
CORPORATE (BBG): TSMC Sales Beat Estimates in Upbeat Outlook for AI Spending
Taiwan Semiconductor Manufacturing Co.’s revenue topped estimates, reinforcing hopes of sustained global AI spending in 2026 despite concerns about an industry bubble. The go-to chipmaker for Nvidia Corp. reported a roughly 20% rise in December-quarter revenue to NT$1.05 trillion ($33.1 billion), based on calculations off monthly figures. That compares with an average projection for NT$1.02 trillion.
CORPORATE (WSJ): Rio Tinto, Glencore Restart Talks to Form World’s Biggest Miner
Rio Tinto and Glencore are in talks about a deal that could create the world’s largest mining company with a market value of more than $200 billion, as a scramble for copper and other metals drives an industry return to big acquisitions. Glencore and Rio Tinto separately confirmed that talks are under way over an all-share deal, revisiting a tie-up that was first discussed around a year ago when the U.S. and other countries began reshaping supply chains for metals and minerals essential to industries such as defense, automaking and semiconductor chips.
ECB (BBG): ECB’s Radev Says Current Level of Rates Is Appropriate: Capital
European Central Bank Governing Council member Dimitar Radev indicated he is comfortable with interest-rate settings, according to an interview in Capital newspaper. “The current level of interest rates can be assessed as appropriate in terms of the available information and the inflation outlook,” said Radev, who heads Bulgaria’s central bank. “The Governing Council of the ECB is not committed to a predetermined trajectory. Decisions are taken at each meeting, depending on the incoming data and the balance of risks.”
UK/EU (FT): UK to Exclude Financial Services From Push for Closer EU Alignment
Sir Keir Starmer will exclude the City of London from his push for “closer alignment” with the EU, following lobbying by financial services firms against any return to Brussels rules. British government officials told the FT that while ministers wanted “closer co-operation” with the EU on financial services, the prime minister had no intention of trying to reintegrate the sector with the Brussels rule book. Starmer’s comment this week that “if it’s in our national interest to have even closer alignment with the single market, then we should consider that” raised concerns in the Square Mile.
CHINA (BBG): China Vanke Preps Restructuring Plan in Move Toward Default
China Vanke Co. is preparing a debt restructuring plan at the request of authorities, people familiar with the matter said, pushing one of the country’s largest real estate developers closer to default. Vanke, one of the few major Chinese property companies to avoid a debt failure so far, was recently asked by authorities to accelerate its overhaul and submit the plan as soon as possible, according to the people, who asked not to be identified discussing private matters. Normally a restructuring would lead to suspension of debt payments and result in a default.
BOJ (BBG): BOJ Is Said Likely to Raise Economic Growth Outlook on Stimulus
The Bank of Japan is likely to raise its economic growth projection when its board meets later this month, while officials are set to keep the benchmark interest rate on hold, according to people familiar with the matter. The central bank will probably revise up its economic projection from 0.7% for the fiscal year starting in April in its quarterly economic outlook report due to be released with the policy statement on Jan. 23, according to the people. The forecast for the current fiscal year might also be upgraded, the people said.
JAPAN (BBG): Japan Seeks Support as Fears Rise Over China’s Rare Earth Grip
Japan is ramping up efforts to reach out to its Group of Seven peers and beyond amid mounting concerns over China’s grip on rare earths as the dispute with Beijing escalates. Japanese Finance Minister Satsuki Katayama said she will meet with counterparts of other industrialized democracies to discuss critical minerals during a trip to the US starting Sunday, while Defense Minister Shinjiro Koizumi is also set to hold talks with his US counterpart on Thursday. At home, Prime Minister Sanae Takaichi will be holding a summit with South Korea’s Lee Jae Myung next week to reaffirm the alliance between the two key US allies.
IRAN (MNI): Internal & External Factors at Play Amid Escalating Protests
Comments from Supreme Leader Ayatollah Ali Khamenei are being reported as he delivers a televised address regarding the ongoing protests. Says that "There are some rioters who want to please the American president by damaging public property", but that Iran "won't back down in the face of vandalism". Says Iran will not "tolerate foreign-backed operatives". Says that President Donald Trump "should focus on running his own country". Claims that Trump "will be overthrown at the peak of pride, like past tyrants".
RUSSIA/UKRAINE (BBG): Russia Launches Oreshnik Missile in Air Strikes on Ukraine
Russia launched an intermediate-range ballistic missile known as Oreshnik in a widespread air attack on Ukraine that targeted energy infrastructure and damaged apartment buildings. Russia previously launched an Oreshnik missile against Ukraine’s fourth-largest city, Dnipro, in November 2024. The design of the missile is based on technology in Russia’s intercontinental ballistic missiles that are capable of carrying nuclear warheads, and it may have a range of 5,000 kilometers (3,110 miles), putting most of Europe and the US West Coast within striking distance.
DATA
EUROZONE NOV RETAIL SALES +0.2% M/M, +2.3% Y/Y (VS +0.3% M/M, +1.9% Y/Y OCT) (MNI)
GERMANY DATA (MNI): IP Stronger in November With Plenty of Moving Parts
- GERMANY NOV IND PROD +0.8% M/M, +0.8% Y/Y (VS +2.0% M/M, +1.0% Y/Y OCT)
German industrial production was stronger than expected in November rising 0.8% M/M (with a 0.2ppt upside revision to October) after we've flagged upside risks to consensus following yesterday's factory orders print. "The less volatile three-month on three-month comparison showed that production was 0.7% higher in the period from September 2025 to November 2025 than in the previous three months", Destatis comments.
GERMANY NOV TRADE BALANCE EUR +13.1 BLN (MNI)
GERMANY NOV EXPORTS -2.5% M/M; IMPORTS +0.8% M/M (MNI)
FRANCE DATA (MNI): IP Turns Mildly Negative, Energy Rebounds Offset Transport Strength
- FRANCE NOV IND PROD -0.1% M/M
France November industrial production printed a touch stronger than consensus at -0.1% M/M (cons -0.2%, 0.2% Oct), but still marginally contractionary. Declines in production of food, refined products, machinery and electricity/steam/gas offset strength in electricals and transport equipment, which has been a strong upward driver as of late. This was the first negative M/M IP print since August, though on the whole appears a partial rebound from October's rise. The story of strong energy sector rebounds driving the headline figure remains prevalent. IP fell 0.1% M/M (vs +0.2% Oct), and grew 2.1% Y/Y (above consensus of 1.6%, and up from an upwardly revised 1.8% Oct).
FRANCE DATA (MNI): Consumer Spending Sees Energy-Driven Pullback in November
- FRANCE NOV CONSUMER SPEND -0.3% M/M, +0.0% Y/Y (VS +0.5% M/M, +0.6% Y/Y OCT)
France real consumer spending saw a sizeable decline in November at -0.3% M/M (-0.1% cons), after an upward revised 0.5% in Oct (+0.1pp) and what had been a third consecutive increase. It was driven by a large drop in energy consumption alongside a more muted reversal lower in food consumption, which were only partially offset by increased spending on manufactured goods. On the whole, a pullback isn't concerning given recent strength, though the longer-term trend remains tepid at best. The headline Y/Y rate fell back to flat after just one positive reading since June, but this was October's notable 0.6% Y/Y (revised up 0.2ppt).
UK DATA (MNI): BRC Footfall Sees Sharp December Decline, Weak End to 2025
UK footfall decreased a sharp 2.9% Y/Y in December, down from -0.8% in November - leaving the "golden quarter" (Q4) for retail at a significant 2.2% Y/Y footfall drop. This marks the eighth straight month of decline, with the BRC highlighting rising living costs potentially causing consumers to hold off for post-Christmas sales. Though we would caution against reading too much into the data as the proportion of online purchases can vary (especially around sales events), the release paints an, at best, subdued picture for the retail sector to end 2025.
NORWAY DATA (MNI): Inflation Pressures Still to Firm for Norges Bank
- NORWAY DEC CPI +0.1% M/M, +3.2% Y/Y
- NORWAY DEC CPI-ATE +0.1% M/M, +3.1% Y/Y
The details of the December inflation report underscore Norges Bank's cautious stance, with services ex-rent and food inflation pressures noted. Although the surprise in CPI-ATE versus Norges Bank and consensus was small, 2-year NOK swap rates are still up over 5bps on the session, NOKSEK is now up 0.25% to 0.9170, piercing resistance at the 20-day EMA of 0.9167. On a seasonally adjusted basis using Statistics Norway data, CPI-ATE prices rose 0.3% M/M in December, after 0.15% in November and 0.45% in October. That pulled 3m/3m annualised momentum up to 3.21%, an eight month high.
SWEDEN DATA (MNI): Solid Rise in Nov GDP, Riksbank Not Concerned About Inflation Risks
Swedish GDP rose 0.9% M/M in November, according to monthly activity data. That was much stronger than expected, and kept 3m/3m momentum at a solid pace of 0.6% (albeit down from 1.1% in Oct and 1.0% in Sep). The Riksbank projects GDP to grow 0.4% in Q4, down from 1.1% in Q3. Only production data was released alongside the GDP estimate, with household consumption data due next Wednesday. That may warrant a little more caution than usual when interpreting the monthly data, with a potentially increased scope for revisions ahead. Private sector production rose 0.5% M/M, driven by the services sector.
SWISS DEC UNEMPLOYMENT RATE 3.0% (MNI)
CHINA DATA (MNI): China December CPI Near Three-Year High
- CHINA DEC CPI +0.8% Y/Y VS MEDIAN +0.8%; NOV +0.7%
China’s Consumer Price Index rose 0.8% y/y in December, up from November's 0.7% growth to hit the highest level since February 2023, in line with expectations for a 0.8% gain, according to data from the National Bureau of Statistics released Friday. The y/y increase was mainly driven by a 1.1% rise in food prices which was 0.9 percentage points higher than the previous month. On a monthly basis, CPI rose 0.2%, reversing the previous 0.1% decline. Core CPI, which excludes food and energy, rose 1.2%, flat from November's reading, marking the fourth consecutive month to be above 1%.
JAPAN DATA (MNI): Household Spending Jumps in Nov, Outpacing Weaker Earnings
- JAPAN NOV HOUSEHOLD SPENDING +2.9% Y/Y; OCT -3.0%
- JAPAN NOV HOUSEHOLD SPENDING +6.2% M/M; OCT -3.5%
Japan real household spending rose 2.9%y/y in Nov, well above the -1.0% forecast and -3.0% Oct outcome. In m/m terms spending was up 6.2%, the strongest monthly rise since 2021. In terms of the detail on today's spending update, food spending rose 0.9% y/y from -1.1% in Oct. Spending on transport, communication also surged to 20.4% y/y from -9.2%.
RATINGS: Germany & Sweden Up for Review After Close
Potential sovereign rating reviews of note scheduled for after hours on Friday include:
- Fitch on Germany (current rating: AAA; Outlook Stable)
- Morningstar DBRS on Sweden (current rating: AAA, Stable Trend)
Hidden PDF to access the indicative 2026 sovereign rating review schedules across the five most prominent rating agencies (Fitch, Moody's, S&P, Morningstar DBRS & Scope Ratings). Note that the schedules are indicative only and ratings can be reviewed on an ad-hoc basis. Rating agencies may also adjust their schedules during the year.
FOREX: USDJPY Approaches Key Resistance Ahead of Key US Data
- Ahead of December NFP, the USD index extends its recovery from the December lows to 1.35%. USDJPY has narrowed the gap substantially to key resistance at 157.89, as a BoJ sources report (said to weigh downgrade of CPI outlook) underpinned earlier strength. Japan FinMin Katayama has spoken about risks of China's export controls on global supply chains and called for smooth trade flows.
- Further strength would show JPY shorts have not surrendered after Katayama's recent FX jawboning, and would open up 158.87, the 2025 high.
- Scandinavian FX outperform after local data. Swedish monthly GDP was much stronger than expected, keeping momentum at a solid pace but a recovery in economic activity is not yet a definitively hawkish contributor to the Riksbank's policy considerations. The details of the Norway December inflation report meanwhile underscore Norges Bank's cautious stance, with services ex-rent and food inflation pressures noted. NOKSEK is roughly unchanged on the session after piercing resistance at the 20-day EMA of 0.9167.
- NZDUSD (-0.4%) meanwhile extends its recent pullback, breaking below 0.5736 support, the Dec 19 low. The next level to watch will be 0.5711, the Dec 2 low. Meanwhile, AUDUSD weakness back below 0.67 appears corrective, allowing an overbought condition to unwind
- December payrolls data will carry more signal to the market and Fed than the highly unusual November report, being the last NFPs before the FOMC's Jan meeting. Participants would probably require substantially weaker-than-expected NFPs to spur even consideration of another cut. A Supreme Court ruling on the legality of the Trump tariffs could also come as early as today.
- Elsewhere, ECB's Lane will likely repeat that rates are in a "good place", while the Fed's Kashkari, Bostic and Barkin are also scheduled to appear.
EGBS: Bund Futures Still Below 50-day EMA Following Very Active Week
- Bund futures are +7 ticks at 127.93, with activity taking a bit of a breather after a very busy week featuring significant sovereign/corporate issuance. Our technical analyst is monitoring resistance at the 50-day EMA (128.31). A clear break of this average would further undermine the recent bear theme, and signal scope for a continuation higher.
- German yields are within 0.5bps of yesterday’s closing levels, with a very light twist flattening bias noted.
- Bunds underperform swaps, with long-end swap spreads/ASWs down around 1bp.
- An extension higher in European equity futures has supported modest 10-year EGB spread narrowing versus Bunds.
- Eurozone November industrial production looks to be solid, with Germany and Spain (and to a lesser extent France) outperforming consensus expectations today.
- Global focus remains on the US labour market report at 1330GMT.
GILTS: Consolidating This Week's Bullish Price Action
Remaining in technical control after the break of key resistance levels earlier in the week.
- Contract last +8 at 92.10. A break of Wednesday’s high (92.18) would reaffirm focus on a run of Fibonacci projection levels (92.23, 92.57 & 92.72). Conversely, to the downside, Wednesday’s low (91.53) protects the 20-day EMA (91.29).
- Yields 1bp higher to 1bp lower, curve twist flattens. 10s last 4.41%, 4.40% has limited downside this week, protecting the ’25 low (4.363%) and the base of an ascending triangle (4.334% today).
- GBP STIRs little changed on the day, showing ~43bp of easing for ’26 vs. extremes of ~45bp yesterday.
- Local headline flow remains centred on the government’s desire for closer ties with the EU (if they benefit the UK). An FT report has suggested that the UK will exclude financial services from any push for closer EU alignment.
- The DMO has announced the gilt for the long syndication to be held in the W/C 19 January will be the 5.25% Jan-41 line, matching our expectations.
- Little of note on UK calendar ahead of the weekend, which will leave spill over from the U.S. NFP release as the key driver on Friday.
BoE Meeting | SONIA BoE-Dated OIS (%) | Difference vs. Current Effective SONIA (bp) |
Feb-26 | 3.711 | -1.3 |
Mar-26 | 3.623 | -10.2 |
Apr-26 | 3.507 | -21.8 |
Jun-26 | 3.439 | -28.6 |
Jul-26 | 3.364 | -36.1 |
Sep-26 | 3.333 | -39.2 |
Nov-26 | 3.300 | -42.5 |
Dec-26 | 3.297 | -42.8 |
EQUITIES: E-Mini S&P Continues to Trade Just Below Key Resistance
A bull cycle in Eurostoxx 50 futures remains intact and the contract is holding on to the bulk of its latest gains. The move higher this week confirms a resumption of the primary uptrend. Note too that moving average studies are in a bull-mode position, highlighting a dominant uptrend. Sights are on the 6000.00 handle next. On the downside, initial firm support to watch is 5819.97, the 20-day EMA. A pullback would be considered corrective. The trend condition in S&P E-Minis is unchanged, it remains bullish and price continues to trade above key near-term support at 6771.50, the Dec 18 low. Clearance of this level is required to signal scope for a deeper retracement and would also highlight a possible short-term reversal. For bulls, sights are on key resistance at 7014.00, the Oct 30 high. A move through this hurdle would confirm a resumption of the primary uptrend.
- Japan's NIKKEI closed higher by 822.63 pts or +1.61% at 51939.89 and the TOPIX ended 29.77 pts higher or +0.85% at 3514.11.
- Elsewhere, in China the SHANGHAI closed higher by 37.447 pts or +0.92% at 4120.426 and the HANG SENG ended 82.48 pts higher or +0.32% at 26231.79.
- Across Europe, Germany's DAX trades higher by 13.78 pts or +0.05% at 25142.26, FTSE 100 higher by 35.14 pts or +0.35% at 10079.28, CAC 40 up 40.43 pts or +0.49% at 8282.63 and Euro Stoxx 50 up 44.14 pts or +0.75% at 5947.62.
- Dow Jones mini up 3 pts or +0.01% at 49478, S&P 500 mini up 5 pts or +0.07% at 6961.75, NASDAQ mini up 33.5 pts or +0.13% at 25685.5.
Time: 10:00 GMT
COMMODITIES: Trend Structure in Gold Unchanged and Bullish
The trend structure in WTI futures remains bearish and recent gains appear corrective. Moving average studies are in a bear-mode position, highlighting a dominant downtrend. Note that resistance at the 50-day EMA, at $58.29, has been pierced. A clear breach of the EMA would signal scope for a stronger corrective phase. Key resistance is at $61.25, the Oct 24 high. A resumption of the downtrend would open $53.77, a Fibonacci projection. The trend structure in Gold is unchanged, it remains bullish and a sharp sell-off late December appears to have been a correction The trend is overbought and any deeper retracement would allow this condition to unwind. First support at $4372.9, the 20-day EMA, has been pierced. A clear break of the average would expose the 50-day EMA at $4225.3. For bulls, a resumption of gains would open $4235.2, a Fibonacci projection.
- WTI Crude up $0.01 or +0.02% at $58.1
- Natural Gas up $0.04 or +1.29% at $3.456
- Gold spot down $6.01 or -0.13% at $4471.75
- Copper up $8.1 or +1.4% at $585.7
- Silver up $1 or +1.3% at $78.2339
- Platinum up $17.16 or +0.75% at $2310.23
Time: 10:00 GMT
| Date | GMT/Local | Impact | Country | Event |
| 09/01/2026 | 1200/0700 | ** |  BR | Brazil Final CPI |
| 09/01/2026 | 1245/1345 |  EU | ECB Lane Keynote at Danish Economy Conference | |
| 09/01/2026 | 1330/0830 | *** |  CA | Labour Force Survey |
| 09/01/2026 | 1330/0830 | *** |  US | Housing Starts |
| 09/01/2026 | 1330/0830 | *** | US | Employment Report |
| 09/01/2026 | 1500/1000 | *** | US | U. Mich. Survey of Consumers |
| 09/01/2026 | 1500/1000 | ** | US | University of Michigan Surveys of Consumers Inflation Expectation |
| 09/01/2026 | 1500/1000 | US | Minneapolis Fed's Neel Kashkari | |
| 09/01/2026 | 1800/1300 | ** | US | Baker Hughes Rig Count Overview - Weekly |
| 09/01/2026 | 1835/1335 | US | Richmond Fed's Tom Barkin |


