MNI US OPEN - US-Iran Closing in on One-Page Deal
EXECUTIVE SUMMARY
- U.S. AND IRAN CLOSING IN ON ONE-PAGE MEMO TO END WAR: AXIOS
- TRUMP SAYS U.S. PAUSING EFFORTS TO GUIDE SHIPS THROUGH STRAIT BLOCKED BY IRAN
- AMD RALLIES ANEW AFTER AI DEMAND FUELS BLOCKBUSTER FORECAST
- TRUMP'S WIN IN INDIANA PRIMARIES COULD LEAD TO SECOND REDISTRICTING PUSH
Figure 1: One-day change in WTI futures price (%)
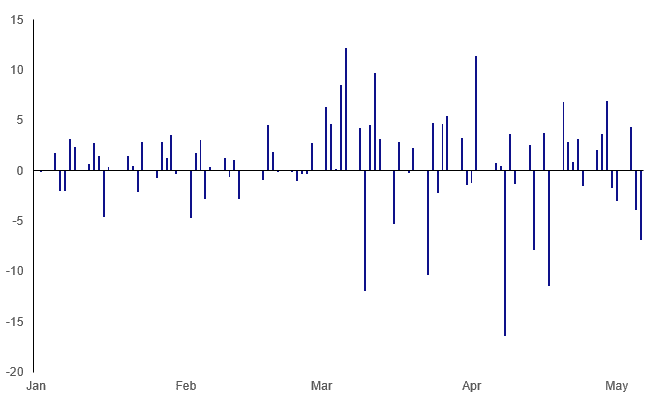
Source: MNI, Bloomberg Finance L.P.
NEWS
US/IRAN (Axios): U.S. and Iran Closing in on One-Page Memo to End War, Officials Say
The White House believes it's getting close to an agreement with Iran on a one-page memorandum of understanding to end the war and set a framework for more detailed nuclear negotiations, according to two U.S. officials and two other sources briefed on the issue. The U.S. expects Iranian responses on several key points in the next 48 hours. Nothing has been agreed yet, but the sources said this was the closest the parties had been to an agreement since the war began. Among other provisions, the deal would involve Iran committing to a moratorium on nuclear enrichment, the U.S. agreeing to lift its sanctions and release billions in frozen Iranian funds, and both sides lifting restrictions around transit through the Strait of Hormuz. Many of the terms laid out in the memo would be contingent on a final agreement being reached, leaving the possibility of renewed war or an extended limbo in which the hot war has stopped but nothing is truly resolved.
US/IRAN (NYT): Trump Says U.S. Pausing Efforts to Guide Ships Through Strait Blocked by Iran
President Trump, in a sudden reversal, announced on Tuesday evening that the United States was pausing “for a short period of time” efforts to help guide ships through the Strait of Hormuz, which Iran has effectively blocked to most commercial ships for weeks. The president’s announcement came one day after the effort began. He said in a social media post that the change was “based on the request of Pakistan and other countries,” as well as the “tremendous military success” and “great progress” toward an agreement. Pakistan has hosted cease-fire talks between American and Iranian negotiators. Mr. Trump said, however, that a recently announced U.S. blockade would “remain in full force and effect” in the narrow waterway and that the pause was “to see whether or not the agreement can be finalized and signed.”
CORPORATE (BBG): AMD Rallies Anew After AI Demand Fuels Blockbuster Forecast
Advanced Micro Devices Inc., the leading challenger to Nvidia Corp. in AI computing chips, soared to new heights in late trading after a flood of data center spending bolstered its sales forecast. Second-quarter revenue will be $11.2 billion, plus or minus $300 million, the company said in a statement Tuesday. That compares with an average analyst prediction of $10.5 billion, according to data compiled by Bloomberg. AMD also gave robust predictions for its longer-term growth, sending the shares up more than 11% in extended trading. The stock had already gained 66% this year heading into the report, and it’s poised to reach a record high if the gains extend into regular trading Wednesday.
CORPORATE (Information): Anthropic Commits to Spending $200 Billion on Google’s Cloud and Chips
Anthropic plans to spend about $200b with Google over five years, the Information reports, citing an unidentified person familiar with the matter.
US (BBG): US Gasoline Tops $4.50 a Gallon for First Time Since July 2022
US gasoline prices topped $4.50 a gallon for the first time since July 2022, extending their march higher as drivers face further strain from the prolonged conflict in the Middle East. The nationwide average retail price for regular unleaded gasoline rose to $4.54 a gallon on Tuesday, according to the American Automobile Association, and is now around 50 cents off the record $5.01 set in June 2022. On a seasonal basis, prices are already at an all-time high for this time of year.
US (MNI): Trump's Win in Indiana Primaries Could Lead to Second Redistricting Push
President Donald Trump scored a major political victory in a slate of Indiana state Senate primaries yesterday, with voters ousting most of the Republican state Senators who voted against a Trump-backed effort to leverage a supermajority in the state legislature to redraw a favourable Congressional map. "Election returns from the Associated Press showed that five of the seven Trump-backed challengers won in their primaries, including Blake Fiechter, Tracey Powell, Michelle Davis, Brian Schmutzler and Trevor De Vries. Jeff Ellington, who was endorsed by Trump in the open seat, also prevailed in his primary," per The Wall Street Journal. The primary results suggest that, despite a string of Democratic overperformances in recent special elections, including the Florida district of Trump’s Mar-a-Lago resort, Trump still retains significant influence over the grassroots GOP.
ECB (BBG): ECB’s Cipollone Says Likelihood of Interest-Rate Hike Is Rising
The chance of an increase in euro-zone borrowing costs is growing as the Iran war drags the economy away from the European Central Bank’s base case, according to Executive Board member Piero Cipollone. “The current situation seems to be drifting away from our March baseline projections, which increases the likelihood that we may need to adjust our policy rates,” the Italian official said. “If sustained, the current shock could have significant implications for our medium-term inflation objective and the euro area’s economic outlook.”
BOE (FT): We Must Be Mindful of the Risks of Private Credit - BOE’s Bailey
Much has been said of late about the economic role of private credit and the risks it may pose to financial stability. The sector has grown more than 10-fold since 2009, with current estimates ranging from $1.5–2tn (when measured by direct lending). And while activity is concentrated in developed economies, where it has average annual growth rates of more than 10 per cent, emerging markets have also seen a five-fold increase over the past decade. Given its growing global role, international co-operation on risk management is ever more important.
UK (The Times): Angela Rayner Unlikely to Win Unions’ Support to Replace Keir Starmer
Britain’s three largest unions are unlikely to back Angela Rayner if she challenges Sir Keir Starmer to become leader of the Labour Party, The Times understands. Senior figures in Unite, Unison and GMB, which together account for the majority of the party’s affiliated membership, have signalled that they may not back the former deputy prime minister if she runs against Andy Burnham, the mayor of Greater Manchester, dealing a significant blow to any formal campaign she may mount. Rayner has long touted her support for the unions and rose through Unison’s ranks to become its most senior official in the northwest of England before becoming an MP.
Hidden PDF: Favourable Starting Point:
The Riksbank is expected to hold the policy rate at 1.75% on Thursday, while reiterating a patient but vigilant stance with respect to upside inflation risks. We think the Board will have enough confidence to note that the rate is expected to "remain at this level for some time to come", with the June decision (where an updated rate path forecast and MPR will be presented) a more appropriate time to consider any revisions. Domestic economic developments since the March decision have reinforced our view that, absent the Iran war, the Riksbank may have needed to cut rates in H1 2026. In the current environment, that suggests that the bar to hiking is higher for the Riksbank than the ECB.
Hidden PDF: Patience May Not Prevail
Norges Bank laid the foundations for rate hikes at the March decision, and we expect the first to be delivered in May, bringing the deposit rate to 4.25%. Such a move would go against analyst consensus for a hold at 4.00%, though rates markets lean slightly in favour of a hike. Norges Bank are primarily concerned about high domestic inflation, with the Iran war providing a separate hawkish impulse to the outlook given Norway’s status as an energy exporter. As such, we don’t see much value in the Board waiting till June to hike rates – elevated inflation has been flagged as a concern for some time now, and the March guidance was quite clear that the Committee is ready and willing to act.
CHINA (BBG): China Seeks Bigger Role in Restoring Middle East Peace: Wang Yi
China believes complete ceasefire in Iran war is of “utmost urgency”, and urges negotiations, Chinese Foreign Minister Wang Yi says during a meeting with his Iranian counterpart Abbas Araghchi, according to a statement from the Chinese foreign ministry. China expresses appreciation for Iran’s commitment to not develop nuclear weapons, while defending Tehran’s “legitimate right” to peaceful use of nuclear energy.
AUSTRALIA/CHINA (BBG): Australia Imposes Tariffs on China Steel Coil Due to Dumping
Australia’s government has imposed tariffs as high as 82% on hot rolled steel coil from China, following an investigation by the nation’s Anti-Dumping Commission. The agency launched the probe after receiving a complaint from domestic steelmaker BlueScope Steel Ltd. The tariffs range from 38.1% to as much as 82.4%, according to the commission’s final report.
RBNZ (MNI INTERVIEW): Market Overestimating RBNZ Hikes - Ex Econ
A former RBNZ official shares his OCR outlook. On MNI Policy MainWire now, for more details please contact sales@marketnews.com
INDIA (BBG): India’s RBI Mulls New Move Using Foreign Bonds to Prop Up Rupee
India’s central bank is weighing a plan for state lenders to sell foreign-currency bonds, mulling a tool last used nearly three decades ago to draw capital inflows and shore up the beleaguered rupee, according to people familiar with the matter. Reserve Bank of India officials discussed a proposal that would see lenders issue foreign-currency bonds, potentially with five-year maturities, the people said, asking not to be named as the talks are private. Discussions are preliminary and no decision has been made, they said.
ARGENTINA (BBG): Argentina Upgraded by Fitch on Milei’s Economic Overhaul
Argentina’s credit score was upgraded by Fitch Ratings, signaling growing confidence in President Javier Milei’s push to overhaul the economy and secure financing to cover the country’s upcoming debt obligations. The South American nation was raised to B- from CCC+, six notches below investment grade, the ratings firm said in a statement on Tuesday. The outlook is stable.
BRAZIL (BBG): Trump to Meet With Brazil’s Lula Thursday for Economic Talks
President Donald Trump will host Brazilian counterpart Luiz Inacio Lula da Silva Thursday, amid tensions over the Iran war and its impact on the global economy. The working visit between the two leaders will include discussions on economic and security matters of shared importance, according to a White House official. The two leaders have had a thorny relationship in the past as they clashed over trade, foreign policy and the fate of former Brazilian President Jair Bolsonaro — a Trump ally who was convicted of plotting a coup following his 2022 election loss to Lula.
DATA
EUROZONE MAR PPI 2.1% Y/Y (-3.0% FEB) (MNI)
EUROZONE MAR PPI 3.4% M/M (-0.6% FEB, REV FROM -0.7%) (MNI)
ECB DATA (MNI): Wage Tracker: Minor Revisions vs March, Trending to 2.6% by Q4 2026
The ECB's latest forward looking wage tracker update saw minor revisions relative to the March iteration. Negotiated wages excluding one-off payments are still seen around 2.6% by Q4 2026. Q1 negotiated wages are due on May 22. The Q1-26 wage tracker with unsmoothed one-off payments (which most closely tracks the actual negotiated wages series) was 2.89% in today's update. The ECB press release notes that "The deeply uncertain economic situation could lead to a stronger role for one-off payments in the coming year, but this is not yet reflected in the new collective bargaining agreements signed since the March 2026 data release"
FRANCE DATA (MNI): IP Rebounded in March, With Broad-Based Manufacturing Strength
- FRANCE MAR IND PROD 0.9% Y/Y (-0.3% FEB)
- FRANCE MAR IND PROD 1.0% M/M (-0.9% FEB, REV FROM -0.7%)
- FRANCE MAR MANUF PROD 1.6% Y/Y (0.8% FEB)
- FRANCE MAR MANUF PROD 1.2% M/M (-0.1% FEB, REV FROM 0.0%)
French IP saw a stronger-than-expected rebound at 1.0% M/M in March (0.5% cons), after mild weather had driven down February's reading at -0.9% M/M (revised down 0.2ppt). Production rose in all broad manufacturing sectors, though energy/water/extractive industries rebounded only slightly from the prior sharp drop. While the headline figures show some resilience after the start of the Iran war, it's hard to say how much of this is purely a rebound from prior weakness.
SPAIN DATA (MNI): First Sub-50 Services PMI Reading in 3 Years
- SPAIN APR SERVICES PMI 47.9 (51.9 EXP, 53.3 MAR)
- SPAIN APR COMPOSITE PMI 48.7 (51.9 EXP, 52.4 MAR)
The Spanish April services PMI results appear in fitting with the rest of the region, with sentiment severely hampered by the Iran war. This was the first sub-50 reading since August 2023. The importance of tourism for Spain's economy means higher jet fuel prices could have an outsized impact on services sector activity compared to some Eurozone peers. This shock may outweigh any diversion of tourists away from the Middle East (e.g. the UAE) to Spain following the war.
ITALY DATA (MNI): April Services PMI Higher Than Expected, Limited Cost Passthrough
- ITALY APR SERVICES PMI 49.8 (47.9 EXP, 48.8 MAR)
- ITALY APR COMPOSITE PMI 50.5 (48.4 EXP, 49.2 MAR)
In contrast to Eurozone peers, the Italian April services PMI exceeded consensus expectations. However, this was likely in part due to the weak sub-50 starting point from March. In contrast to Spain, output charge responses suggest firms have been absorbing higher input costs, potentially due to to a weaker domestic demand backdrop.
EUROZONE APR FINAL SERVICES PMI 47.6 (47.4 FLASH, 50.2 MAR) (MNI)
EUROZONE APR FINAL COMPOSITE PMI 48.8 (48.6 FLASH, 50.7 MAR) (MNI)
GERMANY APR FINAL SERVICES PMI 46.9 (46.9 FLASH, 50.9 MAR) (MNI)
GERMANY APR FINAL COMPOSITE PMI 48.4 (48.3 FLASH, 51.9 MAR) (MNI)
FRANCE APR FINAL SERVICES PMI 46.5 (46.5 FLASH, 48.8 MAR) (MNI)
FRANCE APR FINAL COMPOSITE PMI 47.6 (47.6 FLASH, 48.8 MAR) (MNI)
UK APR FINAL SERVICES PMI 52.7 (52.0 FLASH, 50.5 MAR) (MNI)
UK APR FINAL COMPOSITE PMI 52.6 (52.0 FLASH, 50.3 MAR) (MNI)
SWEDEN DATA (MNI): Another Soft Inflation Print
- SWEDEN APR FLASH CPIF 0.76% Y/Y (1.58% MAR)
- SWEDEN APR FLASH CPIF-XE -0.01% Y/Y (1.13% MAR)
Much lower-than-expected CPIF ex-energy inflation once again. The Riksbank's 0.67% Y/Y forecast from the March MPR was already stale following the weak March print, but the -0.01% Y/Y April reading still comfortably undershot all analyst forecasts submitted to Bloomberg. The print could limit the extent to which tomorrow's Riksbank decision is a "hawkish hold", but overall we still expect the Board to stress vigilance with respect to the inflation outlook (albeit with a very favourable starting position).
CHINA DATA (MNI): China Services Private PMI Rises in April
China’s RatingDog Services PMI rose to 52.6 in April from 52.1 in March, the agency said Wednesday. Business activity and new business growth both accelerated last month, RatingDog founder Yao Yu said, citing sub-index data. Input cost inflation accelerated to its highest level of 2026, driven largely by higher oil and fuel prices, though overall cost pressure remained modest, Yao added.
NEW ZEALAND DATA (MNI): Ongoing Labour Market Recovery Modest, Wages Contained
The labour market continued its modest recovery in Q1. The unemployment rate was lower, there was job growth in both full-time (FT) and part-time (PT) sectors and hours worked were higher. While the unemployment rate dip to 5.3% was in line with the RBNZ's February forecast, employment growth was softer. Wage growth also remained contained, thus labour market conditions argue for the RBNZ to remain on hold but the onset of the Iran War has complicated decision making. The next announcement is 27 May. Employment rose 0.2% q/q to be up only 0.4% y/y after 0.5% q/q & 0.2% y/y. The RBNZ projected in February an increase of 0.4% & 0.7%. The majority of job growth was in part-time positions suggesting employer caution.
FOREX: Reportedly Looming US-Iran Agreement Pressures USD
- Earlier dollar losses extend as we approach the NY crossover after a report that a US-Iran agreement might be looming. Amid firmer risk sentiment and higher precious metals prices, this lead the DXY to dip below the 98.00 handle, putting the focus on the pre-war close of 97.56 seen on February 27. Should a deal indeed be struck, the index looks likely to move below that level which would reignite prior discussions around USD weakness.
- USDJPY saw a renewed sudden spell of weakness earlier this morning, falling around 270 pips to a session low of 155.04 (lowest level since mid-February) in what will prompt another round of intervention speculation. However, spot has recovered almost half way since, making this the fourth failed attempt below the 156.00 handle since April 30 after analysts had been sceptical if the MoF's attempts for a stronger yen will be long-lasting. This comes as positioning was not stretched ahead of the drop from 160.72 cycle highs and underlying yen-negative fundamentals remain in place, keeping intact trendline support at 155.01. Initial firm resistance to watch is 158.32, the 50-day EMA.
- Firmer risk sentiment also underpins the likes of AUD and NZD. NZDUSD (+1.3%) breaks above the cluster of highs around 0.5925 seen throughout April after data showed the New Zealand labour market to have continued its modest recovery in Q1. Should upside persist, focus would turn onto the 0.6000 handle which closely coincides with a Fibonacci retracement. AUDUSD has meanwhile traded to a fresh cycle high today, confirming a resumption of the uptrend. Sights are on 0.7262 next, a Fibonacci projection.
- MBA Mortgage Applications, monthly ADP employment, and the full US Treasury quarterly refunding announcement are on the calendar while Fed's Musalem, Goolsbee as well as BoC's Macklem and Rogers are scheduled in terms of speakers.
EGBS: Sharp Rally in Bund Futures on Ceasefire Hopes, Still Deemed Corrective
Bund futures rallied sharply after Axios reported that the US and Iran are closing in on a ceasefire agreement, but have since moved away from highs following tougher rhetoric from the Israeli side. Futures are +73 ticks at 125.66 at typing (vs a high of 125.88), having pushed through initial resistance of 125.39 (20-day EMA). Key resistance levels at 126.26 (Apr 17 high) and 126.64 (Apr 8 high) remain unchallenged, meaning today’s gains are still considered corrective for now.
- Markets remain extremely sensitive to incoming headline flow. Over 130k lots traded in Bund futures around the time the Axios piece was published.
- The German curve has bull steepened, with Schatz yields down 8bps at 2.59% and 10-year Bund yields back at the 3.00% figure.
- Germany has sold the 7-year 2.50% Nov-32 Bund this morning, alongside holding a E3.5bln WNG long-end syndication.
- 10-year EGB spreads to Bunds narrow on the ceasefire hopes, with the BTP/Bund spread down 4bps to 75.5bps.
- The ECB’s latest wage tracker update continued to point to easing compensation pressures through the year, though the Middle East war does leave scope for increased one-off payments. Eurozone March PPI was in line with consensus on a monthly basis at 3.4%, while the April composite PMI saw a marginal upward revision to 48.8.
GILTS: Bull Steepening as Market Looks Towards End of U.S.-Iran Conflict
The recovery in gilts has extended after Axios sources suggested that “the White House believes it's getting close to an agreement with Iran on a one-page memorandum of understanding to end the war and set a framework for more detailed nuclear negotiations", albeit with caveats within the story seemingly limiting follow through to some degree.
- This story added further weight to crude, with the initial oil weakness and gilt rally stemming from President Trump announcing a pause in “Project Freedom”, given “great progress” re: movement towards a final deal being struck with Iran.
- Futures trade as high as 87.32 before paring back a little to print +106 at 87.17.
- Bears remain in technical control despite the recovery, with bulls needing to force a break above the 20-day EMA (87.51) to start turning the technical picture a little more in their favour.
- Yields 9-10bp lower, light bull steepening seen on the curve.
- 10s back below 5.00% after bears failed to force a retest of year-to-date highs (5.121%) during the recent sell off.
- Gilt/Bunds ~3bp narrower on the day at 196.5bp after recent threats to break above 200bp. The higher beta of UK paper to energy price swings has driven the move this morning.
- Short end pricing 62bp of BoE hikes through April vs. ~78.5bp late yesterday.
- Local headline flow continues to focus on risks surrounding PM Starmer’s future in the build-up to tomorrow’s local elections.
BoE Meeting | SONIA BoE-Dated OIS (%) | Difference vs. Current Effective SONIA (bp) |
Jun-26 | 3.843 | +11.3 |
Jul-26 | 4.007 | +27.8 |
Sep-26 | 4.153 | +42.4 |
Nov-26 | 4.248 | +51.9 |
Dec-26 | 4.297 | +56.7 |
Feb-27 | 4.330 | +60.0 |
Mar-27 | 4.346 | +61.6 |
Apr-27 | 4.351 | +62.1 |
EQUITIES: E-Mini S&P Reaches New All-Time High
EuroStoxx 50 futures have erased the sharp sell-off on Monday. The reversal higher refocuses attention once again on a bullish theme. A continuation higher would expose 6022.00, the Apr 17 high and a key resistance. Clearance of this hurdle would open 6143.00, the Feb 26 high and a medium-term bull trigger. Key short-term support has been defined at 5684.00, the May 4 low. The primary long-term uptrend in S&P E-Minis remains intact and this week’s fresh cycle highs reinforce current conditions. The move higher confirms a resumption of the primary uptrend. Sights are on 7330.26 next, a Fibonacci projection. Note that moving average studies are in a bull-mode position, a strong bullish signal that highlights a dominant uptrend. Initial key support lies at 7098.31, the 20-day EMA.
- In China the SHANGHAI closed higher by 48.015 pts or +1.17% at 4160.174 and the HANG SENG ended 315.17 pts higher or +1.22% at 26213.78.
- Across Europe, Germany's DAX trades higher by 558.04 pts or +2.29% at 24966.88, FTSE 100 higher by 222.57 pts or +2.18% at 10443.43, CAC 40 up 199.08 pts or +2.47% at 8263.39 and Euro Stoxx 50 up 132.25 pts or +2.25% at 6003.07.
- Dow Jones mini up 243 pts or +0.49% at 49668, S&P 500 mini up 36.25 pts or +0.5% at 7325, NASDAQ mini up 283.75 pts or +1.01% at 28427.25.
Time: 10:15 BST/05:15 ET
COMMODITIES: WTI Futures Below $100/bbl as Pullback Extends
The primary bull cycle in WTI remains intact and the latest pullback is for now, considered corrective. The contract has recently cleared resistance at $104.34, the Mar 9 high and bull trigger, to confirm a resumption of the uptrend. The $110.00 handle has also been pierced and sights are on $113.10 next, a Fibonacci projection. Further out, scope is seen for a climb towards $120.00. Initial firm support lies at $96.93, the 20-day EMA. Gold maintains a bearish tone for now and continues to trade below its recent highs. A reversal higher and a resumption of gains would resume the correction that started on Mar 23 and open $5000.0 and $5107.6, a Fibonacci retracement. For bears, a continuation lower would instead highlight a resumption of the M/T bear condition and signal scope for a move towards $4306.4, the Mar 24 low. The key support lies at $4099.2, the Mar 23 low.
- WTI Crude down $6.37 or -6.23% at $95.8
- Natural Gas down $0.05 or -1.79% at $2.74
- Gold spot up $142.03 or +3.12% at $4702.71
- Copper up $13.4 or +2.24% at $612.75
- Silver up $4.12 or +5.66% at $76.9505
- Platinum up $64.42 or +3.29% at $2022.01
Time: 10:15 BST/05:15 ET
| Date | GMT/Local | Impact | Country | Event |
| 06/05/2026 | 1100/0700 | ** |  US | MBA Weekly Applications Index |
| 06/05/2026 | 1230/0830 | *** | US | Treasury Quarterly Refunding |
| 06/05/2026 | 1330/0930 | US | St. Louis Fed's Alberto Musalem | |
| 06/05/2026 | 1430/1030 | ** | US | US DOE Petroleum Supply |
| 06/05/2026 | 1430/1030 | ** | US | DOE Weekly Crude Oil Stocks |
| 06/05/2026 | 1700/1300 | US | Chicago Fed's Austan Goolsbee | |
| 06/05/2026 | 2015/1615 |  CA | BOC Governor and Sr Deputy testify at Senate. | |
| 07/05/2026 | 0130/1130 | ** |  AU | Trade Balance |
| 07/05/2026 | 0600/0800 | ** |  DE | Manufacturing Orders |
| 07/05/2026 | 0645/0845 | * |  FR | Foreign Trade |
| 07/05/2026 | 0700/0900 | ** |  CH | Unemployment |
| 07/05/2026 | 0715/0915 |  EU | ECB de Guindos Keynote at European Financial Integration Conference | |
| 07/05/2026 | 0730/0930 | *** |  SE | Riksbank Interest Rate Decison |
| 07/05/2026 | 0730/0930 | ** |  IT | S&P Global Final Italy Construction PMI |
| 07/05/2026 | 0730/0930 | ** | DE | S&P Global Final Germany Construction PMI |
| 07/05/2026 | 0730/0930 | ** | EU | S&P Global Final Eurozone Construction PMI |
| 07/05/2026 | 0800/1000 | *** |  NO | Norges Bank Rate Decision |
| 07/05/2026 | 0830/0930 | ** |  GB | S&P Global/CIPS Construction PMI |
| 07/05/2026 | 0900/1100 | ** | EU | EZ Retail Sales |
| 07/05/2026 | - | GB | BOE MPG Meeting | |
| 07/05/2026 | 1200/1400 | EU | ECB Elderson Chairs Panel at European Financial Integration Conference | |
| 07/05/2026 | 1230/0830 | ** | US | Preliminary Non-Farm Productivity |
| 07/05/2026 | 1230/0830 | ** | US | WASDE Weekly Import/Export |
| 07/05/2026 | 1230/0830 | *** | US | Jobless Claims |
| 07/05/2026 | 1240/1440 | EU | ECB Lane Panel "The interconnected world" at BOE | |
| 07/05/2026 | 1400/1000 | * | US | Construction Spending |
| 07/05/2026 | 1430/1030 | ** | US | Natural Gas Stocks |
| 07/05/2026 | 1500/1100 | ** | US | NY Fed Survey of Consumer Expectations |
| 07/05/2026 | 1530/1130 | ** | US | US Bill 04 Week Treasury Auction Result |
| 07/05/2026 | 1530/1130 | * | US | US Bill 08 Week Treasury Auction Result |
| 07/05/2026 | 1700/1900 | EU | ECB Schnabel Lecture at London School of Economics | |
| 07/05/2026 | 1700/1300 | US | Minneapolis Fed's Neel Kashkari | |
| 07/05/2026 | 1805/1405 | US | Cleveland Fed's Beth Hammack | |
| 07/05/2026 | 1900/1500 | * | US | Consumer Credit |
| 07/05/2026 | 1900/1500 | *** |  MX | Mexico Interest Rate |
| 07/05/2026 | 1930/1530 | US | New York Fed's John Williams |


