SWEDEN: Another Soft Inflation Print
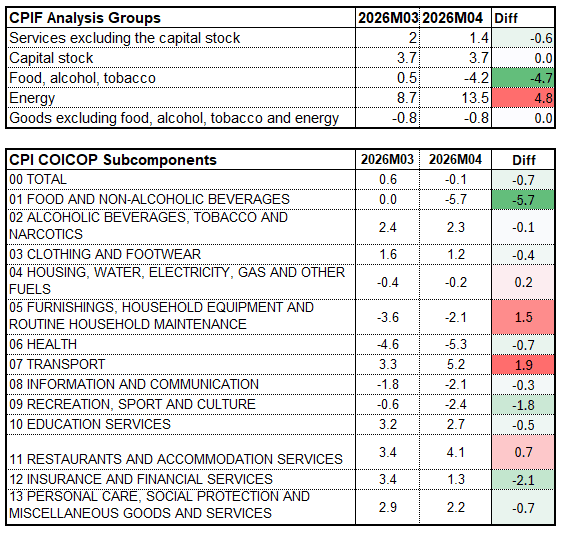
Much lower-than-expected CPIF ex-energy inflation once again. The Riksbank’s 0.67% Y/Y forecast from the March MPR was already stale following the weak March print, but the -0.01% Y/Y April reading still comfortably undershot all analyst forecasts submitted to Bloomberg. The print could limit the extent to which tomorrow’s Riksbank decision is a “hawkish hold”, but overall we still expect the Board to stress vigilance with respect to the inflation outlook (albeit with a very favourable starting position).
- SEK weakens following the release, with EURSEK up 0.2% versus pre-data levels and away from early lows.
- Food inflation unsurprisingly moved into deflation (food CPIF at -4.2% Y/Y vs 0.5% prior) as the Government’s temporary food VAT cut came into effect.
- Services CPIF looks to be a big downward surprise, moving to 1.4% Y/Y (vs 2.0% prior). We note a significant pullback in insurance and financial services CPI (1.3% Y/Y vs 3.4% prior) and recreation, sport and culture CPI (-2.4% Y/Y vs -0.6% prior).
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
US TSYS: Yields Edge Higher Ahead of US Open
With so much news to digest US treasuries had a cautious start to the trading week. Yields were higher by around 1 to 1.5bps higher across the curve whilst volumes for futures remained low.
- The 2-Yr is up +1.2bps at 3.858%
- The 5-Yr is up +1.6bps at 4.004%
- The 10-Yr is up +1bps at 4.36%
- The 30-Yr is up +1bps at 4.924%
The rally has seemingly stalled for now as markets look for the next direction. Trump's threat of a Tuesday deadline to open the Strait of Hormuz clashed with reports of a push for a ceasefire of up to 45 days with a pathway to a permanent end (as reported by Axios). This calmed oil markets with WTI around $3 lower than early morning highs.
The outcome of the next 24 hours will dictate the next move in yields as short term momentum indicators remain neutral. A 45 day pause should cap any further move higher, whereas a resumption in US/Israel bombing could see 10-Yr yields back above 4.40%
Looking ahead to Monday, March services PMI is the main focus along with ADP employment change and durable goods.
Auction wise sees a US$13-week US$89bn and a US$77bn 26-week as the primary focus.
AUD: Antipodean Update
The AUD and the NZD both tried lower from the Asian open but a last ditch push for a 45-day ceasefire has seen both of them turn positive as risk turns around on renewed optimism. Like anything you can't completely rule things out but I would be very surprised anything amounts from this.
- {AUDUSD Curncy} - 0.6910, +0.22%
- {NZDUSD Curncy} - 0.5705, +0.25%
- {AUDNZD Curncy} - 1.2110, 10.01%
CROSS ASSET: Asian Stocks Pullback Risk After A Weak Open
Risk has pulled back across the board after a fairly weak open this morning. Asian equities have all opened well as has Bitcoin. This has seen a market that started under pressure paring back those early losses and turning positive.
{ESA Index} - S&P - 6610, +0.10%
{NKY Index} - Nikkei 53655, +1.0%
{BBDXY Index} - BBDXY 1217, +0.10%
{CLA Comdty} - WTI $111.85, +0.25%
{XBTUSD Curncy} - Bitcoin 68900, +1.87%


