MNI US Macro Weekly: Higher For Longer

Sep-18 17:27By: Chris Harrison and 1 more...
USKevin WarshRetail Sales DataDonald Trump
Hidden PDF
Executive Summary
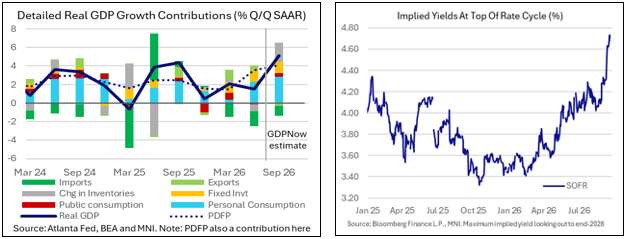
- Wednesday’s FOMC decision, or more specifically the SEP, and Fed Chair Warsh’s press conference dominated the week, pushing US rates to fresh hawkish extremes with three more hikes currently priced.
- The fully anticipated first 25bp hike on Wednesday was accompanied by a more hawkish than expected “higher-for-longer” Dot Plot and economic projections that remained pessimistic on the inflation outlook.
- Communications cemented expectations for at least one more hike this year, in line with the 25bp raise now expected by 12 of 18 FOMC members by end-2026 with 4 more seeing a third hike to 4.375%.
- The median analyst expectation remains that there is one 25bp hike to come after September's increase (an unchanged analyst median vs pre-FOMC) though consensus is roughly split with those who see two hikes; there's also split opinion on the timing for the next hike (October vs December).
- Speaking after the decision, President Trump said "I'm relying on Kevin. But he has a very tough board” when asked if he had confidence in Warsh, and revealed he spoke to Warsh just before the decision.
- The August retail sales report was far stronger than expected, boosted by a jump in gasoline sales on higher prices and non-store (i.e. internet) sales bouncing after July weakness stemming from Amazon Prime Day moving to June from its usual July slot.
- This retail strength spurred a further upward revision to the Atlanta Fed’s real GDP growth tracking to 5.1% for Q3 (after a realized 1.5% in Q2) whilst PDFP sits at an equally impressive 4.7% (after 4.2% in Q2).
- Import prices were stronger than expected and especially on an ex-petroleum basis in August, where industrial supplies and tech-driven capital goods inflation remains strong.
- Weekly labor indicators also firmed, especially jobless claims with initial claims at one of the lowest single week figures in decades, a four-week average not much higher at 203k and continuing claims falling to their lowest since early 2024.
- Business surveys were mixed, the NY Fed's mfg index hitting a three-month low after blistering activity the prior couple of months but the Philly Fed mfg index a little better than expected. The NY Fed also saw a marked softening in service provider activity in ones of its weakest reports in months.
- Housing remains a weak point as mortgage rates climb to nearly 7%, with mortgage applications under pressure, pending home sales plumbing all-time lows and August starts/permits data showing no reason to expect relief anytime soon.
- China President Xi’s trip to the US to visit U.S. President Trump will be in focus this week.
- Otherwise, it’s a much quieter US calendar for more traditional releases after the past three weeks were headlined by payrolls, CPI and the FOMC decision. Flash PMIs for September likely headline data along with relatively heavy Fedspeak compared to so far under Chair Warsh’s leadership. Of speakers, NY Fed’s Williams will be most anticipated after dovish remarks in the lead up to the FOMC meeting before a unanimous decision to hike rates this week.