EQUITIES: E-Mini S&P Reaches New All-Time High
EuroStoxx 50 futures have erased the sharp sell-off on Monday. The reversal higher refocuses attention once again on a bullish theme. A continuation higher would expose 6022.00, the Apr 17 high and a key resistance. Clearance of this hurdle would open 6143.00, the Feb 26 high and a medium-term bull trigger. Key short-term support has been defined at 5684.00, the May 4 low. The primary long-term uptrend in S&P E-Minis remains intact and this week’s fresh cycle highs reinforce current conditions. The move higher confirms a resumption of the primary uptrend. Sights are on 7330.26 next, a Fibonacci projection. Note that moving average studies are in a bull-mode position, a strong bullish signal that highlights a dominant uptrend. Initial key support lies at 7098.31, the 20-day EMA.
- In China the SHANGHAI closed higher by 48.015 pts or +1.17% at 4160.174 and the HANG SENG ended 315.17 pts higher or +1.22% at 26213.78.
- Across Europe, Germany's DAX trades higher by 558.04 pts or +2.29% at 24966.88, FTSE 100 higher by 222.57 pts or +2.18% at 10443.43, CAC 40 up 199.08 pts or +2.47% at 8263.39 and Euro Stoxx 50 up 132.25 pts or +2.25% at 6003.07.
- Dow Jones mini up 243 pts or +0.49% at 49668, S&P 500 mini up 36.25 pts or +0.5% at 7325, NASDAQ mini up 283.75 pts or +1.01% at 28427.25.
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
ASIA STOCKS: NKY and KOSPI Up Cautiously Whilst SE Asia Losses Mount
With China out, Asia looked to South Korea and Japan as the main markets opened Monday. The AXIOS report ended a weak start with the NIKKEI touching 53,200 early before rebounding back above 54,000, before settling around 53,500 and gains of +0.85%. AI stocks continued to perform from the positive spillover from Microsoft's AI partnership in Japan. Banks continue to deliver modest returns as the higher yield environment bodes well for their balance sheets.
In Korea, Samsung led the charge with gains of over +3.6% Monday driving the KOSPI higher by +1.3%. Early trading was bolstered by reports that the South Korean government is considering a new supplementary budget for the second half of the year to cushion the economy against high oil prices and supply chain disruptions. Banks are performing also given the higher yield environment perceived to have a positive impact. Gains were tempered in the afternoon with investors wary of the April 6 deadline
Malaysia, Thailand and Indonesia have all had a weak start to the trading week with losses of around -0.40% to -0.80% on the ongoing Middle East concern. The woes for the JCI started with concerns over the fiscal spend due to the government's growth objectives, was further pressured by concerns raised by the index provider MSCI (and hence rating agencies) and now the price of oil. This sees the JCI floundering with year to date losses of -19% whilst projecting a full year growth rate of around 5%
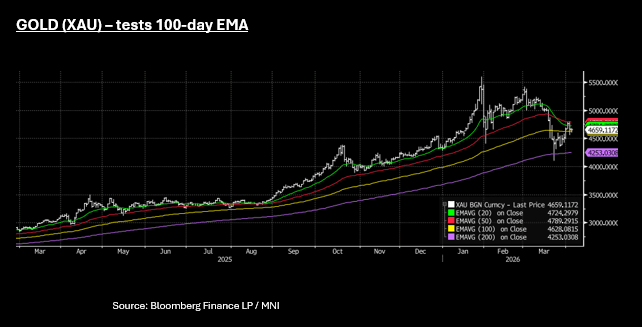
GOLD: Gold Holds Near Key Tech as Trump's Tuesday Deadline Looms
- Despite strengthening in the afternoon session, gold's weak open sees it holding onto modest losses in the Asia trading day.
- Currently near US$4661, gold is down around -0.32%
- This keeps bullions wedged between the 20-day EMA of $4,789 and just above the downside resistance from the 100-day EMA at $4,628.
- Should a break below the 100-day occur, there appears reasonable support at $4,500.
- Gold's next move will hinge on the Trump Tuesday deadline and how the USD and UST Yields react with both markets watching closely for signs of a potential ceasefire.
US TSYS: Yields Edge Higher Ahead of US Open
With so much news to digest US treasuries had a cautious start to the trading week. Yields were higher by around 1 to 1.5bps higher across the curve whilst volumes for futures remained low.
- The 2-Yr is up +1.2bps at 3.858%
- The 5-Yr is up +1.6bps at 4.004%
- The 10-Yr is up +1bps at 4.36%
- The 30-Yr is up +1bps at 4.924%
The rally has seemingly stalled for now as markets look for the next direction. Trump's threat of a Tuesday deadline to open the Strait of Hormuz clashed with reports of a push for a ceasefire of up to 45 days with a pathway to a permanent end (as reported by Axios). This calmed oil markets with WTI around $3 lower than early morning highs.
The outcome of the next 24 hours will dictate the next move in yields as short term momentum indicators remain neutral. A 45 day pause should cap any further move higher, whereas a resumption in US/Israel bombing could see 10-Yr yields back above 4.40%
Looking ahead to Monday, March services PMI is the main focus along with ADP employment change and durable goods.
Auction wise sees a US$13-week US$89bn and a US$77bn 26-week as the primary focus.


