MACRO ANALYSIS: MNI US Macro Weekly: Activity Hums While Labor Market Stutters
Our latest US Macro Weekly Hidden PDF
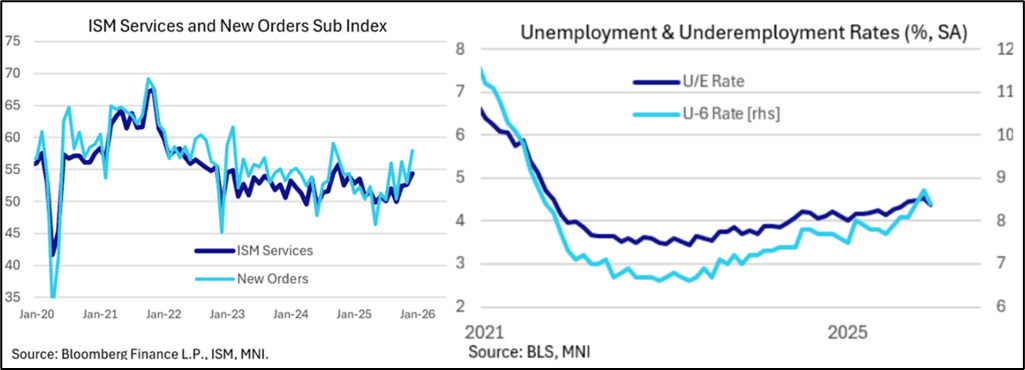
- Jobs growth may have disappointed in December’s Employment Situation report, but the drop in the unemployment rate saw near-term rate FOMC cut prospects trimmed further (January cut = no chance) after hawkish shifts throughout the week.
- A next Fed cut is still fully priced for June, only just at 25.5bp, the first meeting under a new Chair.
- Most labor market data remains concerning but activity is still robust, not least because recent productivity growth was shown this week to be stronger than expected. Additionally while manufacturing activity remains moribund, December's ISM Services report was meaningfully stronger than expected, with the headline PMI index surprisingly jumping to a 14-month high.
- A 5+% real GDP handle in Q4 as implied by the Atlanta Fed tracker may be misleadingly high due to distorted October trade data, but domestic final demand looks to have been roughly as strong at the end of the year as it was through its resilient middle.
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
FED: MNI's Rough Transcript of Fed Chair Powell's Press Conference
Below is a rough transcript of Fed Chair Jerome Powell's December 10 press conference - unedited, please check against delivery:
STIR: Dovish Reaction As Powell Doesn't Meet Hawkish Expectations
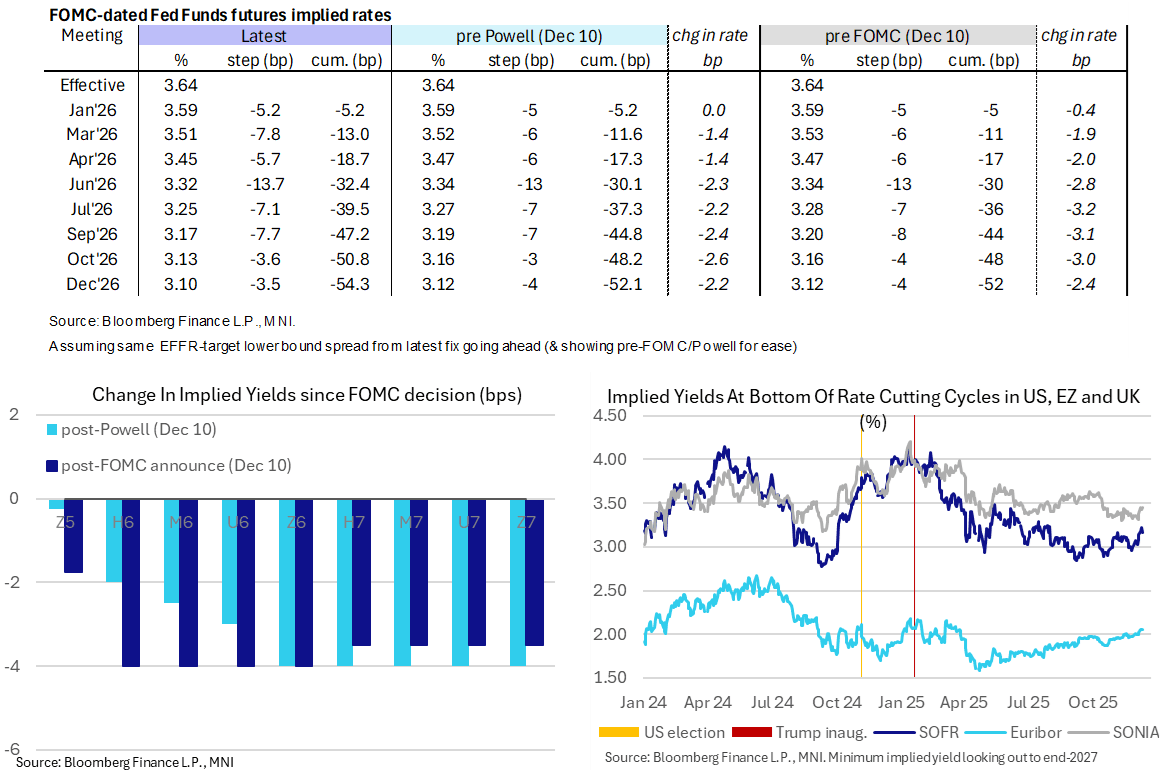
Powell has had a net dovish impact on US rates, reversing a hawkish reaction to initially patient rhetoric. The push back towards session highs has come with help from various factors including pushing back on a rate hike question, noting the post-shutdown boost to the 2026 GDP growth upgrade and discussing a weaker payrolls trend when factoring in expected downward revisions along with the labor market “cooling “maybe just a touch more gradually than we thought”.
- Fed Funds futures implied rates are 0.5-2bp lower since shortly before the FOMC announcement, with about half of that coming since Powell’s press conference.
- Cumulative cuts from an assumed 3.64% effective: 5bp Jan, 13bp Mar, 18.5bp Apr, 32.5bp Jun, 47bp Sep and 54.5bp Dec.
- SOFR futures sit up to +0.04 through 2026 contracts since the FOMC decision, with the day’s gains led by the U6 (+0.07).
- The terminal implied yield of 3.16% (Z6) is 6.5bp lower on the day but only gives back yesterday’s climb to its highest since July – it’s still more ~15bps above levels seen in late November after a recent push higher on reasonable domestic data and global factors.
- An example of patience when asked whether the Fed has taken out sufficient insurance against labor market weakness: "We're going to get a great deal of data between now and the January meeting, and I'm sure we'll talk more about that, and that will the data that we get are going to factor into our thinking.... We did some cutting, and then we paused for a while to work our way through what was happening in the middle of the year. And then we resumed cuts in September.... We're well positioned to wait and see how the economy evolves from here."
AUDUSD TECHS: Bull Wave Intact
- RES 4: 0.6723 High Oct 21 ‘24
- RES 3: 0.6707 High Sep 17 and a key resistance
- RES 2: 0.6660 High Sep 18
- RES 1: 0.6654 High Dec 12
- PRICE: 0.6648 @ 16:36 GMT Dec 10
- SUP 1: 0.6580/6559 High Nov 13 / 20-day EMA
- SUP 2: 0.6517 Low Nov 27
- SUP 3: 0.6466/21 Low Nov 26 / 21
- SUP 4: 0.6415 Low Aug 21 / 22 and a bear trigger
A strong impulsive bull wave in AUDUSD remains intact, signalling scope for a continuation near-term. Note that moving average studies have recently crossed and are in a bull-mode position, reinforcing current conditions. The pair has pierced 0.6640, 76.4% of the Sep 17 - Nov 21 bear leg. A clear breach of this level would open 0.6707, the Sep 17 high and key resistance. Key support to watch is at 0.6559, 20-day EMA.


