MNI ASIA MARKETS ANALYSIS: Senate Advances Vote on War Actions
HIGHLIGHTS
- Treasuries look to finish near session lows, heavier long selling/unwinds ahead tomorrow's employment report for December, not to mention the Supreme Court's "opinion day" regarding the Trump admin's global tariff policy.
- FX price action has remained subdued on Thursday, with a lack of impetus owing to the close proximity of tomorrow’s US payrolls data, the final labour market report for the Fed before its Jan 28 decision.
- An early release of a Hidden PDF for the Challenger jobs report in December shows job cut announcements at 35.6k for a -8% Y/Y decline from the 38.8k in Dec 2024.
- The Senate voted to advance legislation opposing further military action in Venezuela, with five Republicans joining all Democrats, Bbg.
US TSYS
MNI US TSYS: Late Treasury Roundup: Focus on Dec NFP, SCOTUS on Tariffs
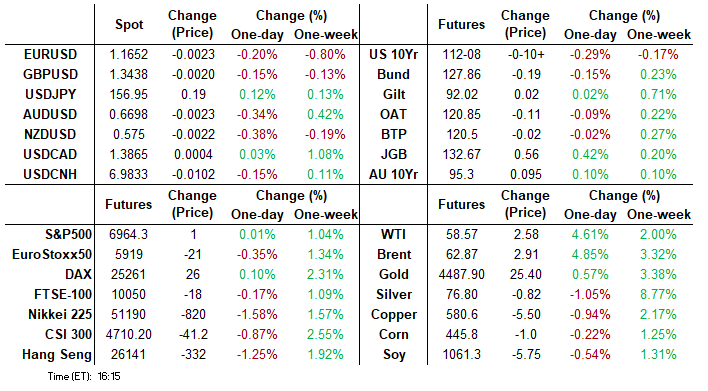
- Treasuries are holding near late session lows, curves mixed with moderately heavy volumes ahead of tomorrow's December employment report as well as SCOTUS "opinion day" that is scheduled to start at 1000ET with focus on Trump admin's global tariff policy.
- Currently, TYH6 trades -10.5 at 112-08 vs. -07.5 low, yesterday’s retreat from highs keeps the trend set-up bearish and a breach of 111-29 would confirm a resumption of the bear cycle. This would open 111-19 initially, a Fibonacci projection.
- Consensus looks for nonfarm/private payrolls growth of 69k/75k with primary dealer analysts a touch higher for nonfarm. It would see similar monthly rates to those in November after nonfarm payrolls fell heavily in October on federal government deferred resignations showing up.
- The December data will carry more signal to the market and Fed than the highly unusual November report. This is the last NFPs before the FOMC's end-January meeting, at which participants would probably require substantially weaker-than-expected NFPs to spur even consideration of another cut (4bp priced).
- Earlier Initial jobless claims were lower than expected at 208k (sa, cons 212k) in the week to Jan 3 after a still unusually low 200k in the prior week (initial 199k). Continuing claims were a little higher than expected at 1914k (sa, cons 1900k) in the week to Dec 27 after another downward revised 1858k (initial 1866k).
- An early release of a Hidden PDF for the Challenger jobs report in December shows job cut announcements at 35.6k for a -8% Y/Y decline from the 38.8k in Dec 2024. It follows the particularly sharp 175% Y/Y increase in Oct to a huge 153k (highest for an October since 2003) and a more measured 24% increase to 71k in Nov.
REFERENCE RATES
US TSYS: Repo Reference Rates
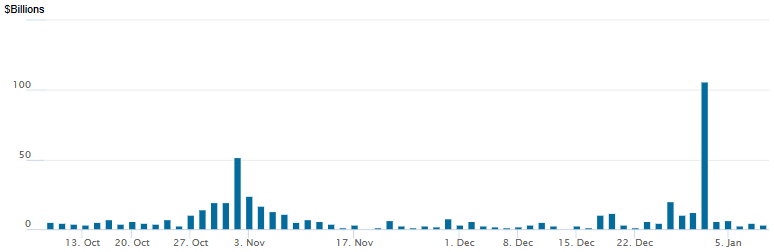
- Secured Overnight Financing Rate (SOFR): 3.65% (-0.01), volume: $3.267T
- Broad General Collateral Rate (BGCR): 3.62% (+0.00), volume: $1.348T
- Tri-Party General Collateral Rate (TCR): 3.62% (+0.00), volume: $1.315T
- (rate, volume levels reflect prior session)
STIR: FRBNY EFFR for prior session:
- Daily Effective Fed Funds Rate: 3.64% (+0.00), volume: $83B
- Daily Overnight Bank Funding Rate: 3.64% (+0.00), volume: $174B
FED Reverse Repo Operation
RRP usage slips up to $3.083B with 7 counterparties this afternoon vs. $4.582B Wednesday. Compares to December 12 low of $0.838B (lowest level since mid-March 2021); this years highest excess liquidity measure: $460.731B on June 30.
US SOFR/TREASURY OPTION SUMMARY
Mostly downside put flow from SOFR & Treasury options - with a notable exception: huge buyer short Sep'26 SOFR calls outlined below. Focus is on tomorrow's headline employment data for December and the SCOTUS opinion session (est 1000ET) on the Trump admin's global tariff actions. Underlying futures reverse early overnight gains - remain near recent session lows, curves mixed (2s10s +1.683 at 69.274; 5s30s -.753 at 111.928). Projected rate cut pricing has consolidated vs. late Wednesday levels (*): Jan'26 at -2.9bp (-4bp), Mar'26 at -11.2bp (-12.9bp), Apr'26 at -16.4bp (-18bp), Jun'26 at -30.3bp (-33bp).
SOFR Options:
over +125,000 0QU6 97.50 calls, 7.5 vs. 96.80/0.17%
+20,000 SFRU6 96.12/96.37 put spds, 1.75
+7,500 SFRZ6 96.87/97.37/98.50 2x3x1 call flys, 17.5-18.0 ref 96.88
+10,000 0QZ 97.50 calls, 8.5 ref 96.73/0.16%
-30,000 SFRM6 97.62 calls, 2.0 vs. 96.635/0.10%
+7,500 SFRG6 96.43/96.50/96.62 2x3x1 broken call flys, 1.5 ref 96.44
+10,000 SFRH6 96.43 put vs. 0QH6 x2 96.50 put, 3.75 net
+27,000 (pit/screen) 0QF6 96.62/96.75 put spds, 1.5 ref 96.86
-2,000 3QG6 96.50 straddles, 19.5 ref 96.45
+38,000 SFRH6 96.31/96.37/96.43 put trees, 3.75
Block, -5,000 SFRG6 96.31/96.87 strangles, 1.0, more in pit
1,500 SFRU6 96.87/97.25/97.37 broken call trees ref 96.82
2,000 SFRZ6 96.62/96.87 put spds ref 96.88
over 11,000 0QG6 96.62 puts outright pushes volume up to 36.5k
25,000 0QG6 96.62/96.75 put spds ref 96.90 to -.905
1,500 SFRZ6 96.50/96.75 put spds vs 0QZ6 96.25/96.37/96.75 broken put flys
3,000 0QG6 96.87 puts ref 96.885
2,000 2QH6 96.12/96.37 put spds ref 96.715
1,750 SFRZ6 96.37/97.00/97.37 broken put flys ref 96.90
Treasury Options:
4,000 TYG6 111/TYK6 110.5 put spread
2,500 TYK6 114 calls
4,000 FVG6 108 puts ref 109-05
8,000 TYG6 111.75/112.25 put spds, 12 ref 112-13
2,000 FVG6 109.25/109.5 call spds ref 109-08.25
1,115 USH6 112/114/115 1x3x2 put flys ref 115-22
1,800 wk2 TY 112 puts, 2 ref 112-15
MNI BONDS: EGBs-GILTS CASH CLOSE: Bund Rally Pauses For Breath
Core EGB yields rose Thursday for the first session this week, with Gilts outperforming Bunds and Eurozone periphery spreads tightening.
- Most of the session appeared characterized by consolidation within the prior session's trading sessions after the recent rally, with little in the way of morning macro/headline drivers.
- German factory orders beat expectations and Italian unemployment hit a new low but these weren't market movers.
- Instead, heavy corporate and sovereign supply weighed in particular on EGBs early, with issuance from Spain, France, Italy, and Portugal.
- After yields edged to session highs following mixed US data in early afternoon, there was a solid pullback in yields late in the session into the close as after the supply digestion window closed.
- The Gilt curve maintained its ongoing rally, twist steepening with the short end easily outperforming, while the German curve bear steepened.
- Periphery/semi-core EGB spreads tightened, led by BTPs.
- Friday's global focus will be the US employment report, while in Europe we get national-level industrial production data (including France and Germany) and an appearance by ECB's Lane.
Closing Yields / 10-Yr EGB Spreads To Germany
- Germany: The 2-Yr yield is up 0.5bps at 2.095%, 5-Yr is up 1.3bps at 2.411%, 10-Yr is up 1.3bps at 2.863%, and 30-Yr is up 2.1bps at 3.468%.
- UK: The 2-Yr yield is down 2.3bps at 3.656%, 5-Yr is down 0.8bps at 3.853%, 10-Yr is down 1.2bps at 4.404%, and 30-Yr is up 0.2bps at 5.159%.
- Italian BTP spread down 1.9bps at 64.6bps / French OAT down 0.7bps at 66.6bps
OPTIONS: Trade Goes Mixed After Recent Upside
Thursday's Europe rates/bond options flow included:
- RXG6 126/125ps, bought for 3 in 2k
- ERU6 96.43/96.56/96.68c fly, bought for 0.25 in 12k
- ERZ6 97.93/98.06/98.18 call fly paper paid 0.75 on 10K
- ERZ6 98.06/97.93/97.81p fly 1x3x2, bought for 1.5 in 10k
- ERZ6 98.06/97.93/97.81p fly, bought for 5.25 in 2.5k
- 2RH6 97.93 calls vs. ERH6 98.25 calls paper paid 1.25 for the mid-curve on 8.2K
- SFIH6 96.50/96.60/96.70c fly 1x3x1, bought for half in 4k
- SFIM6 96.85/75/55/35 put condor, paper pays 4.25 for 25k
MNI FOREX: Greenback Tilts Higher as US Employment Report Awaited
- FX price action has remained subdued on Thursday, with a lack of impetus owing to the close proximity of tomorrow’s US payrolls data, the final labour market report for the Fed before its Jan 28 decision. Early declines for the likes of AUD and NZD have consolidated amid a moderately softer risk backdrop, while EURUSD has been grinding steadily lower through the session.
- For AUDUSD, 0.4% declines this morning come on the back of comments from RBA Deputy Governor Hauser, who offered little guidance on possible tightening, which was interpreted as dovish at the margin considering the recent hawkish repricing. Corrective price action has narrowed the gap to initial firm support, which intersects at 0.6674, the 20-day EMA.
- EURUSD has slipped below 1.1650 in late trade, extending the pull lower from the 1.1808 high in late December. Spot has edged below support at 1.1659, the Jan 5 low, cancelling a possible reversal signal on Jan 5 - a dragonfly doji candle pattern. For now, a bearish theme appears likely to dominate from a technical perspective.
- USDJPY meanwhile continues to hold relatively contained ranges, with another attempt above the 157.00 handle today short-lived. Ahead of tomorrow’s data, it is worth highlighting the trend structure remains bullish and short-term weakness is considered corrective. MA studies are also in a bull-mode position, highlighting a dominant uptrend. Sights are on 157.89, the Nov 20 high and a bull trigger.
- All eyes will be on tomorrow’s US labour market data, while a Supreme Court ruling on the legality of the Trump tariffs could also come as early as tomorrow.
MNI US STOCKS: Late Equities Roundup: Unwinding Midweek Moves Ahead NFP, SCOTUS
- Stocks trade mixed Thursday, largely unwinding midweek moves with the DJIA recovering, outperforming the tech heavy Nasdaq in late trade. Currently, the DJIA trades up 244.67 points (0.5%) at 49240.38, S&P E-Mini Futures down 8.75 points (-0.13%) at 6954.5, Nasdaq down 157.7 points (-0.7%) at 23426.74.
- Some of the moves could be explained by repositioning ahead of tomorrows NFP data as well as the Supreme Court's opinion on Trump's tariff policy via the International Emergency Economic Powers Act (IEEPA).
- Energy and Consumer Staples sector shares led advances in the second half, oil and gas stocks buoyed the former as crude prices climbed on the day (WTI +1.80 at 57.79): APA Corp +8.27%, Texas Pacific Land +6.97%, Halliburton +5.79%, Occidental Petroleum +5.50%, ConocoPhillips +5.46%, Diamondback Energy +5.38%, Devon Energy +5.11%.
- The Staples sector was supported by a mix of household, food & beverage and distribution stocks: Bunge Global +6.86%, Archer-Daniels-Midland +6.41%, Colgate-Palmolive +5.23%, Costco Wholesale +4.75%, Target +4.62%, Constellation Brands +4.33% and Sysco Corp +3.62%.
- As noted, IT sector shares unwound a portion of Wednesday’s gains: Seagate Technology Holdings -9.28%, Western Digital -7.88%, Sandisk Corp -7.00%, Datadog -6.65%, Autodesk -5.85% and Arista Networks -5.26%.
- Meanwhile, the Health Care sector was weighed down by pharmaceutical stocks as the Trump administration continues to unwinding vaccine mandates & recommendations: Moderna -5.18%, Incyte -4.87%, AbbVie -3.89%, Dexcom -3.57% and Amgen -3.23%.
MNI EQUITY TECHS: E-MINI S&P: (H6) Still Looking For Gains
- RES 4: 7080.92 0.764 proj Nov 21 - Dec 11 - 18 price swing
- RES 3: 7021.79 0.618 proj Nov 21 - Dec 11 - 18 price swing
- RES 2: 7014.00 High Oct 30 and the bull trigger
- RES 1: 7006.75 High Jan 7
- PRICE: 6954.00 @ 14:32 GMT Jan 9
- SUP 1: 6873.57 50-day EMA
- SUP 2: 6771.50 Low Dec 18 and a key support
- SUP 3: 6684.50 Low Nov 24
- SUP 4: 6583.00 Low Nov 21 and a reversal trigger
The trend condition in S&P E-Minis remains bullish and price continues to trade above key near-term support at 6771.50, the Dec 18 low. Clearance of this level is required to signal scope for a deeper retracement and would also highlight a possible short-term reversal. For bulls, sights are on key resistance at 7014.00, the Oct 30 high. A move through this hurdle would confirm a resumption of the primary uptrend.
MNI COMMODITIES: Crude Rebounds, Precious Metals Extend Decline
- WTI crude has risen today, more than reversing yesterday’s losses, as the market assesses heightened geopolitical risk in Venezuela, weighed against expectations for an oil market surplus this year.
- WTI Feb 26 is up 3.2% at $57.8/bbl.
- President Trump believes US control of Venezuela’s oil industry will push prices down to $50/bbl, apparently his preferred level, according to the WSJ.
- US Energy Secretary Wright said that with US support, Venezuelan oil output could rise 50% in 18 months.
- Meanwhile, oil executives will meet with President Trump tomorrow to discuss rebuilding Venezuela’s energy sector, according to Bloomberg.
- The trend structure in WTI futures remains bearish and recent gains appear to have been corrective. A clear resumption of the bear leg would signal scope for a move towards $53.77, a Fibonacci projection. Initial resistance is at $58.29, the 50- day EMA.
- Elsewhere, precious metals have declined again today, ahead of annual index rebalancing in the coming days, which could weigh particularly on silver.
- Gold has edged down 0.1% to $4,452/oz, while silver has fallen a further 3% to $75.9/oz, taking total losses the last two sessions to almost 7%.
- The trend structure in gold remains bullish and a resumption of gains would open $4,578.3, a Fibonacci projection. First support is $4,370.2, the 20-day EMA.
- Similarly, trend signals in silver remain bullish, with the recent sharp pullback also appearing to be corrective. First important support lies at $71.14, the 20-day EMA.
FRIDAY DATA CALENDAR
| Date | GMT/Local | Impact | Country | Event |
| 09/01/2026 | 0700/0800 | ** |  DE | Trade Balance |
| 09/01/2026 | 0700/0800 | ** | DE | Industrial Production |
| 09/01/2026 | 0700/0800 | ** |  SE | Private Sector Production m/m |
| 09/01/2026 | 0700/0800 | *** |  NO | CPI Norway |
| 09/01/2026 | 0745/0845 | * |  FR | Industrial Production |
| 09/01/2026 | 0745/0845 | ** | FR | Consumer Spending |
| 09/01/2026 | 0800/0900 | ** |  ES | Industrial Production |
| 09/01/2026 | 0800/0900 | ** |  CH | Unemployment |
| 09/01/2026 | 0900/1000 | * |  IT | Retail Sales |
| 09/01/2026 | 1000/1100 | ** |  EU | EZ Retail Sales |
| 09/01/2026 | 1200/0700 | ** |  BR | Brazil Final CPI |
| 09/01/2026 | 1245/1345 | EU | ECB Lane Keynote at Danish Economy Conference | |
| 09/01/2026 | 1330/0830 | *** |  CA | Labour Force Survey |
| 09/01/2026 | 1330/0830 | *** | CA | Labour Force Survey |
| 09/01/2026 | 1330/0830 | *** |  US | Housing Starts |
| 09/01/2026 | 1330/0830 | *** | US | Housing Starts |
| 09/01/2026 | 1330/0830 | *** | US | Employment Report |
| 09/01/2026 | 1330/0830 | *** | US | Employment Report |
| 09/01/2026 | 1330/0830 | *** | US | Employment Report |
| 09/01/2026 | 1330/0830 | *** | US | Employment Report |
| 09/01/2026 | 1330/0830 | *** | US | Employment Report |
| 09/01/2026 | 1330/0830 | *** | US | Employment Report |
| 09/01/2026 | 1500/1000 | *** | US | U. Mich. Survey of Consumers |
| 09/01/2026 | 1500/1000 | ** | US | University of Michigan Surveys of Consumers Inflation Expectation |
| 09/01/2026 | 1500/1000 | US | Minneapolis Fed's Neel Kashkari | |
| 09/01/2026 | 1800/1300 | ** | US | Baker Hughes Rig Count Overview - Weekly |
| 09/01/2026 | 1800/1300 | ** | US | Baker Hughes Rig Count Overview - Weekly |
| 09/01/2026 | 1800/1300 | ** | US | Baker Hughes Rig Count Overview - Weekly |
| 09/01/2026 | 1835/1335 | US | Richmond Fed's Tom Barkin |


