US STOCKS: Late Equities Roundup: Unwinding Midweek Moves Ahead NFP, SCOTUS
Jan-08 19:49
- Stocks trade mixed Thursday, largely unwinding midweek moves with the DJIA recovering, outperforming the tech heavy Nasdaq in late trade. Currently, the DJIA trades up 244.67 points (0.5%) at 49240.38, S&P E-Mini Futures down 8.75 points (-0.13%) at 6954.5, Nasdaq down 157.7 points (-0.7%) at 23426.74.
- Some of the moves could be explained by repositioning ahead of tomorrows NFP data as well as the Supreme Court's opinion on Trump's tariff policy via the International Emergency Economic Powers Act (IEEPA).
- Energy and Consumer Staples sector shares led advances in the second half, oil and gas stocks buoyed the former as crude prices climbed on the day (WTI +1.80 at 57.79): APA Corp +8.27%, Texas Pacific Land +6.97%, Halliburton +5.79%, Occidental Petroleum +5.50%, ConocoPhillips +5.46%, Diamondback Energy +5.38%, Devon Energy +5.11%.
- The Staples sector was supported by a mix of household, food & beverage and distribution stocks: Bunge Global +6.86%, Archer-Daniels-Midland +6.41%, Colgate-Palmolive +5.23%, Costco Wholesale +4.75%, Target +4.62%, Constellation Brands +4.33% and Sysco Corp +3.62%.
- As noted, IT sector shares unwound a portion of Wednesday’s gains: Seagate Technology Holdings -9.28%, Western Digital -7.88%, Sandisk Corp -7.00%, Datadog -6.65%, Autodesk -5.85% and Arista Networks -5.26%.
- Meanwhile, the Health Care sector was weighed down by pharmaceutical stocks as the Trump administration continues to unwinding vaccine mandates & recommendations: Moderna -5.18%, Incyte -4.87%, AbbVie -3.89%, Dexcom -3.57% and Amgen -3.23%.
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
US STOCKS: Late Equities Roundup: DJIA Reverse Course, Pharma/Banks Weaker
Dec-09 2025 19:46
- Stocks are trading near steady (SPX eminis) to mixed late Tuesday, the DJIA underperforming as Treasuries tested technical support and forward rate cut pricing projections consolidated ahead what is still expected to be a 25bp cut by the FOMC tomorrow.
- Currently, the DJIA trades down 130.26 points (-0.27%) at 47612.78, S&P E-Mini Futures down 3.25 points (-0.05%) at 6852.5, Nasdaq up 33 points (0.1%) at 23578.05.
- Health Care and Financials sector shares led declines in the second half:
- Weighing on the former: Solventum Corp -2.77%, Merck & Co -1.94%, Humana Inc -1.90%, Bristol-Myers Squibb -1.55% and Gilead Sciences -1.36%.
- Of note, Pfizer is down appr 1% as Bloomberg reports the FDA is investigating whether the Covid-19 vaccine shots caused deaths in adults as part of a safety review that appears to be larger in scope than previously thought.
- Meanwhile, JPMorgan Chase fell -4.39% after warning of higher than expected operating costs, Wells Fargo -1.24%, Citigroup -1.17% and Bank of America -1.06%.
- On the positive side, Energy and Consumer Discretionary sector shares led advances in late trade:
- Targa Resources +3.42%, Exxon Mobil +2.22%, Halliburton +1.44% and Kinder Morgan +0.99%.
- Ulta Beauty +2.49%, Airbnb +2.45%, Tesla +2.16% and Best Buy Co +2.03%.
COMMODITIES: Crude Falls Amid Oversupply Fears, Silver Surges to Record High
Dec-09 2025 19:38
- WTI crude has fallen towards the lower end of the recent trading range on Tuesday oversupply fears as the market awaits updated projections for the future market balance this week.
- With a Ukraine peace deal again looking elusive and Russia likely to continue to find ways around sanctions, the market is focused on the supply outlook with a record market surplus forecast for 2026.
- WTI Jan 26 is down by 1.1% at $58.2/bbl.
- For WTI futures, moving average studies are in a bear-mode position, highlighting a dominant downtrend. Key support and the bear trigger is at $55.99, the Oct 20 low.
- Meanwhile, silver has risen to a fresh record high today, with price up by over 4% to $60.7/oz to take YTD gains to 110%.
- As noted, daily ETF flows have supported upside in silver, which has also been boosted by tight physical supply.
- A breakdown in the Gold/Silver ratio may also have exacerbated recent outperformance in silver. With gold rising by just 0.4% to $4,209/oz today, that ratio has fallen below 70, its lowest level since July 2021.
- Trend signals in silver remain bullish, with sights on $60.852 next, a Fibonacci projection point.
- Elsewhere, copper has fallen by 2.2% to $532/lb, with no obvious trigger for the move. Despite this, price remains 7% above the Nov 5 low, amid concerns over tight global supplies.
- From a technical perspective, next resistance is seen at $550.00, the Jul 9 and 28 lows.
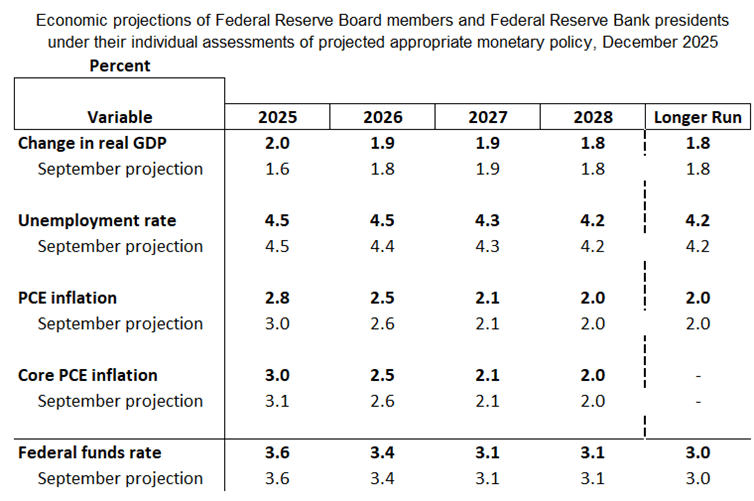
FED: SEP/Dot Plot: Slight Upgrade To GDP, Downshift To Inflation (2/2)
Dec-09 2025 19:35
As for the new macroeconomic projections, there’s likely to be a slight upgrade to GDP forecasts with some downshifting of PCE inflation in 2025/2026.
- There is some risk that the unemployment rate forecast shifts up slightly for 2025 but anything above 4.5% would be a major surprise.
Trending Top

Sep-18 18:49
Sep-18 17:27

