US IG FINANCIALS: US Banks: Week in Review
US Banks: Week in Review
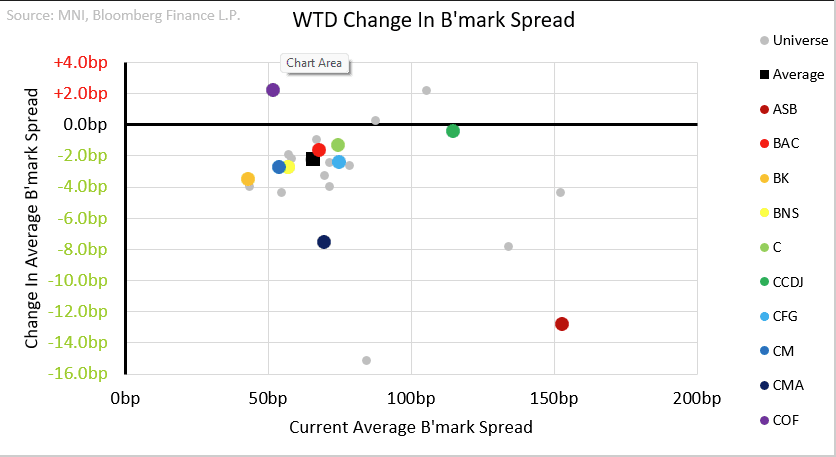
Bank Sr Unsecured spreads overall tightened 2bps for the week, while Bank Subs tightened 3bps. Banks started reporting 4Q, with results overall showing growth led by capital markets and wealth and mid single digit loan and NII growth. The outlook includes repurchases and potential M&A as many banks manage down capital ratios on shifting regulatory capital requirements. Post-earnings new issuance from JPM, WFC, MS, GS received strong interest, with ~25-30bps compression from IPT. In the news, Trump's comments on credit card rate caps impacted card issuers like COF (#1 US card issuer post its DFS acquisition.
Regional Banks Key news
US Bancorp buying BTIG for up to $1B
Credit neutral. USB like larger regionals have some investment banking business; this will enhance its scale and scope of services to institutional investors. Even though this is a bolt-on size deal, execution is key, and the risk here is tempered by the 2 companies’ past collaborations.
https://www.mnimarkets.com/articles/us-bancorp-buying-btig-for-up-to-dollar1b-1768312434563
US Bank Shares Tumble as Trump Slams Credit Card Rates (1) -bbg
Regional & Custody Bank earnings
PNC 4Q25
Credit neutral. Strong quarter, beat consensus, with mid single digit NII and loan growth and healthy asset quality. Fee revenues up double digits, led by Capital Markets with Card/Cash Management and other services seeing steady growth.
https://www.mnimarkets.com/articles/pnc-4q25-1768569433727
State Street 4Q25 (STT)
Credit neutral. Good quarter on growth in servicing fees generated by its market- leading global custody business, though expenses up on big investments and move into digital assets could introduce potential risks.
https://www.mnimarkets.com/articles/state-street-4q25-stt-1768583356509
M&T Bank Corp 4Q25 (MTB)
Credit neutral. Stable modest loan growth to pick up 2026, credit quality healthy, loans to CRE ~17%, loans to NDFI ~9%. Continue to adjust CET1 down to target range, via buybacks. Buybacks for now, but CEO sees possible M&A down the road.
(Baa1/BBB+/A)
https://www.mnimarkets.com/articles/mandt-bank-corp-4q25-mtb-1768574097839
Regions Financial 4Q25 (RF)
Credit neutral, with NII and NIM rising while loans flat on managed runoff of leveraged loans, while general commitments projects modestly rising loan growth. Asset quality metrics healthy.
https://www.mnimarkets.com/articles/regions-financial-4q25-rf-1768578592278
Issuance
Goldman Sachs new deal priced within 0-3bps of FV
Morgan Stanley new deal came within up to 3bps of FV
Wells Fargo came within up to 15bps of FV
JP Morgan new deal priced within 1-2bps of FV
National Bank of Canada new 3NC2 priced at +63 slightly inside FV + 65a, now trading +59
JEF comes to market post earnings with new 10Y +143 vs our FV +145a
https://www.mnimarkets.com/articles/jefferies-dollarbenchmark-10y-fv-1768316286910
https://www.mnimarkets.com/articles/jefferies-4q25-jef-1767830184520
JPM’s $6B 3-part new deal comes to market at no concession with 6NC5 at +63, 11NC10 at +76.
4Q25
Aviation Capital Group new 144A: long 3Y +83, 7Y +115, comes at 30+ tight to IPT.
https://www.mnimarkets.com/articles/aviation-capital-group-dollarbmark-guidance-1768410906356
Bank of NY post-earnings new 4NC3 priced at +47 flat to our FV
https://www.mnimarkets.com/articles/bny-mellon-dollarbmark-fv-1768402749729
MassMutual FA-backed 3Y priced at +50 or 5 wide of our FV
https://www.mnimarkets.com/articles/massmutual-dollarbenchmark-fa-backed-3y-3y-frn-fv-1768403835616
Bank Sr Unsecured spreads:
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
AUD: AUD/USD - Trades Heavy Around 0.6600 As Risk Sentiment Sours
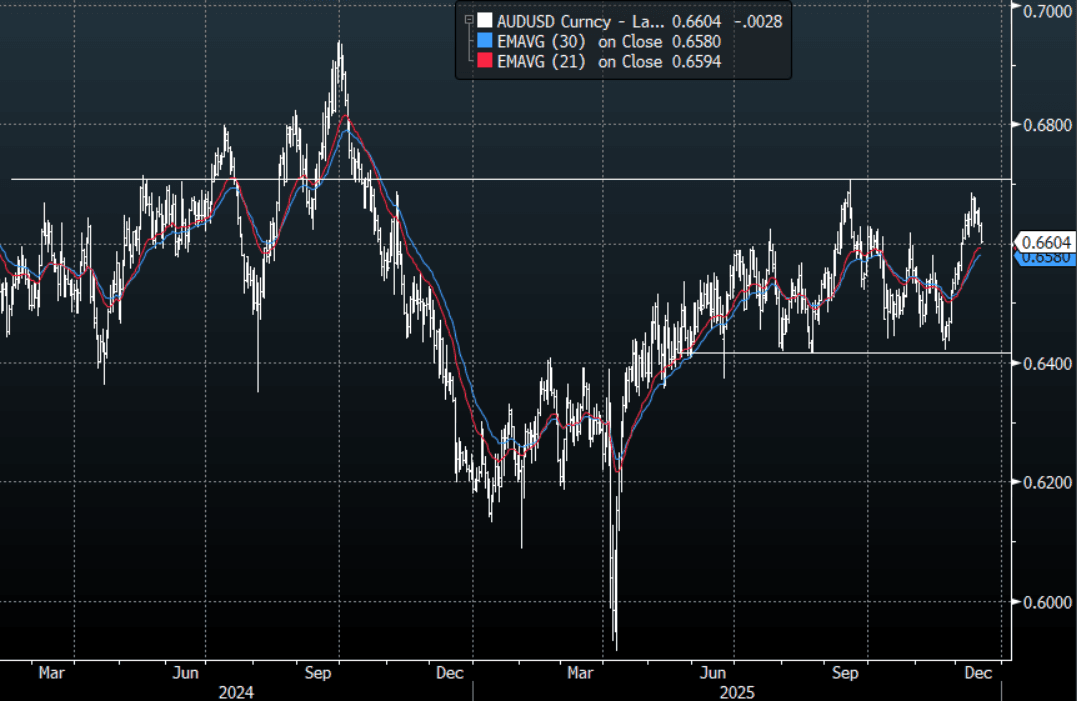
The AUD/USD had a range overnight of 0.6599-0.6629, Asia is trading around {AUDUSD Curncy}. The bounce in AI lasted 1 day and is lower again, the move is starting to turn ugly as sentiment is quickly changing. The NASDAQ and the S&P both look to potentially be putting in double tops and the likes of Nvidia is approaching some pivotal levels as well. This does not augur well for risk and creates significant headwinds for the AUD which trades with a high correlation to it. The AUD price action for the moment remains constructive, but I do remain wary of what seems to be happening in US stocks. Technically while the AUD remains above 0.6500-0.6550 dips should continue to be supported. In the Asian session, watch to see if this 0.6600 area can continue to hold in the face of this souring in sentiment, if not we could see a deeper pullback towards the 0.6500-50 support. On the day I suspect sellers would be looking to fade a bounce back toward the 0.6625-0.6645 area initially looking to see if we can break back below 0.6600.
- Bloomberg reports, “China Vanke asked some commercial banks to accept delayed interest payments on certain borrowings, people familiar said. At least one lender was asked to let the developer delay an interest obligation by one year.”
- Options : Closest significant option expiries for NY cut, based on DTCC data: 0.6550(AUD1.07b), 0.6625(AUD849m), 0.6675(AUD989m). Upcoming Close Strikes : 0.6675(AUD1.31b Dec 19), 0.6700(AUD1.57b Dec 19) - BBG
- The AUD/USD Average True Range for the last 10 Trading days: 40 Points
- Data/Event: Consumer Inflation Expectation
Fig 1: AUD/USD spot Daily Chart
Source: MNI - Market News/Bloomberg Finance L.P
US PREVIEW: Analysts Generally Expect Upside CPI Pressure Coming From Core Goods
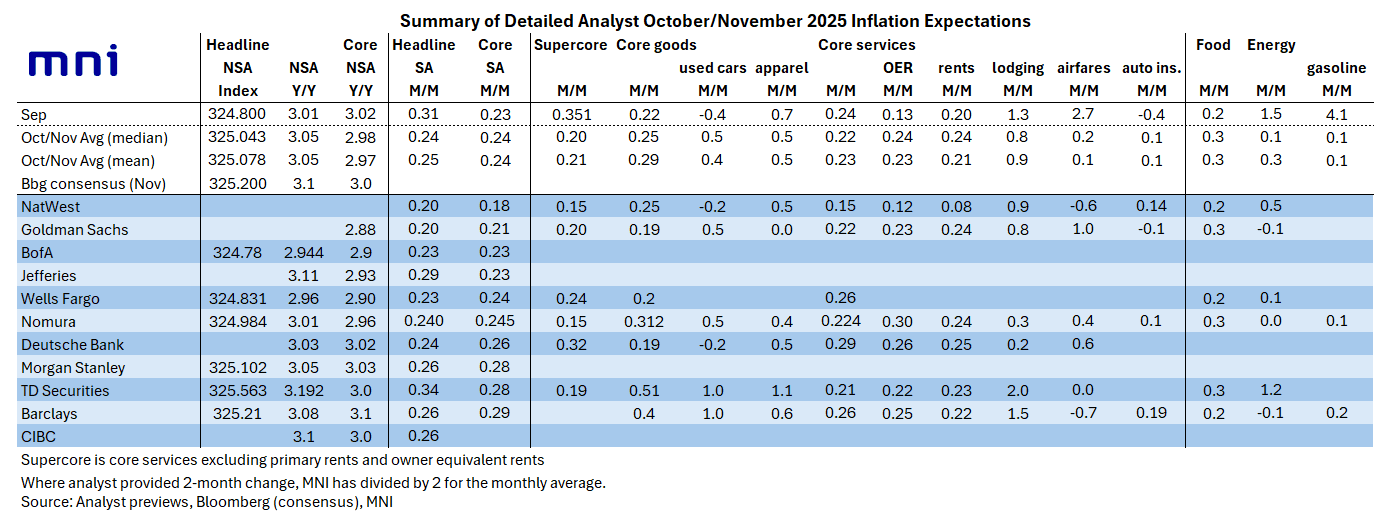
Our compilation of sell-side analyst expectations for Thursday's CPI report uses a narrower range of previews - namely, those that included core CPI forecasts to two decimal places or more for the 2-month or Oct and Nov % M/M changes. Within a range of 0.18-0.29% for average core CPI % M/M over October and November, Barclays is at the high end of expectations while NatWest is at the low end. A few summaries below:
- Barclays: Core CPI to average 0.29% M/M across Oct-Nov (two-month cumulative increase of 0.58%), with headline averaging 0.26% M/M (two-month cumulative of 0.52% M/M). “We expect the uptick to be led mainly by core goods prices, which we forecast to have sequentially accelerated over the prior two months, led by a rebound in used cars prices and firmer inflation across the remaining core goods basket. We estimate services inflation to have also gathered steam, partly led by a rebound in OER CPI following the downside surprise in September.”
- Nomura: Core CPI to average 0.245% M/M across Oct-Nov (0.228% Oct, 0.263% Nov); headline 0.24%. "We expect core goods inflation remained strong due to tariff effects as well as higher used vehicle prices...The recent firming of import prices and further tariff passthrough likely pushed up non-auto core goods prices, which leads us to forecast continued strength in apparel and other goods prices in October and November...Supercore service inflation likely slowed due to lower health insurance prices and other volatile service prices, while inflation of rent-related components likely rebounded after a temporary slowdown in September."
- Goldman Sachs: Core CPI to average 0.21% M/M across Oct-Nov (0.16% Nov, 0.25% Oct), headline CPI to average 0.20% M/M across Oct-Nov (0.27% Nov, 0.14% Oct). “we have penciled in upward pressure from tariffs on goods categories that are particularly exposed worth +0.08pp on core inflation on average across October and November”
- NatWest: Core CPI to average 0.18% M/M across Oct-Nov (cumulative 0.35%), headline CPI to average 0.20% M/M across Oct-Nov (cumulative 0.40%)."we suspect it will be extremely challenging to try to draw many firm conclusions and suggest market participants use caution interpreting any surprises in the upcoming report...Within the details, we project that core goods prices increased 0.5% and core services advanced 0.3% (and core services ex rents +0.3%).”
ASIA: Coming Up In Asia Pac Markets On Thursday
| 2145BST | 0545HKT | 0845AEDT | New Zealand Q3 GDP |
| 2350BST | 0750HKT | 1050AEDT | Japan Weekly Investment Flows |
| 0000BST | 0800HKT | 1100AEDT | Australia Dec Consumer Inflation Expectation |
| 0100BST | 0900HKT | 1200AEDT | China Nov Swift Global Payments CNY |
| 0330BST | 1130HKT | 1430AEDT | Japan 3mth Bill Sale |
Source: Bloomberg Finance L.P./MNI


