US IG CREDIT SUPPLY: Aviation Capital Group $Bmark Guidance
Jan-14 17:15
Aviation Capital Group $Bmark Guidance
- Guidance Long 3Y +83# / IPT +115a / FV Long 3Y 92a
- Guidance 7Y +115# / IPT +145a / FV +120a
- Issuer: Aviation Capital Group LLC (ACGCAP)
- Format: 144A/Reg S without reg rights, senior unsecured
- Baa2/BBB- (expected)
- Bookrunners: BofA, JPM, RF, TSI, WFS
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
PIPELINE: Corporate Bond Update: $1B Willis North America 2Pt Launched
Dec-15 2025 17:08
- Date $MM Issuer (Priced *, Launch #)
- 12/15 $1B #Willis North America $700M +5Y +85, $300M +10Y +98
- 12/15 $550M Perimeter Holdings 8NC3
OPTIONS: Larger FX Option Pipeline
Dec-15 2025 17:06
- EUR/USD: Dec17 $1.1700(E1.2bln), $1.1750(E1.2bln), $1.1800(E1.5bln); Dec18 $1.1550(E1.9bln), $1.1600(E1.3bln), $1.1750(E2.6bln), $1.1797-00(E1.2bln); Dec19 $1.1650(E1.1bln), $1.1675-80(E2.0bln), $1.1750(E1.7bln), $1.1785-00(E4.2bln), $1.1900(E2.0bln)
- USD/JPY: Dec18 Y155.00($3.0bln), Y156.00($3.1bln), Y156.25($2.3bln), Y157.00($4.0bln), Y158.00($4.8bln), Y158.50($1.9bln), Y159.00($6.5bln); Dec19 Y155.00($2.0bln)
- EUR/GBP: Dec19 Gbp0.8800(E1.3bln)
- AUD/USD: Dec18 $0.6540-50(A$1.6bln), $0.6665-75(A$1.3bln); Dec19 $0.6675(A$1.1bln), $0.6700(A$1.6bln)
- AUD/NZD: Dec17 N$1.1410(A$1.5bln)
- USD/CAD: Dec19 C$1.3800($940mln), C$1.3825($1.7bln), C$1.3900($1.7bln), C$1.3950($1.2bln)
US DATA: Empire Manufacturing Activity Weaker, But Inflation Signals Mixed
Dec-15 2025 17:05
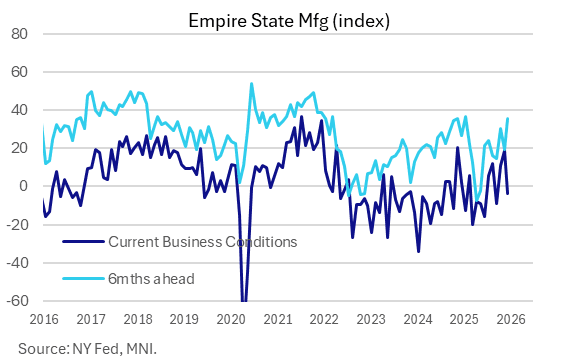
Manufacturing activity in the greater New York region unexpectedly pulled back in December, per the Empire State Manufacturing Survey's General Business Conditions index dropping to -3.9 from 18.7 prior. That compares to a positive 10.0 expected, and November's reading which was one of the highest in the last 3 years. This starts the month's regional Fed surveys on a cautious note in terms of activity, and while input price pressures are clearly moderating, expected future selling prices notably continued to tick up.
- The internals were mostly weaker, with New Orders notably plummeting to a 3-month low 0.0 (15.9 prior) but Employment ticking up to 7.3 after 6.6 for a 5-month high and one of the best readings since 2022 after 3 months of advances.
- The national ISM equivalent to this index reading would be 50.0, a 3-month low and suggestive of flat activity, with Shipments, Delivery Times and Inventory Levels also slipping.
- The 6-month ahead index however jumped to 35.7 from 19.1 for an 11-month high, suggesting that regional manufacturers are hopeful that the current lull is temporary.
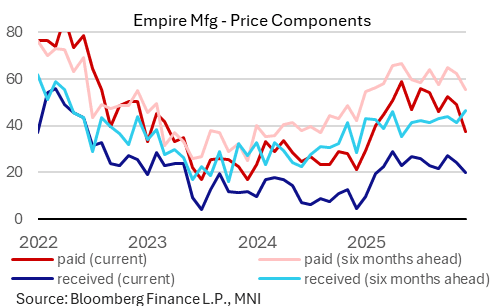
- Inflation gauges were notably softer: current prices paid fell over 11 points to an 11-month low 37.6, with prices received and future (6-months) prices paid also falling.
- Intriguingly though, future prices received ticked up to a 44-month high, suggesting possible expectations that higher prices can be demanded of end-consumers. As such we wouldn't interpret the report as unambiguously disinflationary.
Trending Top

Oct-23 15:09
Oct-23 12:16

