MNI ASIA MARKETS ANALYSIS:From Domestic Data to Geopol Drivers
HIGHLIGHTS
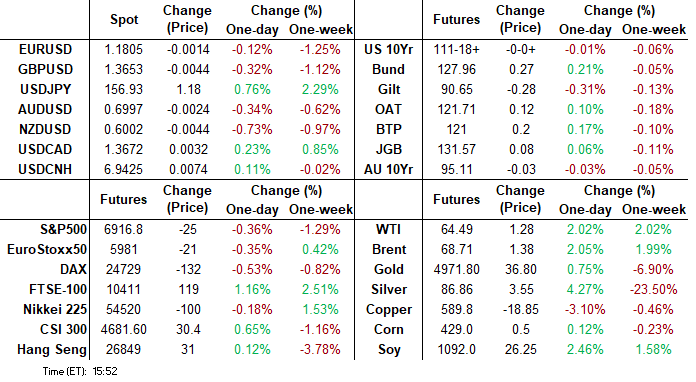
- Treasuries had bounced off lows/extended modest session highs after Axios reported some doubt over US/Iran talks still occurring this Friday, Crude prices jumped while stocks extended lows (Nasdaq -525.0).
- Talks "back on" saw crude retreat from earlier highs, WTO appr 64.15 vs. 65.53 high, Stocks are reacting positively (Nasdaq still underperforming with chip and software services stocks underperforming).
- Economic data to resume with stop-gap funding bill through September signed by Pres Trump late Tuesday, JOLTS expected Thursday at 1000ET, NFP on Feb 11, CPI pushed to Feb 13.
- Pres Trump said he will visit China in April as he shared details of call with Pres Xi Wednesday after discussing trade, Taiwan and the military.
US TSYS
MNI US TSYS: Modest Late Day Reversal W/ US/Iran Talks "Back On", Domestic Data Resumes
- Treasuries see-sawed back in range late Monday, curves twisting steeper with the short end outperforming after the bell (2s10s +2.227 at 71.610).
- Currently, TYH6 trades -.5 at 111-18.5 (111-15.5 low / 111-23.5 high), gains are considered corrective and for bears, sights are on key support at 111-09, the Jan 20 low. Clearance of this level would confirm a resumption of the downtrend.
- Risk-off to risk-on (less off): midday support for Tsys, equities weaker after Axios story making the rounds that plans for US/Iran talks on Friday are collapsing w/subject of nuclear weapons, missile program a non-starter.
- The geopol risk narrative cooled late: US Iran talks "back on" according to Barak Ravid posts on X - crude retreated from earlier highs, WTO appr 64.50 vs. 65.53 high. Stocks reacting positively (Nasdaq still underperforming with chip and software services stocks underperforming).
- Economic data to resume with stop-gap funding bill through September signed by Pres Trump late Tuesday, JOLTS expected Thursday at 1000ET, NFP on Feb 11, CPI pushed to Feb 13. Both the BOE and ECB decisions expected too.
- The USD index has matched the most recent recovery highs at 97.73 and has weighed on the precious metals space, with spot gold briefly extending an impressive intraday pullback to print around $4,850 after reaching a $5,091 high overnight.
- Meanwhile earnings expected after the close include: Allstate Corp, McKesson Corp, Alphabet Inc, O'Reilly Automotive, Coherent Corp, Snap Inc and QUALCOMM.
REFERENCE RATES
US TSYS: Repo Reference Rates
- Secured Overnight Financing Rate (SOFR): 3.69% (+0.00), volume: $3.268T
- Broad General Collateral Rate (BGCR): 3.66% (+0.00), volume: $1.334T
- Tri-Party General Collateral Rate (TCR): 3.66% (+0.00), volume: $1.297T
- (rate, volume levels reflect prior session)
STIR: FRBNY EFFR for prior session:
- Daily Effective Fed Funds Rate: 3.64% (+0.00), volume: $107B
- Daily Overnight Bank Funding Rate: 3.64% (+0.00), volume: $188B
FED Reverse Repo Operation
RRP usage inches up to $2.414B with 18 counterparties this afternoon vs. $1.785B Tuesday. Compares to December 12 low of $0.838B (lowest level since mid-March 2021); this years highest excess liquidity measure: $460.731B on June 30.

US SOFR/TREASURY OPTION SUMMARY
SOFR options continued to lean toward downside puts Wednesday, Tsy options leaning towards low delta calls, volumes gradually improving. Underlying futures mildly mixed, inside narrow ranges w/ curves twisting steeper (2s10s +2.027 at 71.410). Economic data back on with the re-opening of US gov, delayed JOLTS jobs data expected tomorrow along with weekly claims (Fri's NFP pushed to next Wed, Jan 11). Projected rate cut pricing largely in-line with late Tuesday levels (*): Mar'26 at -2.6bp, Apr'26 at -6.6bp (-6.4bp), Jun'26 at -17.8bp (-17.9bp), Jul'26 at -26.1bp (-25.9bp).
SOFR Options:
+5,000 0QK6 96.50/96.75 put spds, 10.0 vs. 96.75/0.26%
-1,000 2QZ6 96.37 straddles, 57.0 ref 96.425
+5,000 SFRH6 97.75 calls, cab
Block, 8,000 SFRM6 96.37/97.00 call over risk reversals, 1.0 vs. 96.525/0.37%
+4,000 SFRH7 96.00/96.25 put spds, 3.25 ref 96.75
-10,000 SFRZ6 96.37/96.43/96.50 put trees, 2.5
+3,000 SFRG6/SFRH6 96.37/96.37 call spd spd, .25
2,000 SFRZ7 96.62 straddles, 75.0
+5,000 SFRZ6 96.87/97.00/97.12/97.25 call condors vs. 96.25/96.37 put spds, 0.0 net
+5,000 SFRJ6 96.31/96.43 put spds, 2.0 ref 96.52
over 11,400 SFRZ6 96.87/97.00 call spds
2,000 SFRJ6 96.43 puts, 2.5 ref 96.52
-10,000 2QH6 96.37/96.50 put spds, 3.0 ref 96.605/0.10%
2,000 SFRK6 96.37/96.50/96.62 iron flys, 9.5 ref 96.52
+2,000 SFRK6 96.43/96.50/96.56/96.62 call condors, 1.5 ref 96.525
+1,000 SFRH6 96.31/96.37/96.50 2x3x1 broken put flys, 3.5 ref 96.36
-2,000 SFRH6 96.37 puts, 3.75
-7,750 SFRM6 96.43 puts, 5.0 ref 96.52
+2,000 0QZ6 97.25 calls, 10.5 ref 96.65
Treasury Options:
+50,000 TYH6 118.25 calls, cab-7
Block, +10,833 TYH6 113.5 calls, 3 vs. 111-24/0.7%
3,000 TYJ6 113 calls, 14 ref 111-11
5,000 TUM6 103.75/104.75 strangles ref 104-06.88
3,000 TYJ6 110.5/111.5/112.5 call flys, ref 111-12
5,000 TYH6 111.5/111.75 strangles, 38
over +23,000 Wednesday wkly US 115 calls, 6 (exp today)
+3,500 Wednesday wkly TY 111/111.5/112 call flys, 23 (exp today)
1,000 USH6 111/113 put spds ref 114-20
1,600 TYH6 110.75 puts, 5 ref 111-18
+1,500 TYH6 110 puts, 2 vs. 111-12/0.05%
-2,000 FVH6 109/110.5 1x2 call spds, 5.5 ref 108-22.75
+2,000 TYH6 113/114.5 call spds, 3 ref 111-24/0.08%
+3,000 Wednesday wkly TY 111.75/112 1x2 call spds, 2 vs. 111-23.5/0.08%
MNI BONDS: EGBs-GILTS CASH CLOSE: Gilts Underperform On Heightened Pol Risk Concerns
Gilts badly lagged across the European government bond space Wednesday on a perceived heightening in political risk.
- The prediction-market implied probability rose that UK Prime Minister Starmer would leave office prematurely amid a scandal involving his appointee as US ambassador (Mandelson). In turn this heightened concerns over the UK fiscal trajectory, seeing the Gilt curve bear steepen.
- Earlier in the session, Eurozone flash January headline HICP was in line with consensus, with some variation in subcomponents; Italian flash inflation printed stronger than expected. Overall data had little impact on EGBs.
- The German curve bull flattened on the day, boosted by a pullback in European equities, with periphery/semi-core EGB spreads widening as part of a risk-off move.
- Industrial data is of some interest Thursday including German Factory Orders, but the clear focus will be central bank decisions.
- Those are of course the BOE (MNI preview) and ECB (MNI preview).
Closing Yields / 10-Yr EGB Spreads To Germany
- Germany: The 2-Yr yield is down 2.9bps at 2.094%, 5-Yr is down 3.2bps at 2.431%, 10-Yr is down 3.2bps at 2.859%, and 30-Yr is down 2.6bps at 3.524%.
- UK: The 2-Yr yield is up 0.7bps at 3.715%, 5-Yr is up 1.3bps at 3.966%, 10-Yr is up 2.9bps at 4.546%, and 30-Yr is up 4.4bps at 5.332%.
- Italian BTP spread up 0.4bps at 61.1bps / French OAT up 1.2bps at 58.8bps
MNI EGB OPTIONS: Dovish Rate Structures Continue To Stand Out
Wednesday's Europe rates/bond options flow included:
- OEH6 116.50/116.75/117.00/117.25c condor, bought for 6 in 2.65k
- RXH6 128.50/129.00cs 1x2, bought for 1 in 4k.
- RXH6 127/126ps 1x2, sold the 1 at in 2k
- ERU6 98.625/99.00cs, trades for half in 7k
- 0RM6 97.75/97.62/96.50p fly 1x3x2, bought for 0.25 in 3.5k
- SFIK6 96.50/96.60/96.65/96.75c condor, bought for 4.75 in 10k
- SFIK6 96.80/96.70/96.55/96.35p condor, bought for 4.75 in 5k
MNI FOREX: US Dollar Maintains Constructive Tone, NZD and SEK Underperform
- The US dollar has traded with a supportive tone on Wednesday, assisted by bouts of risk off sentiment prompting equity weakness and oil strength. Late headlines from Axios suggesting that plans for Iran nuclear talks are collapsing has exacerbated this dynamic.
- The USD index has matched the most recent recovery highs at 97.73 and has weighed on the precious metals space, with spot gold briefly extending an impressive intraday pullback to print around $4,850 after reaching a $5,091 high overnight.
- AUD, NZD and JPY are among the worst performing majors, while the Swedish krona is at the bottom of the G10 leaderboard following some dovish innovations within the latest Riksbank minutes.
- NZDUSD has extended Wednesday’s decline to around 0.9%, slipping back below 0.6000 in the process. This follows a mixed set of Q4 employment data, failing to sustain the Kiwi’s recent bullish momentum. Support levels to note for the pair intersect at 0.5930 (20-day EMA) before more meaningful support at the prior break level around 0.5850.
- USDJPY has consolidated above 156.50 today, extending the recovery from last week’s lows to 3% at its peak. The move back above the 50-day EMA, intersecting at 155.75, undermines the recent bear theme and highlights a stronger short-term bull cycle. The next topside target is 157.72 as we approach this weekend’s election in Japan.
- The BLS have rescheduled the December JOLTS for Thursday, which will be the data highlight alongside both the BOE and ECB decisions.
MNI FX OPTIONS: Expiries for Feb05 NY cut 1000ET (Source DTCC)
- EUR/USD: $1.1725-35(E2.0bln), $1.1800(E2.9bln), $1.1825-35(E1.8bln), $1.1880(E706mln)
- USD/JPY: Y153.00($1.6bln), Y154.00($1.1bln), Y155.00($1.0bln), Y156.00($1.2bln), Y156.15-25($1.1bln)
- GBP/USD: $1.3490-00(Gbp798mln)
- EUR/GBP: Gbp0.8650(E624mln)
- AUD/USD: $0.6840-50(A$1.4bln)
- USD/CAD: C$1.3675($740mln)
- USD/CNY: Cny6.9711($600mln)
MNI US STOCKS: Late Equities Roundup: Oil & Gas Shares Help Bounce off Midday Lows
- Stocks are paring losses late Wednesday, the Nasdaq underperforming amid heavy selling in semiconductor maker and software services shares. Currently, the DJIA trades up 133.65 points (0.27%) at 49373.95, S&P E-Mini Futures down 36.5 points (-0.53%) at 6905, Nasdaq down 364.3 points (-1.6%) at 22889.91.
- As noted, semiconductor and software services shares led midweek declines: Advanced Micro Devices falling -16.62% after falling short of analyst earnings estimates less optimistic guidance on AI-related demand. Meanwhile, AppLovin fell -15.68% as share holders seek an investigation over reports that "AppLovin and certain of its officers and/or directors have engaged in securities fraud or other unlawful business practices" according to Access Newswire.
- Other late day laggers included: Sandisk Corp -15.26%, Palantir Technologies -13.29%, Micron Technology -12.50%, Western Digital -11.19%, Amphenol -10.51%, Lam Research -9.80% and Applied Materials Inc -9.33%.
- Media and entertainment shares weighed on the Communication Services sector: Take-Two Interactive Software -5.89%, Fox Corp -3.23%, Meta Platforms -2.76% and Alphabet -2.30%.
- On the positive side, oil & gas shares rallied with crude prices (WTI +1.92 at 65.13) after Axios reported that plans for US/Iran talks on Friday are collapsing w/subject of nuclear weapons, missile program a non-starter: Phillips 66 +4.77%, Devon Energy +4.65%, Marathon Petroleum +4.21%, Coterra Energy +4.04% and EOG Resources +3.14%.
- Meanwhile earnings expected after the close include: Allstate Corp, McKesson Corp, Alphabet Inc, O'Reilly Automotive, Coherent Corp, Snap Inc and QUALCOMM.
MNI EQUITY TECHS: (H6) Trend Needle Points North
- RES 4: 7141.7 1.236 proj of the Dec 18 - Jan 13 - 21 price swing
- RES 3: 7100.00 Round number resistance
- RES 2: 7080.92 0.764 proj of the Nov 21 - Dec 11 - 18 price swing
- RES 1: 7043.00 High Jan 28 and bull trigger
- PRICE: 6920.75 @ 1510 ET Feb 4
- SUP 1: 6864.50 Low Feb 2
- SUP 2: 6814.50 Low Jan 21 and the bear trigger
- SUP 3: 6771.50 Low Dec 18 and a key support
- SUP 4: 6684.50 Low Nov 24
The trend in S&P E-Minis remains bullish. The recovery from Monday’s low suggests - for now - that a recent bear threat merely resulted in a short lived correction. Attention is on key resistance and the bull trigger at 7043.00, the Jan 28 high. A break of this level would confirm a resumption of the primary uptrend and open 7080.92, a Fibonacci projection. Key support and a bear trigger lies at 6814.50, the Jan 21 low. A break would be bearish.
MNI COMMODITIES: Crude Jumps As US-Iran Talks In Doubt, Precious Metals Pull Back
- Crude markets have jumped after Axios reported that Iran-US talks are collapsing, raising the risk of conflict in the region.
- WTI Mar 26 is up by 3.1% at $65.2/bbl.
- The US told Iran on Wednesday that it will not agree to Tehran's demands to change the location and format of talks planned for Friday, two US officials told Axios.
- The report said that if the Iranians are willing to go back to the original format, the US is ready to meet this week or next week.
- A bull cycle in WTI futures remains intact, with key resistance and the bull trigger at $66.48, the Jan 30 high.
- A break of this level would open round number resistance at $68.00 next.
- Meanwhile, precious metals have unwound earlier gains as the US dollar rallied amid the risk-off tone.
- Spot gold briefly extended an impressive intraday pullback to print around $4,850 after reaching a $5,091 high overnight. Currently, spot gold is down by 0.2% at $4,936/oz.
- For gold, the next two resistance points to monitor are $5,139.9 and $5,314.0, Fibonacci retracement levels. A reversal lower would refocus attention on $4,403.0, the Feb 2 low.
- Similarly, silver briefly fell into negative territory, reaching a low of $83.3, down from an earlier session high around $92. Currently, silver is up by 1.5% at $86.4/oz.
- For silver, initial firm resistance is at $91.775, the 20-day EMA.
THURSDAY DATA CALENDAR
| Date | GMT/Local | Impact | Country | Event |
| 05/02/2026 | 0700/0800 | ** |  DE | Manufacturing Orders |
| 05/02/2026 | 0745/0845 | * |  FR | Industrial Production |
| 05/02/2026 | 0830/0930 | ** |  EU | S&P Global Final Eurozone Construction PMI |
| 05/02/2026 | 0900/1000 | * |  IT | Retail Sales |
| 05/02/2026 | 0930/0930 | ** |  GB | S&P Global/CIPS Construction PMI |
| 05/02/2026 | 1000/1100 | ** | EU | EZ Retail Sales |
| 05/02/2026 | 1200/1200 | *** | GB | Bank Of England Interest Rate |
| 05/02/2026 | 1200/1200 | *** | GB | Bank Of England Interest Rate |
| 05/02/2026 | 1230/1230 | GB | BOE Press Conference | |
| 05/02/2026 | - | EU | European Central Bank Meeting | |
| 05/02/2026 | 1315/1415 | *** | EU | ECB Deposit Rate |
| 05/02/2026 | 1315/1415 | *** | EU | ECB Main Refi Rate |
| 05/02/2026 | 1315/1415 | *** | EU | ECB Marginal Lending Rate |
| 05/02/2026 | 1330/0830 | *** |  US | Jobless Claims |
| 05/02/2026 | 1330/0830 | ** | US | WASDE Weekly Import/Export |
| 05/02/2026 | 1345/1445 | EU | ECB Press Conference | |
| 05/02/2026 | 1400/1400 | *** | GB | BOE Decision Making Panel |
| 05/02/2026 | 1500/1000 | US | Treasury Secretary Scott Bessent | |
| 05/02/2026 | 1530/1030 | ** | US | Natural Gas Stocks |
| 05/02/2026 | 1550/1050 | US | Atlanta Fed's Raphael Bostic | |
| 05/02/2026 | 1630/1130 | * | US | US Bill 08 Week Treasury Auction Result |
| 05/02/2026 | 1630/1130 | ** | US | US Bill 04 Week Treasury Auction Result |
| 05/02/2026 | 1725/1225 |  CA | BOC Governor Macklem speech in Toronto, release time TBC. | |
| 05/02/2026 | 1900/1400 | *** |  MX | Mexico Interest Rate |
| 06/02/2026 | 2330/0830 | ** |  JP | Household spending |


