AUSSIE 3-YEAR TECHS: (Z6) Recent Gains Still Appear Corrective
* RES 3: 95.925 - High Jan 9 (cont) and a key resistance * RES 2: 95.670 - High Jun 25 / 29 and the ...
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
JPY: Little Changed For Mon, USD/JPY Bull Cycle Intact, Ueda Speaks Today
Yen ended Monday trade little changed versus the USD, slightly outperforming most of the majors. The pair tracks close to 157.90 in early Tuesday trade, after a 157.44-158.30 range for Monday trade. Broader USD sentiment was supported, as EUR/USD weakness remained in focus (amid political and fiscal headwinds), but oil futures finishing lower and US cash equities finishing in the green helped temper dollar upside.
- For USD/JPY technicals a bull cycle in USDJPY remains in play and recent short-term weakness appears corrective. The pair continues to trade above the 20-day EMA, at 157.28. A clear bearish break of the average would undermine the recent bull leg and reinforce a possible reversal signal on Sep 25 - a bearish engulfing candle. For now sights are on key resistance is 159.04, the Sep 24 high.
- The local data calendar is empty today, but we have BoJ Governor Ueda speaking. Focus will be on BoJ tightening risks into year end. Currently the market gives little chance of an Oct rise, while Dec OIS pricing has an implied rate of 1.44%, versus the current effective rate of 1.227% (a full 25bps hike is priced for the Jan 2027 meeting).
- Via our Tokyo based policy team from late last week: The avoidance of any acknowledgement that inflation is above target by Bank of Japan Governor Kazuo Ueda is aimed both at averting potential criticism from Prime Minister Sanae Takaichi and at keeping good relations with her government ahead of key appointments to the BOJ board including that of his own successor, MNI understands. Ueda’s stance has caused some confusion in markets, given clear signs that underlying inflation is already above 2%, despite the BOJ’s insistence that it is still only approaching 2% as it withdraws some monetary accommodation.
- The local data calendar is empty today, with Aug labor cash earnings out tomorrow.
- Also note the following in the option expiry space for NY cut later: Y154.00($1.8bln), Y156.00($3.1bln), Y160.00($500mln)
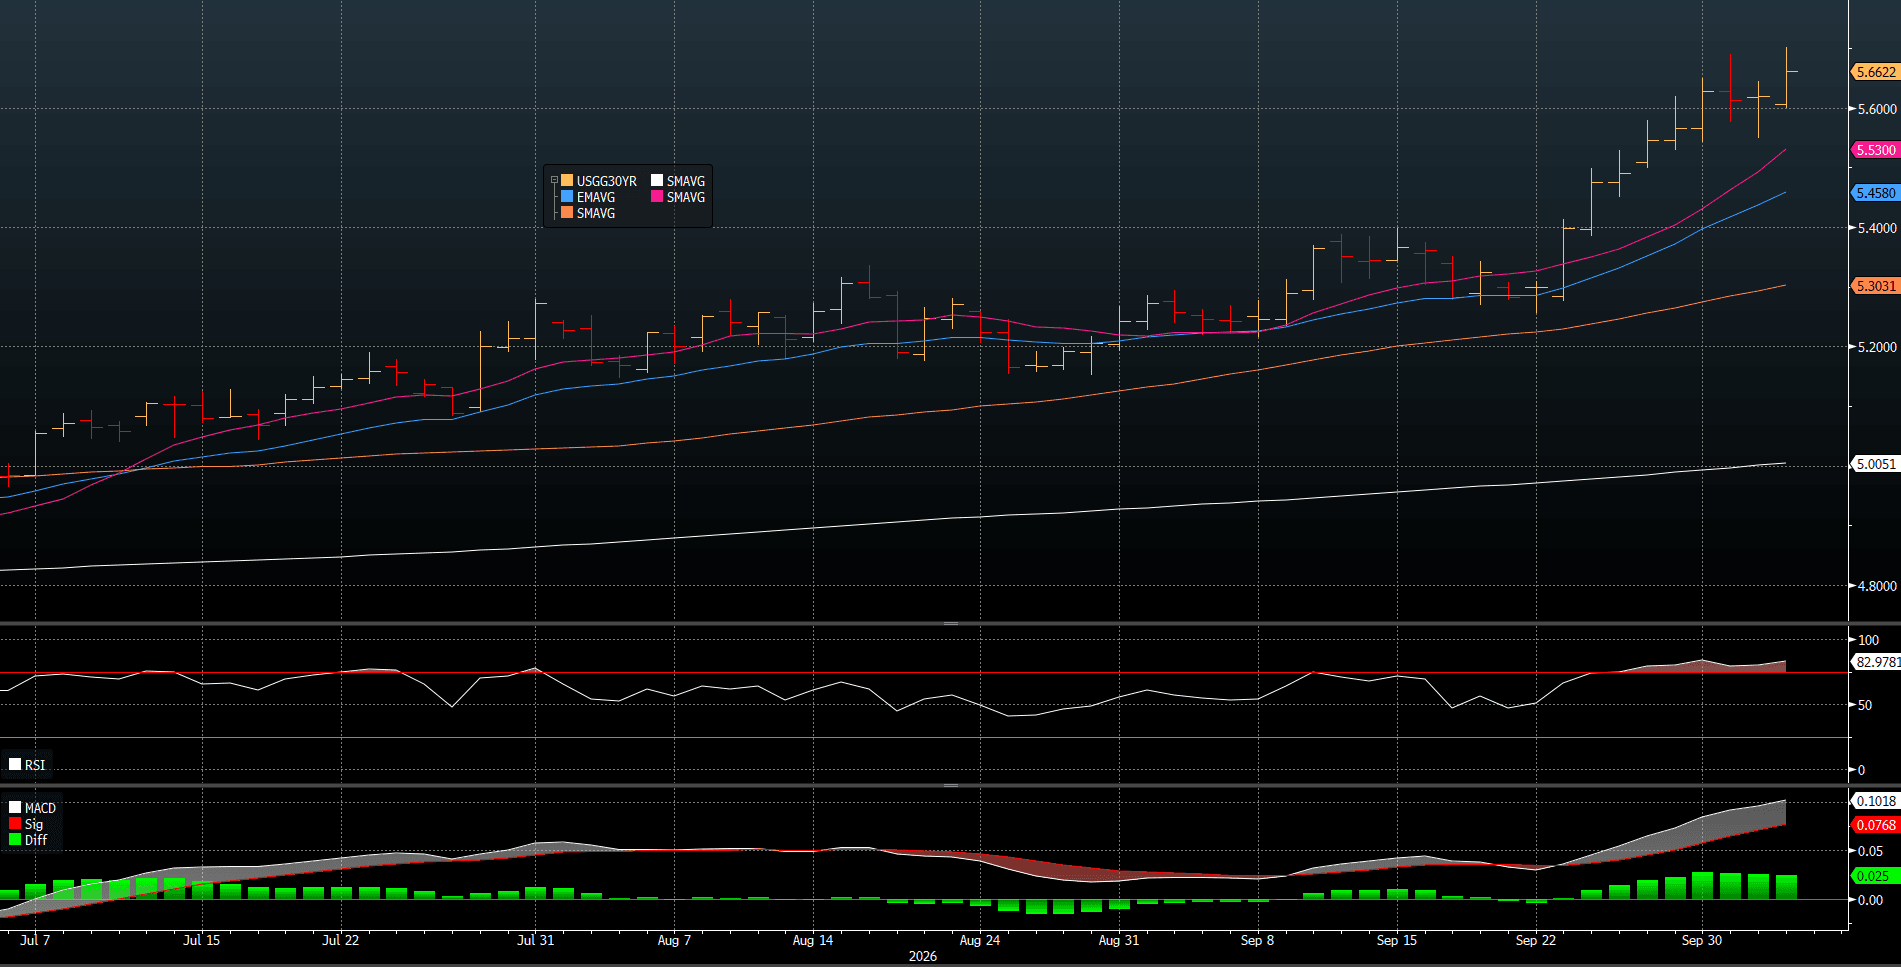
US TSYS: Twist-Steepener Pushes 30YY To Fresh Cycle High
TYZ6 is dealing at 104-09+, +0-02+ from closing levels in today's Asia-Pac session.
- Cash bonds finished Monday’s session showing a twist-steepener, with benchmark yields 1bp lower to 4bps higher, after oil-driven volatility.
- The 30-year yield made a fresh cycle high of 5.7017% before finishing at 5.6622%.
- Conflicting reports over whether the Saudi East-West oil pipeline had halted flows, and whether the Yemeni government had taken control of the Bab-el-Mandeb Strait from the Houthis, saw oil prices fluctuate and EGBs / Gilts with them on heavy volumes.
- Limited reaction to US data: September's ISM Services PMI saw a slight dip as expected, to 54.9 (55.0 consensus) from August's 55.4, with softer activity details, stronger employment, and markedly higher price pressures amid apparent supply chain constraints and soaring energy prices.
- S&P Global US services PMI: 58.8 (cons and flash 58.7) in Sep final after 56.5 in Aug; S&P Global US composite PMI: 58.4 (cons 58.3, flash 58.4) in Sep final after 56.0 in Aug.
- Tuesday’s focus turns to French Industrial & Manufacturing Production, Eurozone retail sales, US & Canadian trade balance data as well as speeches from ECB's Zigman, Cipollone (at an MNI event), Fed's Williams, Schmid & Bowman.
Bloomberg Finance LP
ENERGY: "*SAUDI-LED COALITION SAYS DESTROYED SANAA MISSILE LAUNCHER: SPA
"*SAUDI-LED COALITION SAYS DESTROYED SANAA MISSILE LAUNCHER: SPA
*COALITION SAYS DESTROYED MISSILE STORAGE FACILITY IN SAADA: SPA" - BBG


