MNI US OPEN - Iran Escalates Retaliatory Strikes
EXECUTIVE SUMMARY
- GROUND OFFENSIVE IN LEBANON OPENS UP NEW FRONT IN REGIONAL CONFLICT
- WARSH’S PUSH TO SHRINK FED’S BALANCE SHEET WOULD EVOLVE SLOWLY: FT
- LENGTHY IRAN WAR COULD CAUSE INFLATION ‘SPIKE’, WARNS ECB’S LANE: FT
- EUROZONE HICP SURPRISES TO THE UPSIDE
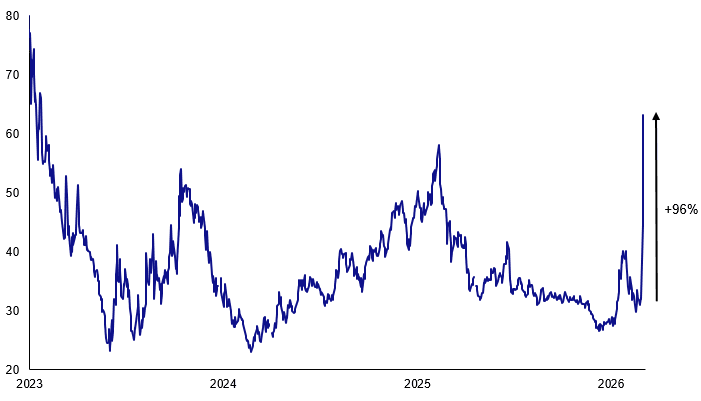
Figure 1: European natural gas future contracts extend two-day surge to nearly 100%
Source: MNI, Bloomberg Finance L.P.
NEWS
ISRAEL (MNI): Ground Offensive in Lebanon Opens Up New Front in Regional Conflict
Israeli Defence Force (IDF) troops are moving into southern Lebanon in the latest stage of the operation intended to knock out the capabilities of Hezbollah, Iran's proxy in the country, once and for all. In the wake of the Israeli/US attacks on Iran over the weekend, Hezbollah responded with rocket fire into north and central Israel in retaliation for the killing of Supreme Leader Ayatollah Ali Khamenei. This in turn sparked the heaviest Israeli bombardment of Lebanon since the November 2024 ceasefire agreement, with Israel targeting senior Hezbollah figures and weapons caches in Beirut and the south of the country. The IDF claims that as part of the strikes, a senior commander in the IRGC's Quds Force, Reza Khazaei, was killed.
MIDEAST (NYT): Iran Escalates Retaliatory Strikes Around the Region
The State Department closed its embassies in Saudi Arabia and Kuwait on Tuesday after drone attacks and ordered nonessential staff in several Middle East countries to evacuate, as Iran expanded its retaliatory strikes on American targets in the widening regional conflict. The U.S. Embassy in Riyadh, Saudi Arabia’s capital, sustained minor damage after an attack by what appeared to be two drones, the Saudi Defense Ministry said on Tuesday. A day earlier, a drone attack caused a fire at the American Embassy compound in Kuwait, according to two U.S. officials who spoke anonymously because they were not authorized to discuss the matter publicly.
US (BBG): US Has No Immediate Plan to Tap Oil Reserve on Iran Concerns
The Trump administration has no immediate plans to release oil from the nation’s emergency reserve in response to surging crude and gasoline prices in the wake of the Iran conflict, according to a person familiar with the situation. A decision to tap the Energy Department’s Strategic Petroleum Reserve could help stanch prices spikes, at least temporarily. The reserve currently holds about 415 million barrels, or a little more than half of its roughly 700 million-barrel capacity.
FED (FT): Kevin Warsh’s Push to Shrink Federal Reserve’s Balance Sheet Would Evolve Slowly
Kevin Warsh’s attempt to shrink the Federal Reserve’s balance sheet would proceed only slowly as Donald Trump’s nominee to chair the central bank faces resistance over his plan to scale back one of its most powerful tools. Warsh has repeatedly said the Fed’s almost $7tn balance sheet is a reflection of how the central bank has strayed into Congress’s domain and noted its huge bond purchases under successive quantitative easing programmes have distorted financial markets. But Warsh would only seek to make changes to the Fed’s balance sheet after extensive talks on its potential effects with banks and the broader public, according to people familiar with his thinking.
US/CHINA (BBG): US, China Trade Chiefs to Meet Mid-March Before Trump-Xi Summit
US and Chinese trade negotiators are slated to meet in mid-March, according to people familiar with the matter, signaling a planned summit between Donald Trump and Xi Jinping is pushing ahead despite American strikes against Iran. US Treasury Secretary Scott Bessent, US Trade Representative Jamieson Greer and China’s Vice Premier He Lifeng are expected to convene in Paris at the end of next week to discuss business deals that could stem from the leaders’ meeting, said the people who requested anonymity to discuss plans that aren’t yet public. Both the timing and location of the meeting could still shift, the people added.
ECB (FT): Lengthy Iran War Could Cause Inflation ‘Spike’, Warns ECB’s Top Economist
Prolonged war in the Middle East and a persistent fall in oil and gas supplies from the region could cause a “substantial spike” in inflation and a “sharp drop in output” in the Eurozone, the European Central Bank’s chief economist has warned. In an interview with the FT, Philip Lane said that “directionally, a jump in energy prices puts upward pressure on inflation, especially in the near term”, and that such a development would be “negative” for growth. The magnitude of the shock from the Middle East would depend “on the breadth and duration of the conflict”, Lane said. He added that “the impact would be amplified if it also gave rise to a repricing of risk in financial markets”. The ECB “will be closely monitoring developments”, Lane said.
ECB (BBG): Villeroy Says ECB Won’t Set Rates Based Solely on Energy Prices
The European Central Bank won’t decide on interest rates only on the basis of energy prices, Governing Council member Francois Villeroy de Galhau said. Speaking to reporters on Tuesday, the Bank of France chief added that it would be a mistake to anticipate a move in borrowing costs in a hurry. Oil and natural gas prices have jumped as the US and Israel step up their war against Iran, and Tehran vows a full closure of the Strait of Hormuz. “Our ECB Governing Council will have updated economic forecasts at its next meeting in two weeks’ time,” Villeroy said in Paris. “It would be a mistake to rush into predicting a possible change in interest rates today.”
UK (Hidden PDF): Will Events in the Middle East Impact the Spring Statement?
Our base case is that there will be no direct impact from events in the Middle East on today's Spring Statement. However, we think there is an outside chance that Chancellor Reeves could hint that the fuel duty increases due later this year could potentially be postponed if petrol prices see large increases. Recall that the Autumn Budget saw an announcement that the "temporary" 5p/litre fuel duty cut would be reversed in stages through a 1p/litre increase in September, 2p/litre in December and 2p/litre in March 2027, before rising in line with inflation thereafter. Any mention of potentially postponing fuel duty increases would likely have knock on impacts for market pricing of cuts.
UK (The Times): Green Party Seizes Second Place in Polls as Labour Hits Record Low
The Green Party has leapfrogged Labour and the Conservatives to second place in the polls behind Reform UK. A YouGov survey for The Times and Sky News found that support for the Greens was 21 per cent, up four points in the week since their historic by-election victory in Gorton & Denton. Labour had 16 per cent support, down two points on the previous week and its lowest polling score on record. The Conservatives are also down two points at 16 per cent, which is only the second time the party has recorded such a low rating.
CHINA (MNI): China Will Ensure Its Energy Security Amid Iran War
MNI (Beijing) China will take necessary measures to ensure its energy security, Foreign Ministry spokesperson Mao Ning told reporters at a press conference Tuesday, responding a question regarding analyst's concern over Beijing's supply of oil and gas from the Gulf region. Energy security is very important to the world economy, and all parties should ensure a stable and smooth energy supply, Mao added.
CHINA (MNI): China Calls for Safety of Hormuz Shipping - MOFA
MNI (Beijing) China has urged the upholding of the safety shipping in the Strait of Hormuz, the Ministry of Foreign Affairs told reporters on Tuesday. MOFA spokesperson Mao Ning said all parties should immediately stop military action, prevent the escalation of tension, ensure the safety of the shipping lane in the Strait of Hormuz, and prevent a wider impact on the global economy. Mao noted energy security matters greatly to the world economy and all parties have the responsibility to keep energy supply stable and unimpeded.
CHINA (MNI INTERVIEW): Chinese Oil Reserves Enough for Short Iran War
A Chinese energy expert shares his view on the impact of the war in Iran on China. On MNI Policy MainWire now, for more details please contact sales@marketnews.com
JAPAN (BBG): Japan’s Katayama Warns on FX as Middle East Weighs on Yen
Japan is monitoring financial markets with the utmost vigilance and will take any necessary action in response to sharp movements, Finance Minister Satsuki Katayama said, as volatility intensifies following the US and Israeli attack on Iran. “We recognize that significant fluctuations have occurred in financial markets in light of the recent developments in the Middle East,” Katayama told reporters Tuesday. “The government is watching market movements with an extremely high sense of urgency, and will take all necessary measures, while working closely and nimbly with overseas authorities,” she said.
JAPAN (MNI): BOJ's Ueda Reveals Blockchain Settlement Project
The Bank of Japan has launched a sandbox project to explore the use of central bank money for a broad range of settlements on blockchain-based systems, said Governor Kazuo Ueda. “In this experimental project, the Bank will conduct technical experimentation on settlement using central bank money in the form of current account deposits on a system that uses blockchains,” Ueda said at FIN/SUM 2026.
DATA
EUROZONE DATA (MNI): HICP Surprises to the Upside
- EUROZONE FEB FLASH HICP 1.90% Y/Y (MNI MEDIAN 1.7%, JAN 1.66%)
- EZ FEB FLASH CORE HICP 2.4% Y/Y (MNI MED 2.2%, JAN 2.2%)
- EZ FEB FLASH SERVICES HICP 3.4% Y/Y (MNI MED 3.2%, JAN 3.2%)
UK DATA (MNI): BRC Shop Prices Partially Reverse Jan's Strong Rise; Prices Flat M/M
- UK FEB BRC SHOP PRICES +0.0% M/M, +1.1% Y/Y
BRC shop price inflation slowed to 1.1% Y/Y in February (vs 1.5% Jan), partially reversing January's strong rise, but still above December's 0.7% Y/Y. There were notable decreases in inflation across food and non-food categories. We would interpret the data with caution given recent moves have been more extreme than those of the official ONS CPI data. On a monthly basis, the shop price index was back to flat (vs 0.4% M/M Jan, 0.0% Dec). Both food and non-food prices were flat on the month. Food inflation fell to 3.5% Y/Y (vs 3.9% Jan, 3.3% Dec), driven mostly by ambient food as opposed to fresh food (the same as January's increase). Month-on-month, food prices were flat, after a large 1.1% M/M in Jan.
JAPAN DATA (MNI): Unemployment Rate & Job-To-Applicant Ratio Show Weaker Trends
Japan's Jan jobless rate edged up to 2.7%, versus a 2.6% forecast (which was also the prior outcome). The job-to-applicant ratio fell to 1.18, versus 1.20 forecast (which was also the prior outcome). This fits with other data released as part of today's release, with job offers down 5.4%y/y, while new job offers, were down -4.6% y/y. This is up from Nov lows in y/y terms for both series. In m/m terms both series were down a touch.
JAPAN DATA (MNI): Q4 Capex Rebounds, Led by Non-manufacturing, Profits Also Rise
Japan Q4 capex was stronger than forecast. We rose 6.5%y/y for the headline (3.0% was projected, while 2.9% was the prior outcome). Ex software we rose 7.3%y/y (3.9% was forecast, 2.9% was the prior outcome). Company profits were also better than forecast, rising 4.7%y/y (3.0% was forecast), but this was down from Q3's heady 19.7% rise. The capex rise fits with the better end to core machine orders for late 2025.
AUSTRALIA DATA (MNI): Net Export Drag to Q4 GDP Less Than Forecast
Australia's Q4 net exports contribution to GDP cut -0.1pps off growth, the same as the Q3 drag. The market expected a -0.3ppts drag, so a slightly better than expected outcome. The ABS also notes that total public demand will contribute 0.3ppt to Q4 growth. This comes ahead of tomorrow's Q4 GDP print. The market consensus is a 0.7%q/q rise (prior 0.4%) and y/y pace of 2.2% (prior 2.1%). The q/q forecast range is 0.5-1.0% at this stage. The focus will be on the domestic demand impulse, particularly as the economy bumps up against capacity constraints.
AUSTRALIA JAN BUILDING APPROVALS -7.2% M/M, -15.7% Y/Y (MNI)
FOREX: USD Index Extends Surge to 1.7% This Week
- Broad greenback strength extends as the markets assess the impact of the Middle East conflict that has erupted over the weekend. Safe haven demand and US energy independence concerns continue to underpin a solid surge for the dollar, leading the DXY to a 1.7% gain from last Friday’s close, with session highs 99.22.
- As a function of its high weighting in the index, this mechanically implies EURUSD losses as the Eurozone's vulnerability to the energy turmoil outweighs upside risks to inflation in the bloc. The pair is extending lows at typing, pushing towards 1.1573, the January 19 low and key support.
- Significant declines for the major equity benchmarks are weighing on the risk sensitive AUD and NZD, with the latter now 1% lower on the session against the dollar. NZDUSD has accelerated below its 50-day EMA and trades sub-0.5900. Highs for AUDUSD overnight at 0.7123 continue to emphasise the building significance of a resistance cluster between 0.7125/58 for the pair.
- Meanwhile, higher core yields have been weighing on the likes of the Yen and Swiss Franc. USDJPY has broken through the post-election highs at 157.76, although intervention rhetoric from the MoF is likely to temper the topside momentum somewhat. Conversely, the SNBs communication on a higher readiness to intervene is prompting sharp CHF underperformance again, with USDCHF extending its tw0-day bounce to over 2.5%. Swiss CPI is scheduled for tomorrow.
- Main focus continues to lie on further developments in the middle east. This includes second order effects on top of questions around Iran's capability to keep up counterattacks to the wider region at the current pace and the duration of the Strait of Hormuz closure.
- Redbook retail sales is the sole US datapoint for today, while ECB's Kocher and Sleipen, Fed's Williams and Kashkari are scheduled to appear.
BONDS: Bear Flattening Dominates as Energy Prices Surge
Bear flattening has dominated again today, with a further increase in European natural gas and benchmark crude oil prices punctuating inflationary risks surrounding the recent escalation of the situation in the Middle East.
- The front end of the EUR curve is now pricing 14bp of ECB tightening through year-end (compared to ~10bp of cuts being priced on Friday), despite chief economist Lane and several Governing Council members warning against acting too quickly in light of developments surrounding Iran (albeit cognisant of hawkish inflation risks alongside downside risks to growth).
- Firmer-than-expected Eurozone HICP data also factors into the move
- Bund futures -93 at 128.70, threatening a break below the 50-day EMA (128.69).
- 2-Year German yields are now 20bp higher on the week, while Bund yields are threatening a break back above 2.80% after trading as low as 2.64% last week.
- The German 2s10s curve is below 60bp for the first time in a year.
- EGB spreads vs. Bunds under more meaningful widening pressure given the risk-negative environment, with GGBs & BTPs leading that move, just under 5bp wider on the day.
- Gilt yields also surge, with 2s 17.5bp higher on the day and 10s back above 4.50%. 2s10s bases around 70bp for now. Futures have moved through key short-term-support and the next support cluster, increasing the risk to the bullish technical theme, last -159 ticks at 91.42.
- BoE-dated OIS prices just 21bp of easing vs. 52-53bp on Friday.
- While today’s Spring Statement is touted to be a bit of a non-event when it comes to policy revelations, the recent headwinds for PM Starmer (by-election defeat & the Mandelson scandal have increased pressure on the PM) and presence of the updated gilt remit provide ongoing intrigue around UK fiscal matters.
- Our full preview of the event can be found here: Hidden PDF
EQUITIES: E-Mini S&P Continues to Trade Close to Recent Lows
A strong short-term reversal in EuroStoxx 50 futures has resulted in a breach of both the 20- and 50-day EMAs. This highlights potential for a deeper near-term pullback and opens 5854.50, a Fibonacci retracement point. Note that a clear break of the 50-day EMA would also undermine the broader uptrend and signal a potential medium-term reversal. Initial resistance to watch is 6083.00, the Mar 2 high. S&P E-Minis are trading closer to their recent lows. For now, the contract remains inside a range. A continuation lower would open key support and the base of the current range at 6751.50, the Feb 6 low, where a break would highlight a bear threat. On the upside, a resumption of gains and a breach of 6983.75, the Feb 25 high, would refocus attention on key resistance and the range top at 7043.00, the Jan 28 high.
- Japan's NIKKEI closed lower by 1778.19 pts or -3.06% at 56279.05 and the TOPIX ended 126.25 pts lower or -3.24% at 3772.17.
- Elsewhere, in China the SHANGHAI closed lower by 59.915 pts or -1.43% at 4122.676 and the HANG SENG ended 291.77 pts lower or -1.12% at 25768.08.
- Across Europe, Germany's DAX trades lower by 795.88 pts or -3.23% at 23839.38, FTSE 100 lower by 265.81 pts or -2.47% at 10513.68, CAC 40 down 216.73 pts or -2.58% at 8178.75 and Euro Stoxx 50 down 191.38 pts or -3.2% at 5797.67.
- Dow Jones mini down 838 pts or -1.71% at 48103, S&P 500 mini down 125 pts or -1.81% at 6762.75, NASDAQ mini down 576.5 pts or -2.3% at 24447.75.
Time: 10:15 GMT (05:15 ET)
COMMODITIES: Volatile Bull Cycle in WTI Intact, Next Resistance at $78.05
A volatile bull cycle in WTI futures remains intact. However, recent gains highlight the fact that the contract is in an extreme overbought position. A deeper retracement would be considered corrective and this would allow the overbought condition to unwind. The first key support to monitor is $65.00, the 20-day EMA. For bulls, a resumption of gains would pave the way for a climb towards $78.05 next, a Fibonacci projection. Gold started this week on a bullish note, confirming an extension of the recovery since Feb 2. The metal has cleared all key retracement points of the sharp sell-off between Jan 29 - Feb 2. The move higher strengthens the short-term bullish theme and signals scope for an extension towards key resistance and the bull trigger at $5595.5, the Jan 29 high. Initial firm support to watch lies at $5075.8, the 20-day EMA.
- WTI Crude up $4.29 or +6.02% at $75.39
- Natural Gas up $0.19 or +6.49% at $3.152
- Gold spot down $54.21 or -1.02% at $5270.3
- Copper down $15.05 or -2.53% at $579.95
- Silver down $5.83 or -6.52% at $83.7141
- Platinum down $169.57 or -7.35% at $2139.6
Time: 10:15 GMT (05:15 ET)
| Date | GMT/Local | Impact | Country | Event |
| 03/03/2026 | - |  GB | OBR Spring Forecast | |
| 03/03/2026 | 1355/0855 | ** |  US | Redbook Retail Sales Index |
| 03/03/2026 | 1455/0955 | US | New York Fed's John Williams | |
| 03/03/2026 | 1510/1010 | US | Kansas City Fed's Jeff Schmid | |
| 03/03/2026 | 1655/1155 | US | Minneapolis Fed's Neel Kashkari | |
| 04/03/2026 | 2200/0900 | * |  AU | S&P Global Final Australia Services PMI |
| 04/03/2026 | 2200/0900 | ** | AU | S&P Global Final Australia Composite PMI |
| 04/03/2026 | 0030/1130 | *** | AU | Quarterly GDP |
| 04/03/2026 | 0030/0930 | ** |  JP | S&P Global Final Japan Services PMI |
| 04/03/2026 | 0030/0930 | ** | JP | S&P Global Final Japan Composite PMI |
| 04/03/2026 | 0130/0930 | *** |  CN | CFLP Manufacturing PMI |
| 04/03/2026 | 0130/0930 | ** | CN | CFLP Non-Manufacturing PMI |
| 04/03/2026 | 0145/0945 | ** | CN | S&P Global Final China Services PMI |
| 04/03/2026 | 0145/0945 | ** | CN | S&P Global Final China Composite PMI |
| 04/03/2026 | 0145/0945 | ** | CN | S&P Global Final China Manufacturing PMI |
| 04/03/2026 | 0730/0830 | *** |  CH | CPI |
| 04/03/2026 | 0815/0915 | ** |  ES | S&P Global Services & Composite PMI (f) |
| 04/03/2026 | 0845/0945 | ** |  IT | S&P Global Composite & Services PMI (f) |
| 04/03/2026 | 0850/0950 | ** |  FR | S&P Global Composite & Services PMI (f) |
| 04/03/2026 | 0855/0955 | ** |  DE | S&P Global Composite & Services PMI (f) |
| 04/03/2026 | 0900/1000 | ** |  EU | S&P Global Composite & Services PMI (f) |
| 04/03/2026 | 0900/1000 | IT | Unemployment | |
| 04/03/2026 | 0930/0930 | ** | GB | S&P Global Composite & Services PMI (Final) |
| 04/03/2026 | 1000/1100 | ** | EU | EZ PPI |
| 04/03/2026 | 1000/1100 | ** | EU | EZ Unemployment |
| 04/03/2026 | 1000/1100 | *** | IT | GDP (f) |
| 04/03/2026 | 1045/1145 | EU | ECB Cipollone Panel at European Investment Bank Group Forum | |
| 04/03/2026 | 1200/0700 | ** | US | MBA Weekly Applications Index |
| 04/03/2026 | - | CN | Chinese People's Political Consultative Conference | |
| 04/03/2026 | 1330/1430 | EU | ECB de Guindos Remarks at American Academy, Berlin | |
| 04/03/2026 | 1445/0945 | *** | US | S&P Global Composite & Services Index (final) |
| 04/03/2026 | 1500/1000 | *** | US | ISM Non-Manufacturing Index |
| 04/03/2026 | 1520/1020 |  CA | BOC Governor Macklem speech | |
| 04/03/2026 | 1530/1030 | ** | US | US DOE Petroleum Supply |
| 04/03/2026 | 1530/1030 | ** | US | DOE Weekly Crude Oil Stocks |


