GBPUSD TECHS: Monitoring Support
* RES 4: 1.3568 High Sep 9 * RES 3: 1.3549 76.4% retracement of the Aug 21 - Oct 14 bear leg * RES 2...
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
RBA: Bullock Sketches Out what's Needed From CPI Ahead
- “RBA GOV BULLOCK: NEED TO SEE QUARTERLY CORE INFLATION NUMBERS SITTING AROUND 0.6%” - RTRS
- “RBA GOV BULLOCK: Q3 CPI NUMBERS WILL ONLY CONFIRM WHAT WE ALREADY KNOWN”
BRENT TECHS: (X6) Bullish Trend Condition
- RES 4: $116.68 - 2.000 proj of the Jul 2 - 23 - Aug 5 price swing
- RES 3: $113.13 - 76.4% retracement of the Apr - Jul bear leg (cont)
- RES 2: $111.97 - 1.764 proj of the Jul 2 - 23 - Aug 5 price swing
- RES 1: $109.97 - High Sep 11 and the bull trigger
- PRICE: $107.27 @ 07:12 BST Sep 28
- SUP 1: $101.08 - 20-day EMA
- SUP 2: $94.64 - 50-day EMA
- SUP 3: $84.56 - Low Aug 26
- SUP 4: $76.78 - Low Aug 5 and a key support
Bullish trend conditions in Brent futures remain intact and the latest recovery reinforces this theme. Initial support to watch lies at the 20-day EMA, at $101.08. A clear break of the 20-day average would suggest scope for a deeper retracement. Support at the 50-day EMA - the next important medium-term support level to watch - lies at $94.64. Key resistance and the bull trigger has been defined at $109.97, the Sep 11 high.
SWEDEN: Economic Tendency Indicator Continues To Climb
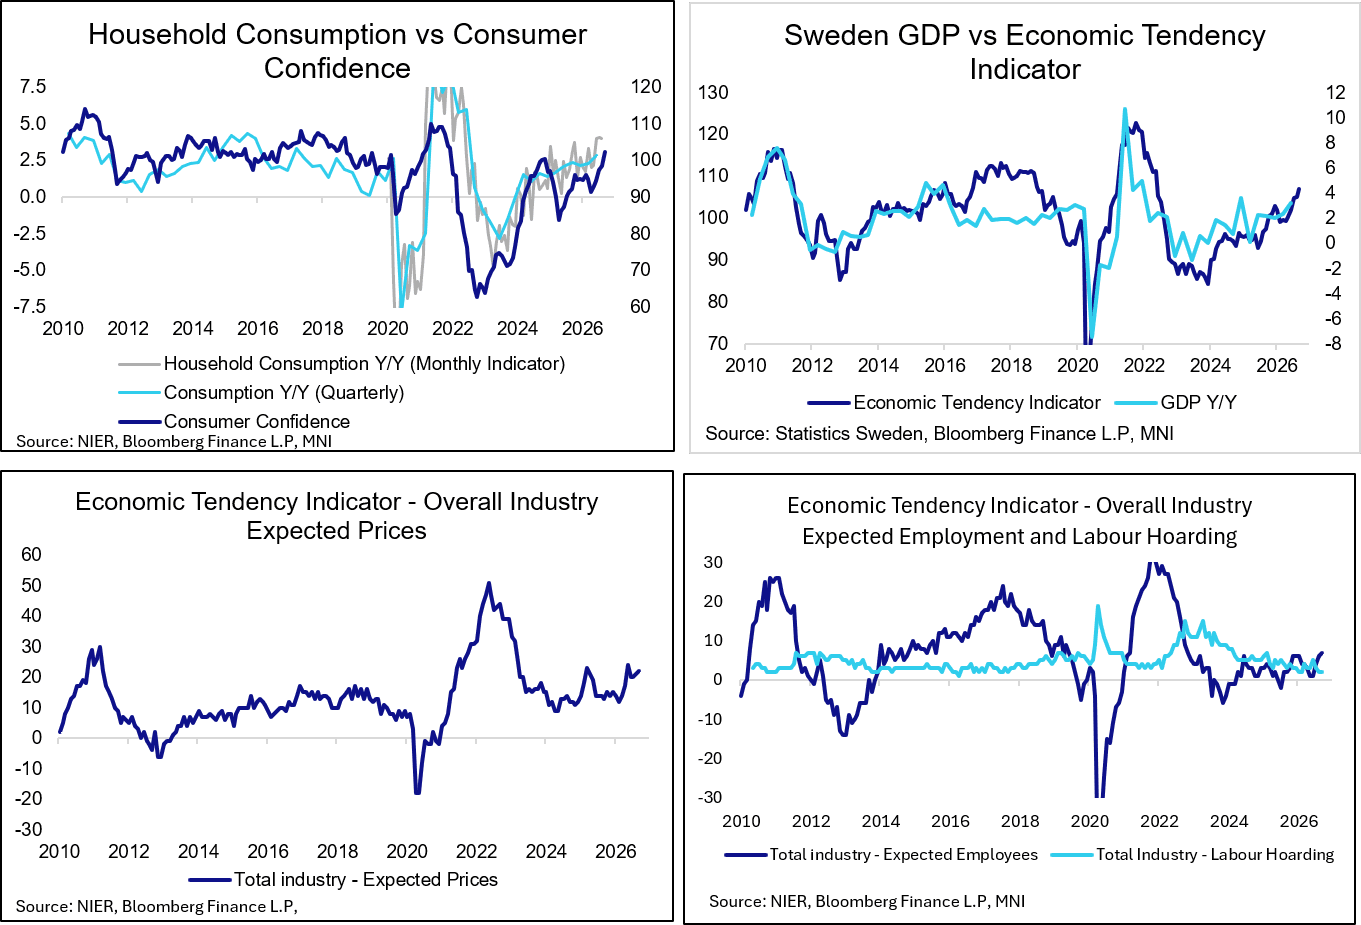
There was another rise in the Economic Tendency Indicator in September, a further signal of a broadening economic recovery. The index rose to 107.1 (vs 105.1 prior), the highest since H1 2022. Consumer confidence moved above the long-term average of 100 for the first time since 2024 (and before that, 2021), while services and construction sentiment rose relative to August.
- The Riksbank’s hawkish guidance in September was a combination of growing inflation risks and better than expected economic outturns. The September ETI survey doesn’t present any tension with that message.
- The expected prices diffusion index inched up to 22 (vs 21 in Aug, 20 in Jul). It peaked at 24 in May. Services expected prices were 19 (vs 18 in Aug, 20 in Jul), while manufacturing prices pulled back to 27 (vs 29 in Aug, 25 in Jul). Retail expected prices were unchanged at 22 for a fourth month.
- The expected employment diffusion index rose again to 7 (vs 6 in Aug, 4 in Jul). It’s now at the highest since November 2022. This was driven by the manufacturing industry (+5 vs -1 in August).
- In the September MPR, the Riksbank noted that “some indicators now suggest that the labour market situation is gradually improving”, though there was still considered to be some spare capacity.