MNI US Inflation Insight: Firm Core Prices Seal Deal For Hike

Sep-11 20:54By: Tim Cooper and 1 more...
InflationUS
Hidden PDF
Executive Summary
While August’s inflation data didn’t show a major acceleration in underlying pressures, nor will they have offered comfort to Fed participants who are looking for more decisive indications of progress toward the 2% target.
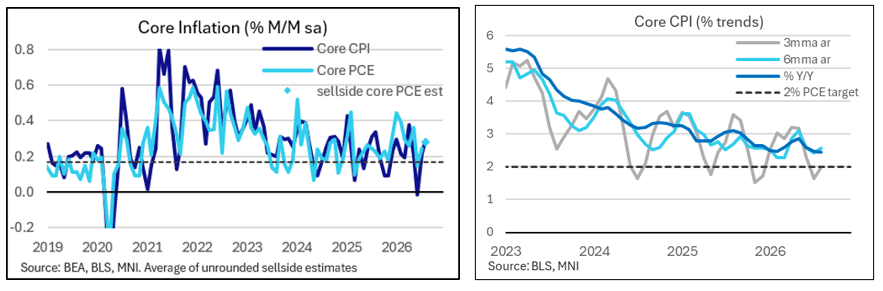
- Core CPI rose 0.29% M/M, above the 0.22% consensus and July’s 0.22%. The upside surprise was driven by supercore inflation, with core goods coming in on the soft side of expectations.
- Headline CPI was broadly in line with consensus. The monthly acceleration reflected a rebound in energy prices, while food inflation remained relatively tame. Grocery prices were flat, but food away from home remained on the warm side and indicative of continued service-sector price pressures.
- The main upside drivers in core were arguably outliers: a record increase in wireless telephone services, a rebound in lodging, and less-negative car insurance. Housing was softer than expected, while medical services were relatively benign.
- Some aspects were somewhat less concerning than the core reading suggested: median and trimmed-mean measures were softer, while dispersion measures showed some moderately encouraging developments.
- However, inflation remained broad and elevated by pre-pandemic standards, and supercore trends picked up from softer prior readings.
- The PPI report showed more moderate pipeline pressures compared to July, but run rates remained elevated amid continued energy passthrough. PCE-relevant components—including airfares and parts of healthcare -- looked on the firm side.
- As a result, core PCE tracking moved into the 0.25–0.30% M/M area (vs 0.21-0.22% coming into the inflation round), with consensus clustered in the high 0.20s. That would translate roughly into a 2.7-2.8% core PCE run rate on a 3-month annualized basis, with Y/Y continuing to run well above 3%.
- Gov Warsh and most of the FOMC are unlikely to be convinced that this represents anything close to a resumption of disinflationary progress. Accordingly, the data were enough to see market-implied pricing for a September Fed hike firm to well over 80%, from under 60% prior to PPI.