JGBS: Long End Yields Pare Gains, Curves Flatter, 40yr Supply Next Tuesday
Sep-25 04:43
JGB futures remain skewed lower, we were last 124.23, -.18 versus settlement levels (session lows re...
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
US TSYS: Cash Bonds Slightly Cheaper After Yesterday's Peace Deal Induced Gains
Aug-26 04:42
TYU6 is dealing at 108-27+, flat from closing levels in today's Asia-Pac session.
- Cash bonds are ~1bp cheaper in today's Asia-Pac session after yesterday's US/Iran peace deal-induced gains.
- Oil prices are weaker again today after falling around 5% yesterday following statements from both Oman and Iran that a "temporary joint maritime corridor" had been agreed and a permanent route through Hormuz would be negotiated over the coming 60 days. Iran reiterated that it doesn't necessarily mean that it will be reopened though.
- While markets await Fed Chairman Warsh's comments at Friday's JH economic symposium, lower oil has slightly eased concerns over future energy cost pass-through to core inflation.
- (Bloomberg) “The Treasury Department's plan to at least double Treasury buybacks has provided some support to the market, but is seen as unlikely to have a lasting impact due to elevated inflation and worries about surging government debt. Besssent’s former mentor Stanley Druckenmiller said the intervention was a mistake.”
- (Financial Times) “US Treasury secretary Scott Bessent’s bond market intervention is pulling in the opposite direction to the Federal Reserve’s battle against inflation, big investors warned ahead of chair Kevin Warsh’s Jackson Hole speech.” – via BBG
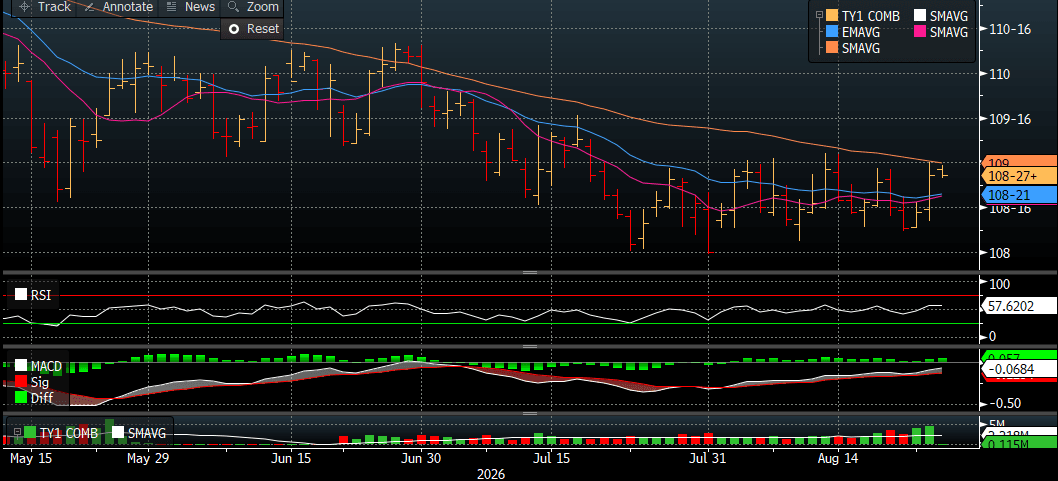
Bloomberg Finance LP
OIL: Oil Continues Decline On Middle East Optimism, US PCE Prices Later
Aug-26 04:40
Oil prices have continued declining during Wednesday’s APAC session after falling around 5% on Tuesday in response to statements from both Oman and Iran that a “temporary joint maritime corridor” had been agreed and a permanent route through Hormuz would be negotiated over the coming 60 days. Iran reiterated that it doesn’t necessarily mean that it will be reopened though and the situation in the region and for oil shipments remains fragile.
- WTI is down 2.5% to $80.30/bbl after a low of $80.08 with $80 providing support. Brent is 2.6% lower at $86.30/bbl after falling to $86.05.
- Oman-Iran technical talks will continue to find an agreement on security and maritime services in the Strait, information sharing, administration and traffic management will also be discussed. Oman’s News Agency said that there will be joint management of the waterway and the compromise will stick to international law. The deal is currently only provisional as further work is needed to ensure multilateral control over the waterway and that other Gulf nations will be involved in future agreements.
- The NY Times reported that the US is returning ambassadors to the Middle East consistent with Secretary of State Rubio’s comments that “for time being” the US is unlikely to resume Iran strikes and that it will focus on economic pressure.
- Bloomberg reported that US oil inventories increased 4.2mn barrels last week, according to people familiar with the API data. However, there was destocking of products with gasoline down 3.2mn and distillate 500k. The official EIA data is out on Wednesday.
- Later the Fed’s Barkin speaks but the focus will be on July core PCE prices, the Fed’s preferred measure of inflation. Bloomberg consensus expects it to be steady. US preliminary July durables and updated Q2 GDP are also released. The ECB’s Cipollone appears.
CHINA: Banks Pricing News Sees Vol. Rise ahead of OMO Ops tomorrow
Aug-26 04:37
- News that Chinese commercial banks have started pricing new debt floating-rate notes off the overnight funding cost has created short-term positioning volatility inside the interbank market and sees a modest move higher in yields today.
- Ongoing news reports from various parts of the government continue to focus on fiscal measures, reducing expectations for monetary easing. This as yields reach near term lows was enough to support the softening.
- The 5-Yr is up +2.1bps to 1.393% whilst the 10-Yr is up +0.4bps to 1.686%. The 30-Yr is up +1.0bps to 2.173%.
- What further adds to the view that this is a minor adjustment is the announcment that the PBOC will use the overnight tenor in tomorrow's Open Market Operations (OMO). According to an official announcement from the central bank, the PBOC will systematically conduct overnight reverse repo operations starting tomorrow, August 27, through September 1, 2026, to manage short-term banking liquidity.
- This typically sees yields firm up and could see a retracement of the moves today.
- There is no significant auctions for the rest of the week.


