FRANCE: Lagarde Presidential Run Remains Unlikely Despite Early ECB Resignation
Oct-29 10:37
European Council President Antonio Costa has published a statement: https://www.consilium.europa.eu/...
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
UK DATA: Lending Data in Line, Mtge Rates Up; Consumer Credit Continues Stronger
Sep-29 10:37
BOE lending data was broadly in line with consensus in August, particularly net lending secured on dwellings, whereas mortgage approvals fell slightly below consensus as mortgage rates rose across the maturity profile. Although the housing side of the release looks to have stabilised in recent months, consumer credit continued its strong run in August (printing the highest on record) on particularly strong credit card lending.
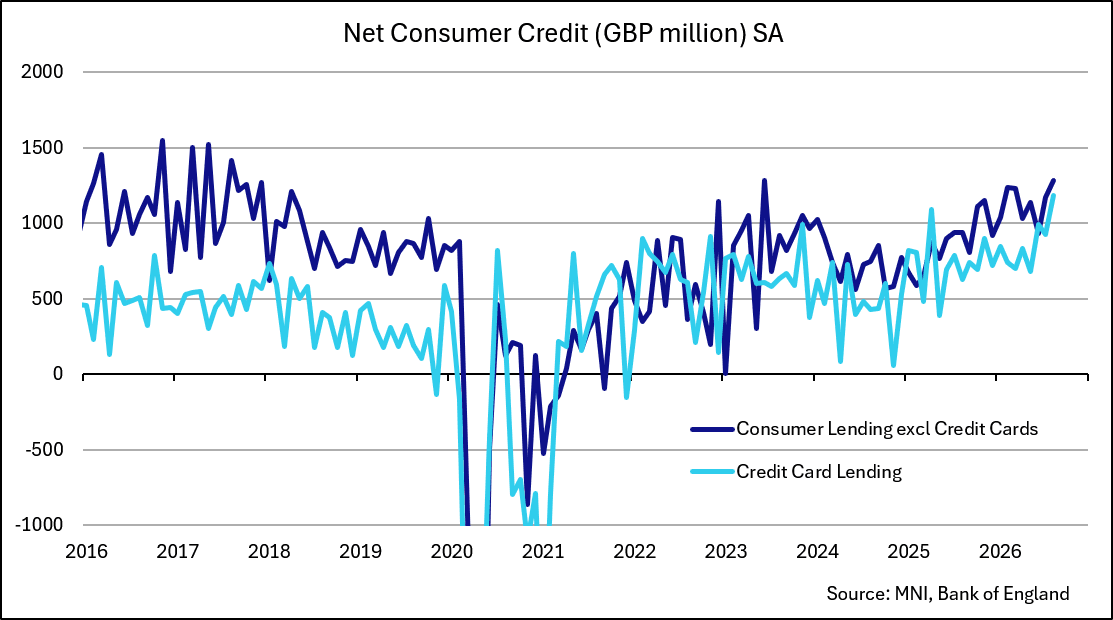
- Consumer credit extended its strong run, growing to GBP2.46bln in August (1.9bln cons, 2.10bln prior rev from 2.01bln). This reading is the highest in the series (back to 1993). With the labour market still deteriorating (even if it is bottoming out) we assume that this increase in consumer credit is for negative reasons as fuel prices etc increase. However, the latest GfK consumer confidence figures have indicated rising consumer confidence (albeit still at subdued levels) which may also influence the data positively. It's hard for the MPC to really take too much of a signal from this at present.
- "Within this, net borrowing through credit cards was £1.2 billion in August, up from £0.9 billion in July. Net borrowing through other forms of consumer credit (such as car dealership finance and personal loans) increased to £1.3 billion in August, from £1.2 billion in July." - from the BOE's press release.
- We add that the credit card lending figure is the highest since March 2004, and it was last above GBP1bln in April 2025. In August, credit card lending made up around half (48%) of the consumer credit figure, close to the 52% seen in July, and (excluding July) the highest share since September 2025.
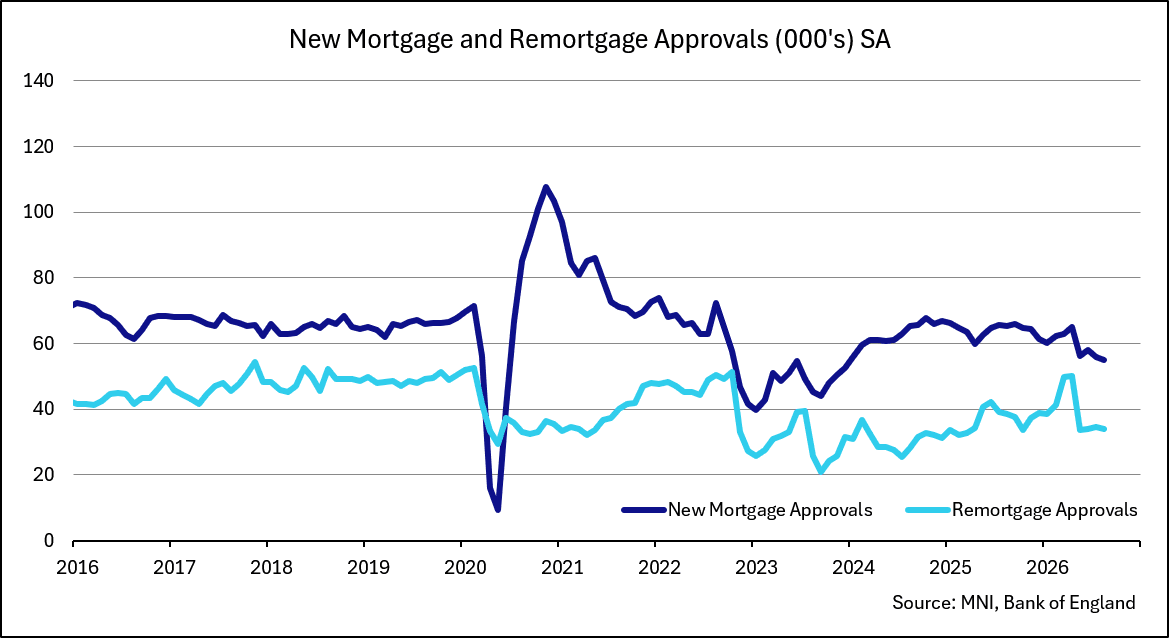
- On the housing side, things were more in line: net lending on dwellings rose to GBP4.41bln (4.4bln cons, 4.08bln prior rev from 4.29bln), while mortgage approvals were a touch on the softer side at 54.9k (56.1k cons, 55.9k prior rev from 56.1k). The latter has seen some stability in recent months after a decent fall in May.
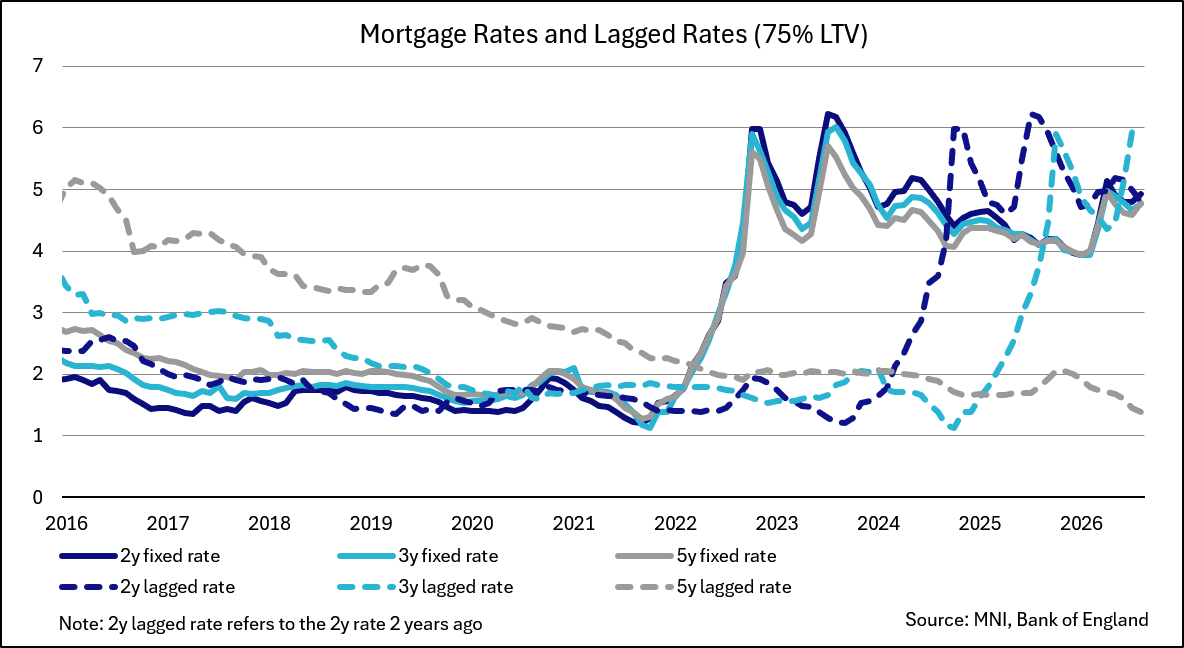
- On mortgage rates, rates rose 0.1-0.2pp in August across the maturity profile (2y to 10y 75% LTV fixed rates).
- The rise in rates has steepened the maturity cliff for those remortgaging from a maturing 5-year term, who would now see a 3.4-3.5pp jump in their mortgage rates, while for those coming off a 3-year term this is around a 1.1-1.2pp fall given the rise in rates around this time three years ago.
- Those remortgaging from a 2-year term, however, would now see a flat-to-0.1pp rise in their mortgage rate, compared to a 0.2-0.4pp fall if they were to have done so in July, as rates were falling this time two years ago.
- Also in the release, M4 money supply ex-intermediate OFCs grew 0.5%M/M, sa (-0.3% prior), while 3M/3M SAAR growth picked up to 2.8% (from 2.2% prior). On an annual basis, the same measure grew 4.4%Y/Y (4.3% prior).
OPTIONS: Expiries for Sep29 NY cut 1000ET (Source DTCC)
Sep-29 10:36
- EUR/USD: $1.1400(E4.1bln), $1.1440-50(E780mln), $1.1490(E1.1bln)
- GBP/USD: $1.3285-00(Gbp750mln)
- AUD/USD: $0.7000(A$515mln)
- USD/CAD: C$1.2838-39($830mln)
- USD/CNY: Cny6.6800($620mln), Cny6.6850($600mln)
GLOBAL: "*SAUDI ARABIA ISSUES POTENTIAL DANGER ALERT IN NAJRAN - bbg"
Sep-29 10:34
"*SAUDI ARABIA ISSUES POTENTIAL DANGER ALERT IN NAJRAN - bbg"


