ECB: JP Morgan Now Expect Hikes In June and September
Apr-16 12:54
JP Morgan have also pushed back their ECB hiking call, now expecting hikes in June and September (vs April and July previously). The new call is broadly consistent with market pricing. ECB-dated OIS price ~21bps of hikes through June and 43bps through September.
- JPM write that “ Despite the ticking clock on the supply of energy and commodities, energy forward curves have recently been quite stable (from a macro perspective) and gas prices have surprised on the downside even as refilling storage ahead of next winter looks challenging. Unless market pricing on energy changes significantly over the next two weeks, the ECB’s current inclination to be patient will likely remain in place. “
- “The ECB staff’s forecasts have provided a solid anchor for a moderate tightening. That still feels likely”
- “Beyond June, the focus for subsequent decisions would shift more and more to whether second-round effects are materialising, especially via wages. “
- They caveat that “We see risks to this call of two hikes in June and September skewed to the ECB ending up delivering only the first of these, and we would also not completely dismiss a look-through scenario. “
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
BONDS: Downside In Crude Provides Support
Mar-17 12:52
LLight downside in crude oil provides support for global FI markets through early NY trade. Comments from U.S. NEC director Hassett, pointing to the capability to upsize the SPR release, provides the likely source of pressure for crude.
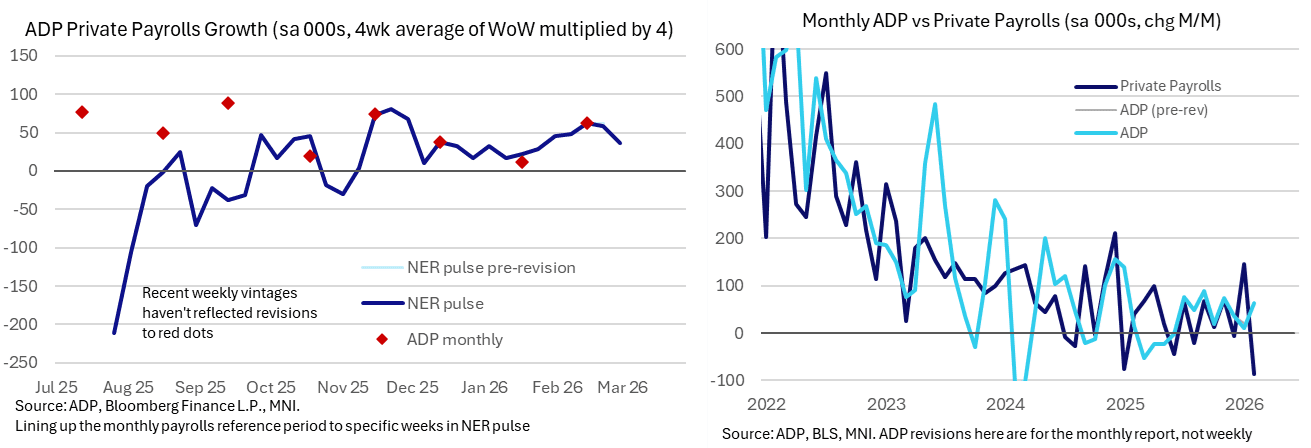
- A slight cooling in the weekly ADP employment figure is also noted, but that is a second order input at best.
- The pullback in crude comes despite ongoing hardline rhetoric out of Iran in light of the reported killing of two of the country’s most senior officials.
- Comments out of the U.S. & Israel remain non-committal when it comes to the exact timing of the end of the conflict, albeit with the U.S. still referencing the already touted 4- to 6-week initial timeframe that was envisaged.
US DATA: Private Sector Hiring Lost A Little Momentum Heading Towards March
Mar-17 12:26
- ADP weekly employment growth cooled a little in today’s update, with an average weekly increase of 9k in the four weeks to Feb 28 after a slightly downward revised 14.75k (initial 15.5k) up to Feb 21 and an unrevised 15.5k up to Feb 14.
- The monthly equivalent of 36k cools from the 63k in the February monthly update released two weeks ago (as always based on a reference week including the 12th day of the month per BLS payrolls) but is above the 11k from January.
- Roughly speaking, this weekly series continues to offer signs of steady but modest private sector job creation compared to some wildly differing indications from the BLS private payrolls data with February’s -86k hit after jumping 146k in January.
OUTLOOK: Price Signal Summary - Gold Remains Above Support
Mar-17 12:14
- On the commodity front, Gold continues to trade below $5419.11, the Mar 2 high. The short-term outlook remains bullish - for now - following the recovery that started Feb 2. The metal has cleared all key retracement points of the sell-off between Jan 29 - Feb 2. This signals scope for an extension towards key resistance and the bull trigger at $5595.5, the Jan 29 high. Initial firm support to watch lies at $4928.6, the 50-day EMA.
- A bull wave in WTI futures remains intact. The recent sharp pullback from the Mar 9 high, has allowed an extreme overbought trend condition to unwind. The key support zone to monitor is $80.37 - $71.03, the area between the 20- and 50-day EMAs. A clear break through this zone would signal a possible trend reversal. On the upside, a continuation higher near-term would open $103.15 next, the 61.8% retracement of the Mar 9 - 10 sell-off.
Related bullets

Related by topic
EUR/USD
Bunds
Germany
Euribor
European Central Bank
Trending Top

Sep-18 18:49
Sep-18 17:27

