EUROZONE ISSUANCE: EGB Supply Daily
Netherlands and Italy will hold the non-competitive rounds of their auctions today. Earlier this wee...
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
BRENT TECHS: (Z6) Northbound
- RES 4: $115.72- 2.382 proj of the Jul 2 - 23 - Aug 5 price swing
- RES 3: $113.13 - 76.4% retracement of the Apr - Jul bear leg (cont)
- RES 2: $109.31 - 2.000 proj of the Jul 2 - 23 - Aug 5 price swing
- RES 1: $107.33 - High Oct 8
- PRICE: $105.94 @ 07:36 BST Oct 14
- SUP 1: $100.61 - 20-day EMA
- SUP 2: $95.11 - 50-day EMA
- SUP 3: $82.89 - Low Aug 26
- SUP 4: $75.77 - Low Aug 5 and a key support
The trend condition in Brent futures is bullish and a fresh cycle high on Monday reinforces current conditions. The break higher maintains the price sequence of higher highs and higher lows. Note the moving average studies remain in a bull-mode position, highlighting a dominant uptrend. Scope is seen for an extension towards 109.31 next, a Fibonacci projection. Initial key support to watch lies at the 50-day EMA, at $95.11.
SWEDEN: September Flash Confirmed, Goods and Services Divergence Noted
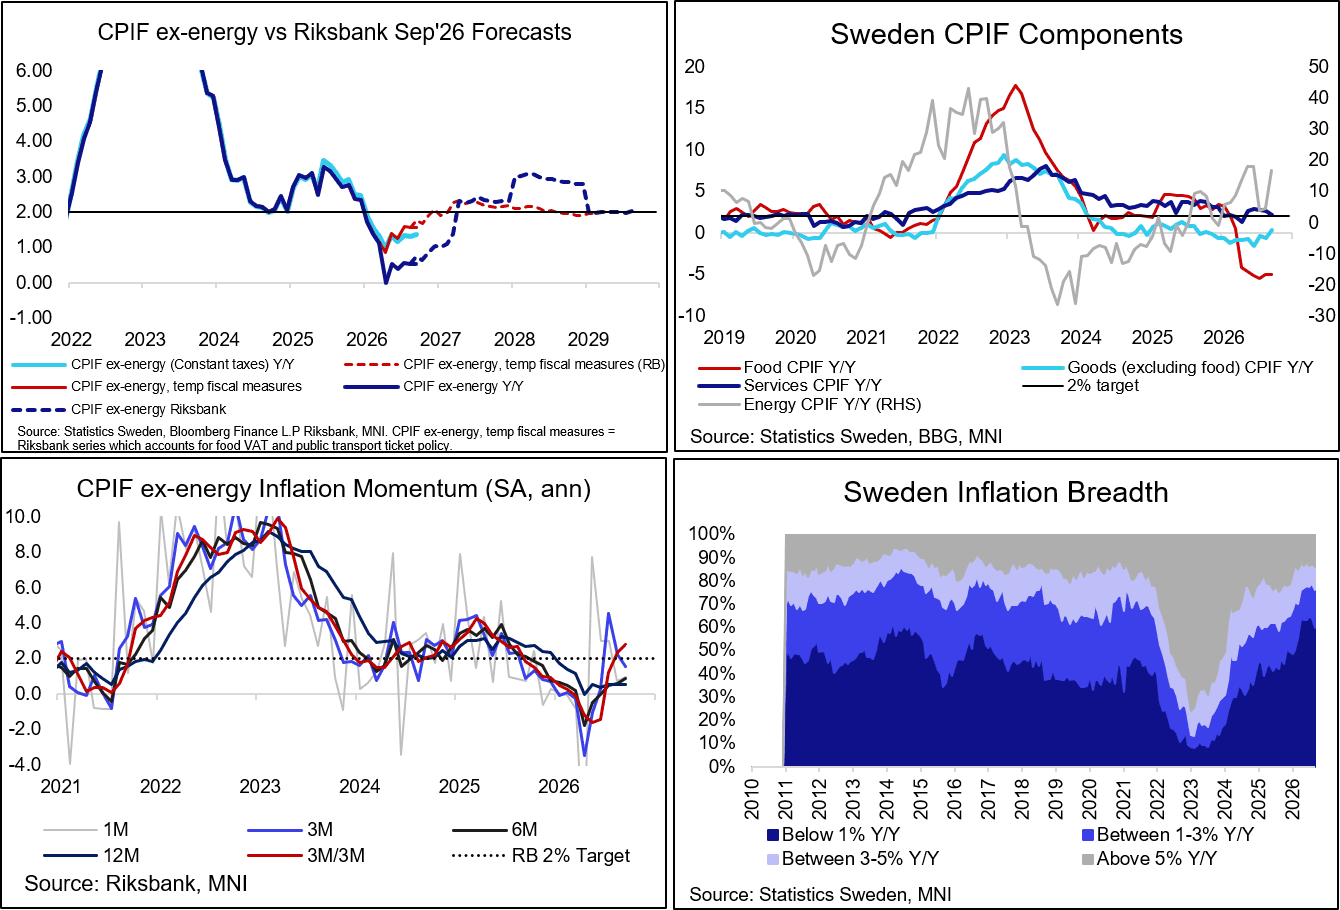
- CPIF ex-energy and temporary fiscal policies was steady at 1.6%, below the Riksbank’s 1.8% September MPR forecast. CPIF ex-energy with constant tax rates was 1.4% Y/Y (vs 1.3% prior). There was a divergence between goods and services categories in September - the latter could be a temporary dynamic given sharp pullbacks in volatile accommodation services and a curious drop in insurance prices.
- On a seasonally adjusted basis using the X-13 methodology, CPIF ex-energy inflation rose 0.08% M/M in September, after 0.06% in August and 0.25% in June and July. It still leaves 3m/3m annualised momentum up on the month to 2.77% (vs 2.32% prior), but this should mechanically fall back next month as April’s -0.8% reading drops of the denominator.
- Level 1 COICOP2 categories were in line with the flash, with major component groups seeing steady annual inflation rates relative to August. Services and food drove the downside surprise versus last week’s flash consensus of 0.5% M/M.
- Goods inflation was confirmed at 0.3% Y/Y (vs -0.6% prior). Accelerations look broad-based across clothing/footwear, furniture, medicines/health products, ICT equipment and recreational goods.
- Services eased to 2.2% Y/Y (vs 2.7% prior). There was an easing of ICT services and insurance (-2.9% M/M; 0.95% Y/Y vs 4.6% prior). This was the largest M/M drop in insurance prices in Stats Sweden’s record, driven by a 4.8% M/M fall in personal transport insurance.
- Looking at volatile items, airfares fell 3.75% M/M but were up 5.1% Y/Y (vs 4.2% prior). Package holidays were 11.4% Y/Y (vs 12.9% prior) while accommodation services were 0.4% Y/Y (vs 3.6% prior).
- The proportion of COICOP2 subcomponents with inflation rates above 3% Y/Y ticked up to 24%, the highest since April and after 21% in August.
STIR: Measured Dovish Reaction As BoE Hawk Pill is More Cautious Than Markets
Dovish adjustments seen in GBP STIRs seen through early London trade on comments made by hawkish BoE dissenter Pill, who expressed some scepticism when it comes to the idea that that the BoE will need to hike rates by the ~100bp that is currently priced into markets. He went on to note that the Bank would need to see “more concrete evidence” of risks to tighten by that amount.
- This comes after BoE Governor Bailey reiterated the idea that the energy shock is getting harder to avoid, despite limited signs of inflationary impact in the UK at this stage.
- BoE-dated OIS flat to 3bp less hawkish across liquid contacts, showing 24bp of tightening for next month, 38bp through December and 96bp through June.
- SONIA futures little changed to +6.0. SFIZ7 +2.5 vs. pre-Pill levels.
- Elsewhere, the latest Deloitte CFO survey revealed that “CFOs have revised their expectations for both inflation and interest rates over the next 12 months. They now expect inflation to be 3.4% in a year's time, up from 3.0% in the previous survey%.” The survey also noted that “cost reduction remains the top priority.”
- Little of note on the UK macro calendar for the remainder of the day.


