GILTS: Curve Bull Steepens
Oct-02 07:15
Yields 3-5bp lower and the curve bull steepens in light of yesterday's recovery in wider core global...
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
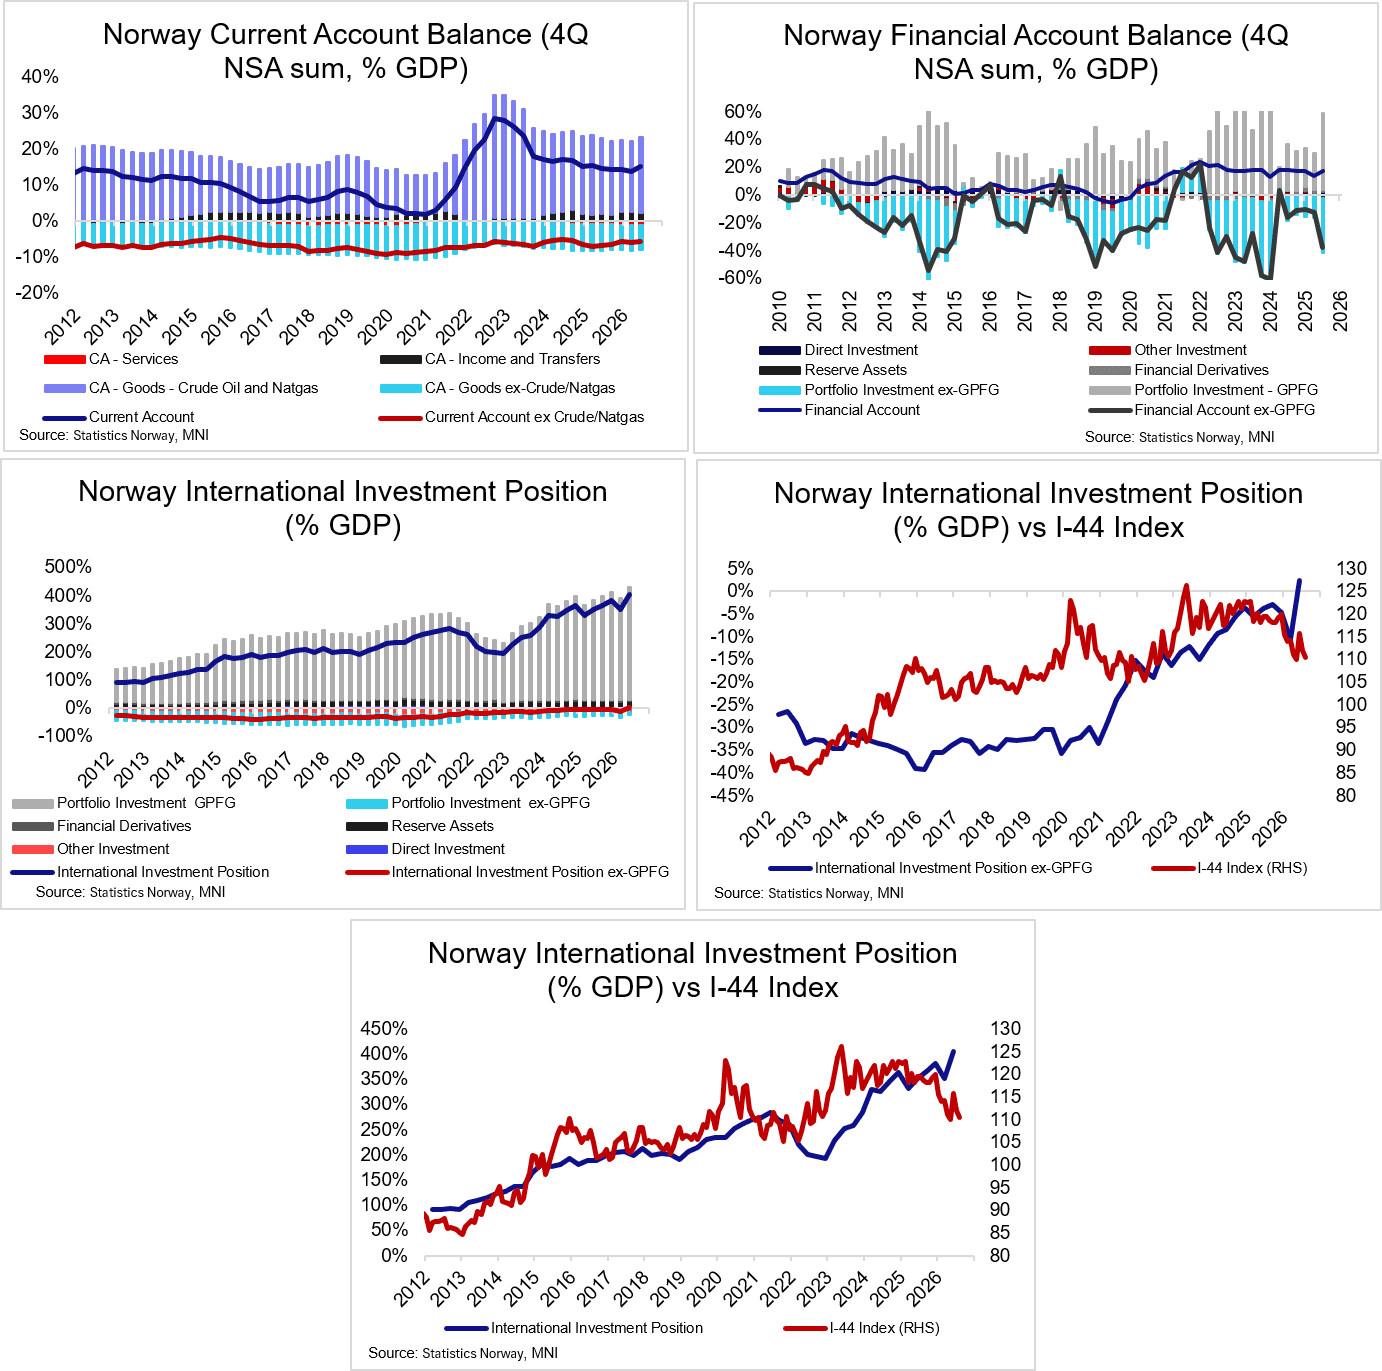
NORWAY: IIP Rises To Fresh ATH On Strong Foreign Asset Returns, CA Surplus Widen
Sep-02 07:13
The Norwegian current account surplus was NOK297bln in Q2, up from NOK248bln in Q1.
- The increase was driven primarily by a rise in the crude oil and natural gas surplus to NOK347bln (unsurprising given the energy price/geopolitical environment). However, a decline in the services deficit to NOK10.3bln and a rise in the income and transfers surplus to NOK46.9bln also contributed. The goods ex-oil/gas deficit widened to NOK104bln.
- On a 4Q rolling basis to GDP, the current account surplus rose to 15%, up from 14% in Q1 for the widest in a year. The oil/gas surplus rose to 21% GDP (vs 20% prior), while the services, goods ex-oil/gas and income balances were steady.
- The financial account balance rose back to 17% GDP (again on a 4Q rolling basis) in Q2, after 14% in Q1 and 18% in Q4 2025.
- Within this, the direct investment outflow (i.e. from NOK) was 2% GDP (vs 1% in Q1), while the portfolio investment outflow rose to 20% GDP (vs 17% in Q1). Flows related to the government’s pension fund is a key component of the portfolio investment category. Crudely splitting out GPFG and non-GPFG flows (using monthly GPFG data from Norges Bank) indicates that the GPFG outflow was 55% GDP in Q2 (vs 27% in Q1).
- This leaves Norway’s international investment position at a fresh high of 405% GDP – the majority of which represents GPFG assets. This is up from 352% in Q1, aided by strong returns on foreign portfolio assets. Statistics Norway also highlights that a weaker NOK in Q2 pushed the IIP higher.
GILTS: '08 High In 10-Year Yields Remains Intact
Sep-02 07:12
Yields 2.5-3.5bp higher, curve flattens.
- The ’08 yield high in 10s (5.274%) remains intact at the open, continuing to present the major bearish target on the curve.
- 6.00% is a little over 10bp away from prevailing levels in 30s.
- Further forward on the curve, year-to-date highs in 2s (4.713%) remain untested.
- Week-to-date hawkish repricing has driven meaningful curve flattening.
- 2s10s nears 60bp, a level not traded below since late July. A break there would expose the July low (58.24bp).
- 5s30s is through 115bp, but the July low (110.41bp) remains untested
MIDEAST: IDF Kill Hamas Commander
Sep-02 07:08
"*IDF KILLS COMMANDER FROM HAMAS MILITARY SECURITY DEPT" - BBG

Trending Top
Oct-02 07:55

Oct-02 05:06

