CANADA: Analysts See Importance Of October CPI For BOC As Open Question (2/2)
Nov-13 19:46
See below for a compilation of analyst expectations for the October CPI report. Most now anticipate ...
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
US TSYS: Tsys Mostly Recover From Post-CPI Lows, Curves Twist Flatter Ahead PPI
Oct-14 19:40
- Treasuries have fully recovered from this morning's post-CPI lows, Tsy futures near the top end of the range - except for the short end: Curves twist flatter (2s10s -3.362 at 38.155, 5s30s -2.636 at 52.746) with projected rate hikes are near session highs. 25bp hike in Dec more than fully priced in.
- The above-expected 0.65% M/M headline CPI reading for September (0.48% MNI median) marked an acceleration from 0.40% in August and was the second-highest print on an unrounded since June 2022 (just edging the 0.64% in April this year, but below the 0.87% in March at the outset of the US-Iran War).
- Potential drivers: position squaring ahead of PPI and retail sales and weaker equities perhaps lending buying in intermediates to long end.
- Making headlines: cloud computing & AI data center operator CoreWeave trades -11.65% at the moment, as concerns over AI buildout costs and over-leveraged portfolios spooked investors, drawing a "Yikes" post by Elon Musk on X after CoreWeave's unsecured bonds maturing in 2032 (valued at $1.25 billion) surged toward 15%.
- PPI will be looked at most closely for the PCE component read-through, the aggregates will also be scrutinized for signs that rebounding energy prices are being reflected in pipeline pressures. Expectations are for overall final demand PPI to pick up to 0.6% M/M in September from 0.4%, with core steady at 0.3%, leaving those at 5.4% (unch) and 4.8%, respectively.
- Crude oil has risen further on Wednesday as markets digest further vessel attacks in the Strait of Hormuz alongside Saudi/Houthi and Russia/Ukraine hostilities.
- Look ahead: Japan Machine Orders followed by Australia September Labour Market data. In the US: PPI, Retail Sales and weekly jobless claims for the US. Central Bankers: BoC's Macklem, ECB's Pereira, Kocher, Moulin and Simkus as well as BoE's Pill and SNB's Schlegel will also appear.
AUDUSD TECHS: Gains Considered Corrective
Oct-14 19:30
- RES 4: 0.7238 High Sep 09 and a S/T bull trigger
- RES 3: 0.7140 High Sep 21
- RES 2: 0.7049 50-day EMA
- RES 1: 0.7011 20-day EMA
- PRICE: 0.6956 @ 16:52 BST Oct 14
- SUP 1: 0.6904 Low Oct 1
- SUP 2: 0.6865 Low Jun 30 and a key M/T support
- SUP 3: 0.6849 50.0% 2025 - 2026 bull leg
- SUP 4: 0.6833 Low Mar 30
The current downtrend in AUDUSD remains intact and the latest recovery is - for now - considered corrective. Price has recently traded through 0.6953, the 76.4% retracement point of the Jun 30 - Sep 9 bull leg. The breach suggests potential for an extension towards 0.6865, the Jun 30 low and an important medium-term support. Initial firm resistance is at 0.7049, the 50-day EMA. A move through this average would be a bullish development.
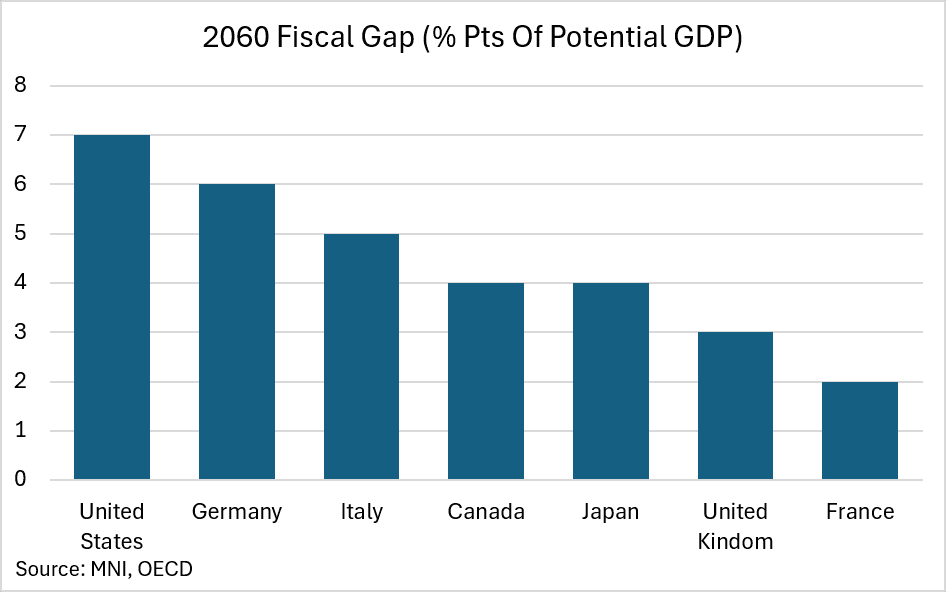
FISCAL: US Has G7's Weakest Long-Term Fiscal Stability; France Best- OECD
Oct-14 19:15
- The U.S. requires the most fiscal adjustment over the 2027-to-2060 period to stabilize gross debt-to-GDP the OECD says. (How large is the long-term fiscal challenge in OECD countries?).
- "Without revenue adjustments or spending reductions, government net debt could rise by 43pp of GDP by 2045 in the median country, and by up to 124pp in the United States."
- "Similarly, in Canada, France, and the United Kingdom, meeting NATO defence spending commitments could add roughly as much, or more, to debt as rising spending on health, long-term care, and pensions."
- "The median country would require a fiscal adjustment of 4.7pp of GDP between 2027 and 2060 to stabilise debt, with substantially larger adjustments in some countries."