EUROSTOXX50 TECHS: (Z6) Bearish Theme
* RES 4: 6612.00 High Aug 13 and key resistance * RES 3: 6533.00 High Aug 23 High Sep 4 * RES 2: 644...
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
UK DATA: BRC Shop Price Inflation Up to Two-Year High, Indirect Effects Showing?
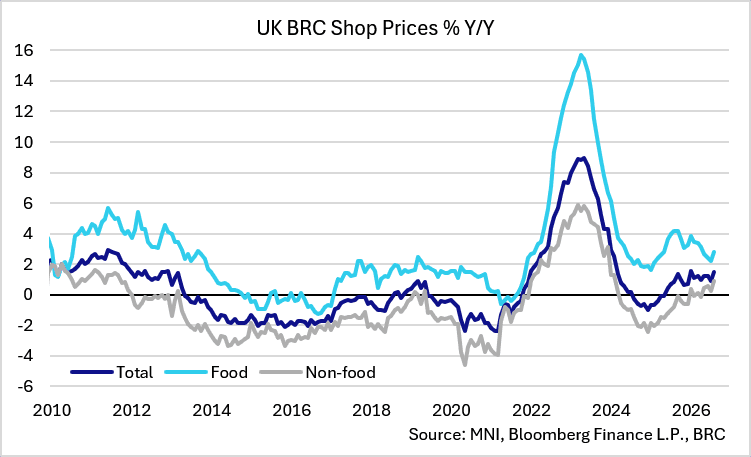
BRC shop price inflation (released overnight) accelerated to 1.5%Y/Y in August (0.9% Jul, 1.2% Jun), matching its highest print since February 2024 (when it was 2.5%) - it was also at 1.5% in January this year. The acceleration was broad-based across food and non-food items, particularly for ambient food and electronics. While the print suggests indirect effects starting to show, the reacceleration is also likely partly attributable to timing of summer promotions (despite continued low clothing prices).
- "The impact of higher energy, input and commodity costs is beginning to filter through into prices, particularly for ambient foods which are typically imported and processed." (from the BRC's press release).
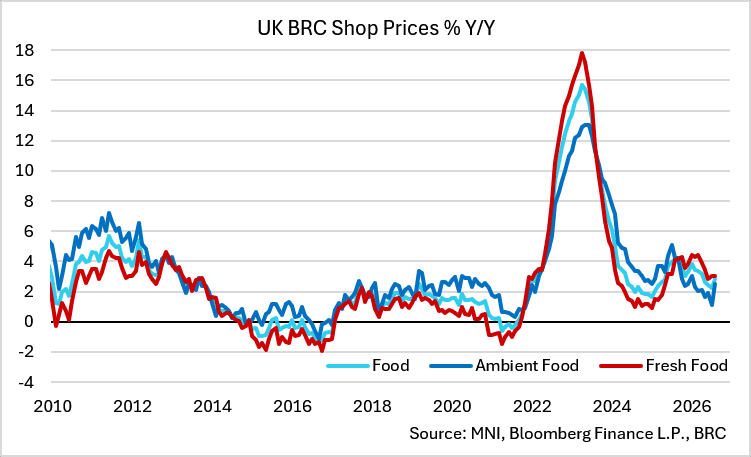
- Food inflation picked up to 2.8%Y/Y (2.2% Jul, 2.4% Jun), off its recent low but still below April's 3.1% - driven entirely by a reacceleration in ambient food to 2.5%Y/Y (1.1% Jul, 1.9% Jun), its highest since January (when it was 3.1%). We could be seeing some unwind of snacks/alcohol promotions during the World Cup, which were noted in last month's release.
- Last month's soft ambient food inflation was likely also driven by a base effect from a particularly strong July last year (which marked the 2025 peak at 5.1%Y/Y).
- In contrast, fresh food inflation slowed a touch to 3.0%Y/Y (3.1% Jul, 2.8% Jun).
- "In non-food, electrical prices rose amid the ongoing AI boom, which is forcing up the price of memory chips and storage. Meanwhile, retailers kept clothing prices low to offer value for families getting ready for the new school year." Non-food inflation rose to 0.9%Y/Y (0.2% Jul, 0.6% Jun), also the highest since February 2024.
- If we see prints like this repeated, they could give some indication of indirect effects from higher energy prices feeding through to consumer prices more broadly. However, as we noted earlier, part of the acceleration is due to the end of base effects and part due to the timing of promotions. We also note the narrow range of goods here compared to official CPI data (which are due Wed 16 Sep).
- The price collection period spans 1 - 7 August 2026, earlier in the month than official CPI data. The ONS will collect prices around the second or third Tuesday of the month (11 or 18 Aug).
- Looking ahead, the press release notes "pressures are continuing to build across supply chains, and we can expect price competition to intensify as we move into the autumn months."
EUROZONE ISSUANCE: EGB Supply Daily
Germany will hold an auction today while Spain, France and Ireland are due to hold conventional auctions on Thursday and Belgium will potentially hold an ORI auction on Friday. The EU held an auction yesterday. There is also the possibility of syndications in the week with Italy a prime candidate. We look for gross issuance of E40.2bln (ex-retail) in the week, up from E24.8bln (ex-retail) last week.
- Germany will look to kick off September issuance this morning with E5.5bln of the 2.90% Oct-31 Bobl (ISIN: DE000BU25075) on offer.
- Spain will come to the market on Thursday to hold a Bono/Obli/ObliEi auction. On offer will be a combined E5.0-6.0bln of the on-the-run 3-year 2.35% Mar-29 Bono (ISIN: ES0000012P90), the on-the-run 5-year 2.60% May-31 Bono (ISIN: ES0000012Q16) and the previously on-the-run 10-year 3.30% Apr-36 Obli (ISIN: ES0000012Q08) alongside E250-750mln of the 2.05% Nov-39 Obli-Ei (ISIN: ES0000012M69).
- France will then look to hold a LT OAT auction, also on Thursday for a combined E11.5-13.5bln. On offer we be the 1.25% May-36 OAT (ISIN: FR0013154044), the on-the-run 10-year 3.7% Nov-36 OAT (ISIN: FR0014018YR0), the 0.50% May-40 OAT (ISIN: FR0013515806) and the on-the-run 20-year 4.10% May-46 OAT (ISIN: FR0014015MU5).
- Ireland will come to the market on Thursday with an IGB auction. On offer will be a combined E1.00-1.25bln of the 0.35% Oct-32 IGB (ISIN: IE00BMD03L28) and the 0.40% May-35 IGB (ISIN: IE00BKFVC345).
- Belgium will come to the market on Friday with ORI Facility. If it decides to hold the optional auction, details will be confirmed on Thursday.
EURGBP TECHS: Resistance Intact
- RES 4: 0.8652 High Jun 26
- RES 3: 0.8632 76.4% retracement of the Jun 22 - Jul 15 bear leg
- RES 2: 0.8601 61.8% retracement of the Jun 22 - Jul 15 bear leg
- RES 1: 0.8588 High Jul 30 and a key resistance
- PRICE: 0.8569 @ 06:45 BST Sep01
- SUP 1: 0.8532 Low Aug 12 and key S/T support
- SUP 2: 0.8518/8455 Low Jul 22 / 15 and the bear trigger
- SUP 3: 0.8443 2.236 projection of the May 18 - 25 - Jun 22 swing
- SUP 4: 0.8374 76.4% retrace of the Dec 19 ‘24 - Nov 14 ‘25 bull leg
EURGBP continues to trade in a range. Key short-term resistance is at 0.8588, the Jul 30 high. A clear break of it would suggest scope for a stronger corrective bull theme and highlight a clear breach of the 50-day EMA, at 0.8570. This would open 0.8601, a Fibonacci retracement. Note that medium-term trend signals still highlight a dominant downtrend. Initial firm support to watch is 0.8532, the Aug 12 low. Clearance of it would be bearish.


