FOREX: USD Rally Gains Momentum as Risk Sentiment Further Wanes
- The risk selloff gathered pace on Tuesday, as the ongoing conflict in the Middle East has further boosted oil prices and significantly weighed on equities & precious metals. These dynamics have fostered an extension of US dollar strength, prompting the USD index to briefly rise more than 2% to print fresh three-month highs at 99.68.
- While the dollar strength has been broad based, the likes of AUD, NZD and Scandinavian FX have been notable laggards in G10, while the EM FX basket has also suffered considerable losses.
- EURUSD plumbed new lows on the year below 1.1573 and feel to a session low of 1.1530 before stabilising. Moves this week have been exacerbated by a break of trendline support (drawn from the 2025 lows, bolstering the current bear cycle that remains in play for the pair. 1.1573 was considered a key support and so today’s close will be important for a bearish extension below 1.15.
- Despite the impressive intra-day weakness for AUD, the AUDUSD trend structure is unchanged, it remains bullish and for now, with today’s sell-off appearing corrective. Key support to monitor is around the 50-day EMA, at 0.6920. A clear break of the average would alter the picture.
- EM FX weakness remains pronounced on Tuesday, with high-beta currencies coming under pressure amid the stronger USD, surging energy prices, and renewed steepening in global yield curves. As noted earlier, the HUF is on track for its largest single-session decline in percentage terms since 2010, driven primarily by a roughly 25% jump in natural gas prices.
- Elsewhere, precious metals weakness has assisted the over 3% rally for USDZAR today. Today’s gains are also being amplified by the pair’s break above its 50-day EMA (16.2570) – a level it has not traded above since November last year. Positioning dynamics will likely be providing further headwinds for some other EM currencies – notably in LatAm, both MXN and BRL have declined over 2%, while CLP is down 3.2% as we approach the close.
- Australian GDP and China PMIs are scheduled on Wednesday, before Swiss CPI headlines the European calendar. In the US, ADP employment and ISM Services PMI are scheduled.
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
FED: Gov Bowman: We Should Be Ready To Adjust Rates Toward Neutral
Fed Vice Chair for Supervision Miki Bowman said Friday that while she didn't elect to cut rates in January, she could be ready to cut in March. She made clear that she saw 3 cuts this year in the December Dot Plot (as MNI had assumed), making her one of the biggest doves on the Committee. (speech text here)
- "I continue to see policy as moderately restrictive, and, looking ahead to 2026, my Summary of Economic Projections includes three cuts for this year."
- The key is that "downside risks to the labor market have not diminished, and we should not overemphasize the latest reading on the unemployment rate...My view is that we should continue to focus on downside risks to our employment mandate, and the description of the labor market is helpful to communicate that we are not overly confident. History tells us that the labor market can appear to be stable right up until it isn't."
- "Absent a clear and sustained improvement in labor market conditions, we should be ready to adjust policy to bring it closer to neutral...we should also not imply that we expect to maintain the current stance of policy for an extended period of time because it would signal that we are not attentive to the risk that labor market conditions could deteriorate."
- "In my mind, the question at this meeting was about the timeline for implementing these cuts, essentially choosing between continuing to remove policy restraint and arriving at my estimate of neutral by the April meeting, or moving policy to neutral at a more measured pace throughout this year."
- "I am also reluctant to take meaningful signal from the latest data releases given the statistical noise introduced by the government shutdown" but "Given that by the time of our March meeting we will have received two additional inflation and employment reports, I saw merit in waiting to take action."
MACRO ANALYSIS: MNI US Macro Weekly: The Fog Of Warsh
We've just published our US Macro Weekly - Download Full Report Here
- The largest rate moves of the week surrounded President Trump’s selection of former Fed Governor Kevin Warsh as the next Fed chair when Powell’s term in the position ends in May.
- A next Fed cut is close to being fully priced for the June meeting again (22bp, the first meeting under the new Fed chair) whilst there are two 25bp cuts fully priced by year-end.
- While historically more hawkish than most of the other contenders but also favoring economic productivity arguments for expecting inflation to remain in check amid solid growth, there remains high uncertainty on what the Fed might look like under Warsh’s leadership. (More from our Policy Team on page 18.)
- That includes policy on the balance sheet (preferring a smaller one) and communications, the Fed’s reach outside of core monetary policy channels, and even personnel, having previously said "I think what we need is regime change at the Fed, and that's not just about the Chairman, it's about a range of people...it's about breaking some heads, because the way they've been doing business is not working."
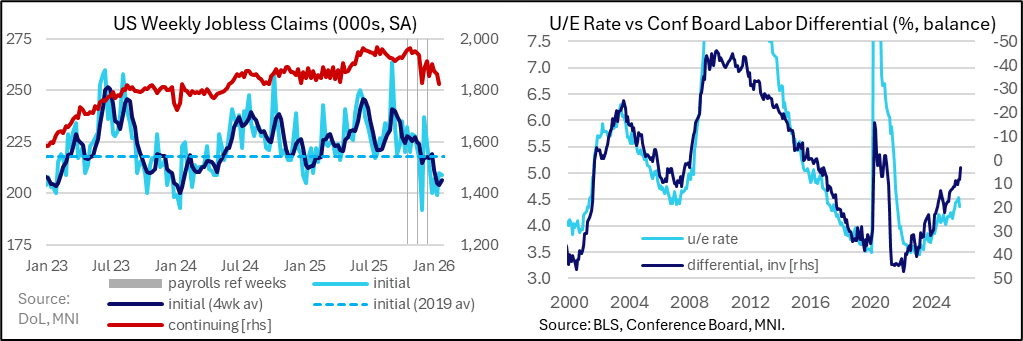
- Warsh or not, one impetus for consensus on a resumption of Fed easing would be a clear deterioration in the labor market, but here the data evidence remained mixed. Jobless claims remain at a healthy level despite initial claims surprising higher for the first time since Dec 11 after a particularly impressive run but with residual seasonality concerns. Continuing claims pushed lower still however but also with some questions over the role of unemployment insurance eligibility roll-off.
- A further acceleration of strong core PPI inflation trends had little impact on Friday against a backdrop of precious metal prices tumbling, whilst details confirmed strong core PCE estimates at ~0.4% M/M for Dec.
- Real GDP growth tracking for Q4 has been trimmed from 5.4% to a still very strong 4.2% after latest volatility in monthly trade reports. Capital goods imports are up strongly in tech-led strength but consumer and industrial imports are down heavily in a hangover from tariff front-running in Q1.
- Manufacturing firms’ sentiment firmed in January but consumer confidence slumped, with the lowest Conference Board metric since 2014 as consumer labor market perceptions softened further.
- The FOMC treaded a largely neutral path with its January decision, maintaining its easing bias but sounding slightly more patient in making its next move than it did last month. Markets took a very mildly hawkish interpretation with implied rates rising under 1bp for meetings to July but even less of a move further out, and the dollar remaining largely unmoved.
- Looking ahead, another government shutdown looms, starting Saturday, but with questions over its potential duration and breadth. In the event the BLS isn’t impacted, the nonfarm payrolls report for January will highlight the week’s economic data on Friday. The report will include benchmark revisions and will continue to see attention on the unemployment rate after its recent stalling around the 4.4% mark.
- We also get Treasury’s quarterly financing and borrowing updates, with attention on any revisions to its guidance on future increases in auction sizes.
US DATA: BLS Economist Matsumoto To Be Nominated As Commissioner: WSJ
The Wall Street Journal reports that President Trump will nominate Brett Matsumoto as the next Commissioner of the Bureau of Labor Statistics. The role has not been filled since Trump fired Commissioner McEntarfer in September shortly after weaker-than-expected nonfarm payrolls report, accusing her of manipulating the data for political reasons.
- Importantly what little we know about Matsumoto suggests that he shouldn't have too much difficulty receiving Senate confirmation, as he has relevant experience and educational background, with little in the way of political entanglements. From the WSJ report: "Matsumoto has worked as an economist at the BLS since 2015. Before spending much of the past year on assignment with the White House Council of Economic Advisers, he had no experience working in a political capacity. He earned a Ph.D. in economics from the University of North Carolina at Chapel Hill in 2015. Matsumoto didn't respond to requests for comment."
- Trump's previous nominee, E.J. Antoni, had his nomination withdrawn in October due to key Senators on the relevant Committee having reservations over his appointment. NPR reported at the time "Antoni's selection was praised by Trump loyalists like Stephen Moore and Steve Bannon. But it was roundly criticized by even conservative economists. Opponents said Antoni — who has spent most of his career at right-wing think tanks — lacked the expertise in statistical number crunching that's typical of previous BLS commissioners. A group of BLS supporters issued a statement Tuesday urging the president to choose a new nominee with a technical and non-partisan background."


