FOREX: USD Can't Extend Higher Amidst Tight Ranges, US NFP Later
The USD BBDXY index sits off earlier highs, last 1224.50 (earlier we got to 1226.17), down a touch v...
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
RBNZ: Cautious Rate Hike, OCR Profile Gives MPC Flexibility To Hold
The RBNZ hiked rates 25bp to 2.75% to bring inflation back to the 1-3% target band by “gradually removing stimulus”. It estimates the neutral rate at around 3% and so policy remains marginally stimulatory. The policy assessment was cautious pointing to uneven growth and global uncertainty. Given weakness in parts of the economy, higher unemployment profile but unchanged OCR, at this stage it seems likely the MPC will be looking to pause at October’s Review meeting before hiking in December with an updated outlook.
- Future decisions will depend on the “balance of risks” which the MPC believes allows it to “observe and assess the effects of reduced monetary stimulus”. It is quite possible that it could hold in October to monitor its 50bp of tightening on a delicate NZ recovery as well as hope global events have progressed. However, it remains “vigilant” and will “respond” to ensure inflation returns to target.
- Its forecasts, especially the OCR path, were little changed with the main adjustment the anchoring to actual data.
- It continues to expect headline inflation to be back in the band in Q2 2027 but at 2.6% rather than 2.4%. The return to the 2% mid-point has been delayed 6 months to H1 2028.
- The MPC said growth was “lacklustre” in Q2 but assumed that the recovery has now continued sounding cautious. It said that overseas demand had been “resilient” and export prices “strong” supporting NZ’s export sector. However, “weak income growth, job insecurity and flat house prices” weighed on household consumption and residential investment.
- It revised up the unemployment rate to peak at 5.5%, 0.1pp higher, in H2 2026 and then decline more gradually than expected in May, especially in 2028. The RBNZ believes as the recovery “gathers pace” the labour market and thus consumption will improve.
- GDP was revised down in 2027 but up in 2028.
CHINA: Key Local News Highlights - China-ASEAN trade up 24.7% i
Below is a selection of key recent onshore media highlights for China ICYMI :
MNI China Press Digest Sep 2: Social Security Fund, Auto, PV.
Tech Innovation (Xinhua): China leverages innovation hubs to boost new quality productive forces
Tax (Xinhua): China to tax foreign individuals' dividends from foreign-invested enterprises.
Autos (Xinhua): China issues guideline to regulate automakers' overseas competitive practices.
Trade (Global Times): China-ASEAN trade up 24.7% in first 7 months.
Tech Innovation (Global Times): China's sci-tech hubs forge tighter lab-to-market ties to power industrial upgrade .
Energy (China Daily): Solar eclipses coal as China's top power source.
Trade (China Daily): China-ASEAN FTA to help spur growth.
Manufacturing (China Daily): Private survey points to robust August manufacturing activity
M&A (Shanghai Sec): The M&A market is showing steady growth, with transaction logic shifting towards industry value integration.
Commodities (SCMP): In race with US for critical resources, China discovers major copper and gold deposit
STIR: RBA-Dated OIS Pricing Adds A Full Hike Post-Sept Meetings
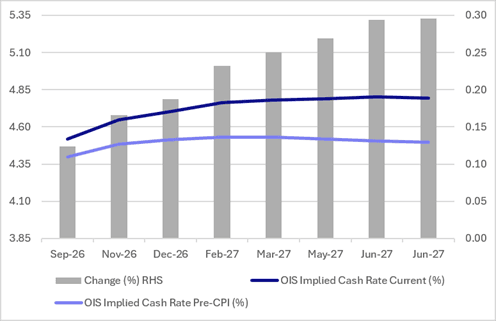
After today’s GDP release, RBA-dated OIS pricing is 12-30bps firmer than last week’s pre-July CPI data levels.
- Q2 GDP rose 0.4% q/q & 2.1% y/y, stronger than expected. Productivity remained poor as it was flat on the quarter and down 0.2% y/y.
- The Q2 national accounts showed that productivity growth remained elusive in Australia and ran at the same level as the average since Q1 2023 – no improvement for more than three years.
- The RBA saw this issue as a source of upside risks to its inflation outlook and the Q2 print will add to its concerns and the list of data suggesting another rate hike may be needed to bring underlying inflation back to the band.
- There are no CPI releases before the 29 September RBA decision and Q3 CPI prints 28 October ahead of the 3 November meeting.
- OIS pricing shows tightening risk across all meetings, with the probability of a 25bp hike rising from 67% (56% pre-data) for September to 142% (130% pre-data) by December 2026.
- Pricing is now 12-24bps bps firmer versus this month’s pre-RBA levels.
Figure 1: RBA-Dated OIS – Current Vs. Pre-July CPI
Source: Bloomberg Finance LP / MNI


