GLOBAL ENERGY: UKMTO Issues Another Vessel Incident Report
Oct-14 10:26
UKMTO has now issued its second incident report today for Oct. 13 attacks. A 19k ton container ship ...
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
STIR: No Further Reaction To Oil Climb With Fed Path Near Hawkish Extremes
Sep-14 10:23
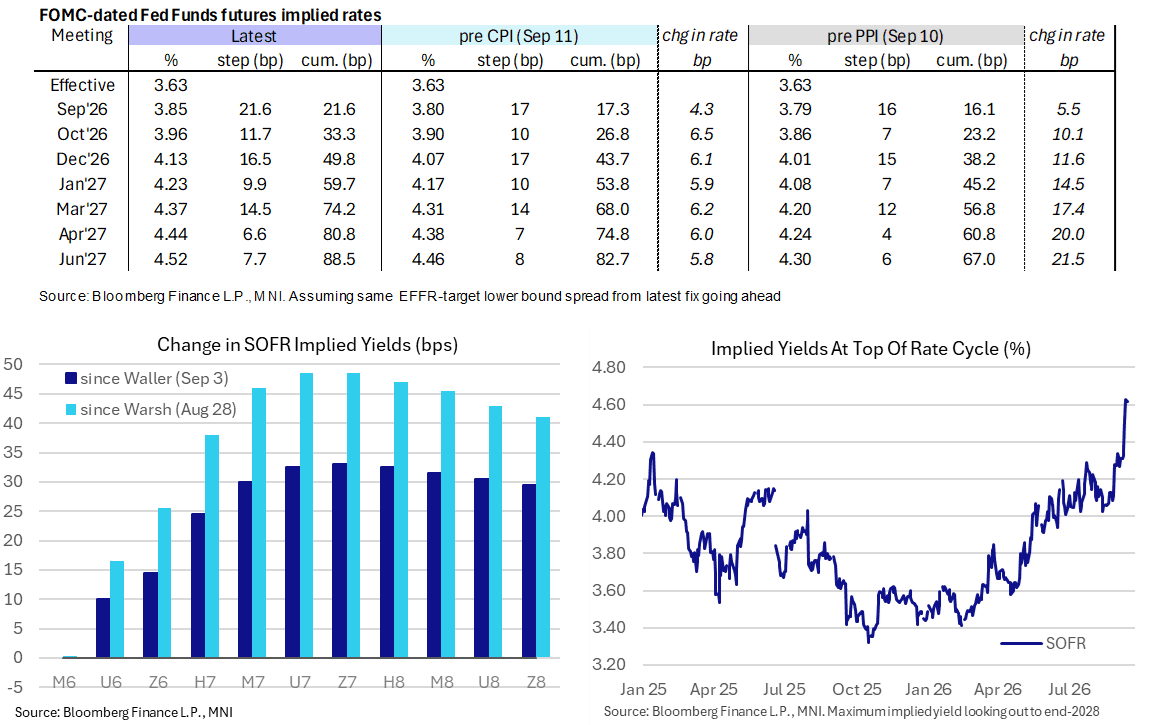
- US rates have faded crude oil futures opening firmly higher following the weekend’s closure of Saudi Arabia’s east-west pipeline, although the former are still near last week’s fresh hawkish extremes.
- Wednesday’s FOMC decision is in focus. See the MNI Preview here including our expectations for the dot plot and economic projections: https://mni.marketnews.com/4hmNZm9 . An analyst summary will follow later today including SEP expectations and their own rate views.
- For a top-level look in the interim, a Reuters poll found that 86 of 101 economists expect the Fed to hike 25bp this week vs 65 of 93 expecting a hold when asked on Sep 9. In addition, 37 of 70 expect the Fed to hike at least twice by end-Mar 2027.
- FF cumulative hikes from 3.63% effective: 21.5bp for Wed, 33.5bp Oct, 50bp Dec, 59.6bp Jan 2027, 74bp Mar, 81bp Apr and 88.5bp Jun.
- SOFR futures are up to 2 ticks firmer on the day looking out to end-2028 contracts, with the peak implied yield at 4.615% (SFRU7) compared to Friday’s close of 4.63% and the snap implied high of 4.675% after CPI.
SEK: Underperforming G10 Alongside NZD: Risk Sentiment The Driver, Not Election
Sep-14 10:05
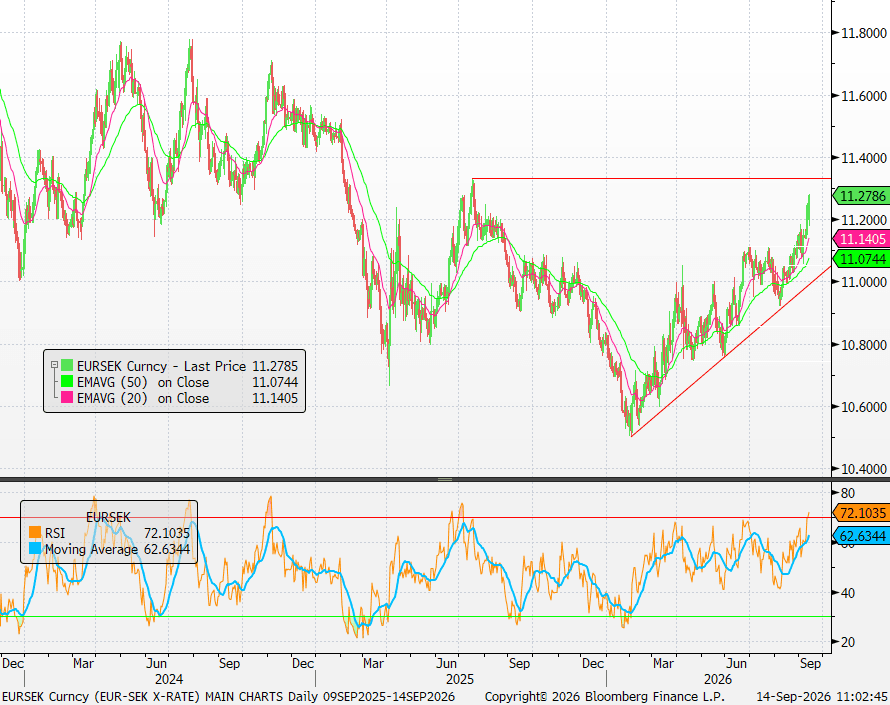
SEK underperforms the G10 basket alongside NZD, with EURSEK up 0.23% after registering a new YTD high of 11.2820 earlier. The primary topside target is the July 2025 high of 11.3320. A bullish technical theme is intact, with pullbacks short of the 20-day EMA at 11.1260 considered corrective.
- Weaker risk sentiment and persistent concerns in the Middle East appear to be driving krona weakness, with the dollar index supported, European equity futures down 1.1%, and energy prices bouncing from Friday’s close.
- Spillover from the inconclusive general election result appears minimal – a protracted period of government formation may generate some uncertainty, but is unlikely to shift the near-term domestic growth/Riksbank outlook meaningfully.
- JP Morgan have downgraded their SEK forecasts materially through mid-2027, pointing to “renewed upside pressure from higher US yields and the global carry trade”. They note that “better domestic growth is insufficient given the global backdrop, leaving SEK vulnerable as a funder”. They see EURSEK at 11.30 in Q4 (vs 10.80 prior) and 11.40 in Q2 2027 (vs 10.90 prior).
- This week’s Swedish calendar includes August labour market data and household consumption. Both will feed into the Riksbank's assessment of the output gap at the September decision. This morning, August CPIF ex-energy and temporary fiscal policies was in line with the Riksbank’s June MPR forecasts at 1.6% Y/Y.
Figure 1: EURSEK SInce 2024
SOFR OPTIONS: SFRH7 96.625 Calls Sold
Sep-14 10:04
SFRH7 96.625 calls 12.5K given at 3.5


