US TSYS: Twist-Flattener After Yesterday's Hiatus, 30bps For Dec
Nov-12 04:28
TYZ6 is dealing at 106-04+, +0-03+ from closing levels in today's Asia-Pacific session, as the marke...
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
AUSSIE BONDS: Richer With US Tsys, Muted Reaction To RBA Minutes
Oct-13 04:27
ACGBs (YM +2.0 & XM +3.5) are richer, with the curve flatter.
- Cash US tsys are 2-5bps richer, with the 10-year leading. The move is consistent with a risk-off tone across Asian equity markets.
- Cash ACGBs are 2-3bps richer with the AU-US 10-year yield differential at +9bps.
- The RBA Minutes of the September Meeting explained the reasoning behind the 25bp hike. There was no indication that it believes it has done enough as it is concerned the degree of restrictiveness may only be "modest". While inflation risks were materialising, it remained concerned regarding upward inflation pressures. The next meeting on 3 November will include revised forecasts.
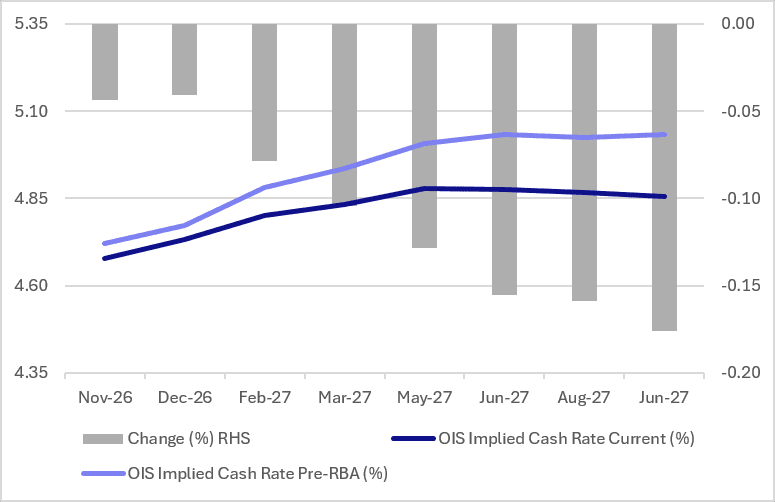
- OIS pricing is 4-17bps softer than pre-RBA decision levels. That said, RBA-dated OIS pricing shows tightening across all meetings, with the probability of a 25bp hike rising from 31% for November to 81% by February 2027 and 109% by June 2027.
- Tomorrow, the local calendar will see the Westpac Leading Index.
- This week, ACGB supply will be in line with the recent average weekly issuance of $2000mn. The AOFM sold A$300mn of the 3.00% 21 March 2047 bond today and plans to sell A$700mn of the 4.25% 21 March 2036 bond today and A$1000mn of the 3.25% 21 April 2029 bond on Friday.
Bloomberg Finance LP / MNI
BONDS: NZGBS: Rallied With US Tsys, Risk-Off Tone
Oct-13 04:15
NZGBs closed 2-4bps richer, with a flatter 2/10 curve.
- Cash US tsys are 2-5bps richer. The move is consistent with a risk-off tone across Asian equity markets.
- Tomorrow, the local calendar will see Net Migration data.
- September food and other monthly price indicators, including rents, petrol and electricity, are due on Friday and should help shape Q3 CPI expectations.
- The data could also influence swap-rate direction, particularly at the 2-year tenor, given the potential implications for OCR terminal-rate expectations.
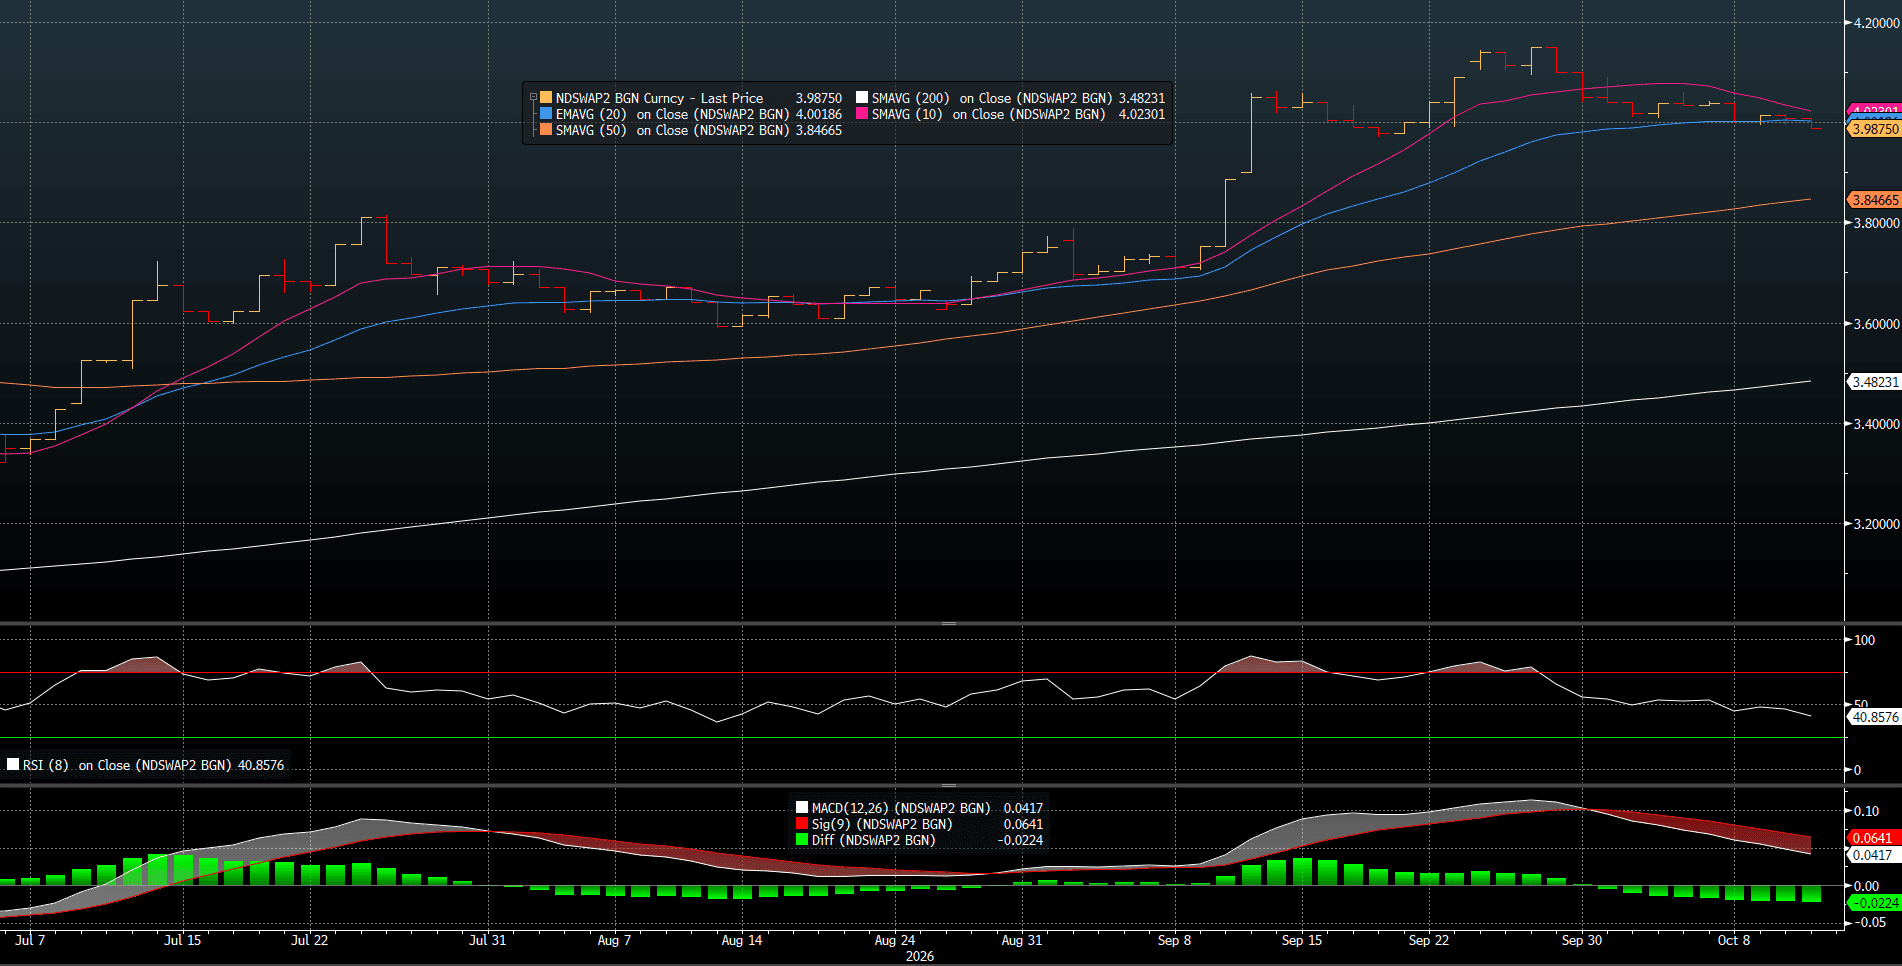
- Swap rates closed 2-4bps lower today, with the 2-year at 3.99%. With the expected OCR peak currently around 3.80%, and 2-year swap rates historically peaking around 50bps above the eventual OCR peak during previous tightening cycles, this framework points to a potential 2-year target of around 4.30%.
- With the 2-year trading near the bottom of its 3.95-4.15% range, which has held over the past month, paying ahead of Friday's price indicators could offer an attractive potential risk/reward opportunity.
- RBNZ-dated OIS pricing is little changed across meetings. 16bps of tightening is priced for October, while February 2027 and August 2027 assign 51bps and 103bps, respectively.
- On Thursday, the NZ Treasury plans to sell NZ$225mn of the 2.00% May-32 bond, NZ$175mn of the 4.25% May-36 bond and NZ$50mn of the 5.00% May-54 bond.
Bloomberg Finance LP
JAPAN: "*TAKAICHI: NOW IS TIME FOR RESPONSIBLE, PROACTIVE FISCAL POLICY
Oct-13 04:14
"*TAKAICHI: NOW IS TIME FOR RESPONSIBLE, PROACTIVE FISCAL POLICY
*JAPANESE PRIME MINISTER SANAE TAKAICHI SPEAKS IN TOKYO" - BBG
(reiterating the well know fiscal backdrop)


