US: "*TRUMP: CONSUMMATED TRADE DEAL WITH PHILIPPINES
"*TRUMP: CONSUMMATED TRADE DEAL WITH PHILIPPINES *TRUMP: WE JUST "CONSUMMATED" A VERY BIG TRADE DEA...
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
BUND TECHS: (Z6) Monitoring Resistance
- RES 4: 123.13 1.000 proj of the Sep 28 - Oct 2 - 8 price swing
- RES 3: 123.00 Round number resistance
- RES 2: 122.47 0.764 proj of the Sep 28 - Oct 2 - 8 price swing
- RES 1: 122.14 High Oct 16
- PRICE: 121.63 @ 05:47 BST Oct 19
- SUP 1: 120.35/119.19 Low Oct 8 / Low Sep 28 and the bear trigger
- SUP 2: 119.00 Round number support
- SUP 3: 118.87 3.236 proj of the Aug 13 - 20 - 25 price swing
- SUP 4: 118.65 3.382 proj of the Aug 13 - 20 - 25 price swing
Bund futures continue to trade closer to their recent highs. Last week’s move higher resulted in a breach of resistance at the 50-day EMA, at 121.61. A second important resistance at 121.97, the Oct 2 high, has been pierced. A clear breach of both price points would undermine the bear theme, and signal scope for a stronger recovery. This would open 122.47, a Fibonacci projection. Initial key support to watch is 120.35, the Sep 28 low.
ASIA STOCKS: MSCI Headwinds; Tech Valuation Concerns; KOSPI Calm;
The Jakarta Composite is down over 5% and near a six-year low. Index provider MSCI's warning that it is consulting on a proposal to downgrade Indonesia from an "Emerging Market" to a "Standalone Market" status would completely remove Indonesian equities from major global benchmarks, triggering massive automated capital flight. Over the weekend, the OJK Chairperson convened an emergency meeting at IDX alongside market participants. The OJK has officially pledged to accelerate capital market reforms—including tougher free-float compliance and tighter disclosure rules—to prove to MSCI that it is actively cleaning up domestic market manipulation.
Elsewhere markets are somewhat calmer with mixed fortunes across the region. The NIKKEI is down -0.60% as a sell-off in U.S. tech carried directly into the Asian session. Investors are growing increasingly anxious over a potential financing crunch and whether the Capex required to build AI infrastructure will yield justifiable near-term returns. Major index heavyweights and chip-related stocks bore the brunt of the damage, with SoftBank Group plunging over -3% and Tokyo Electron sliding over -2%
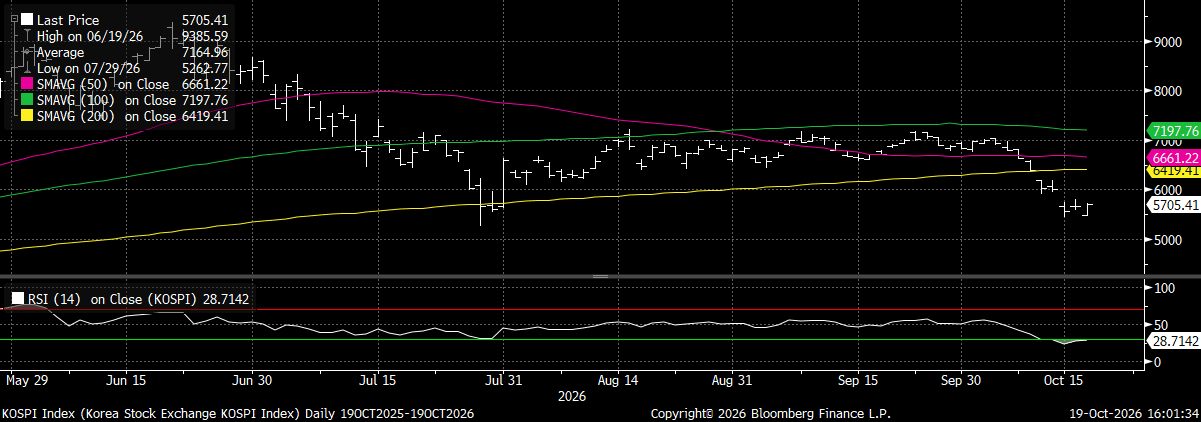
After last week's massive declines, there was calm on the KOSPI with gains of +0.67% - with gains looking largely technically driven. The sell off last week took the index into oversold territory and the gains today see it trying to back away from that.
Chinese bourses are mixed with the Hang Seng closed, the CSI 300 and Shanghai have posted modest gains whilst the tech overhang sees Shenzhen lower by -0.40%. On an individual security level, the biggest decliners in mainland markets included several major electronic and manufacturing caps listed in Shenzhen with Zhongji Innolight down -1.5% whilst Shenzhen Zesum Technology - the technology infrastructure firm - is down -2.50%
Fig 1: KOSPI Remains Oversold on 14-day Relative Strength Index
source: Bloomberg FInance LP / MNI
AUSSIE BONDS: Little Changed After A Subdued Start To The Week
ACGBs (YM +0.5 & XM +0.5) are little changed.
- Cash US tsys have twist-flattened today, with benchmark yields 1bp higher to 2bps lower, after finishing Friday's session with a modest twist-steepening.
- RBA Assistant Governor Christopher Kent delivered remarks in Sydney today. The labour market is loosening faster than the RBA forecast, with Kent noting "there are indicators where the labour market has become less tight a bit faster than we might have forecast." He flagged the key question is whether this reflects weakening demand or rising labour supply.
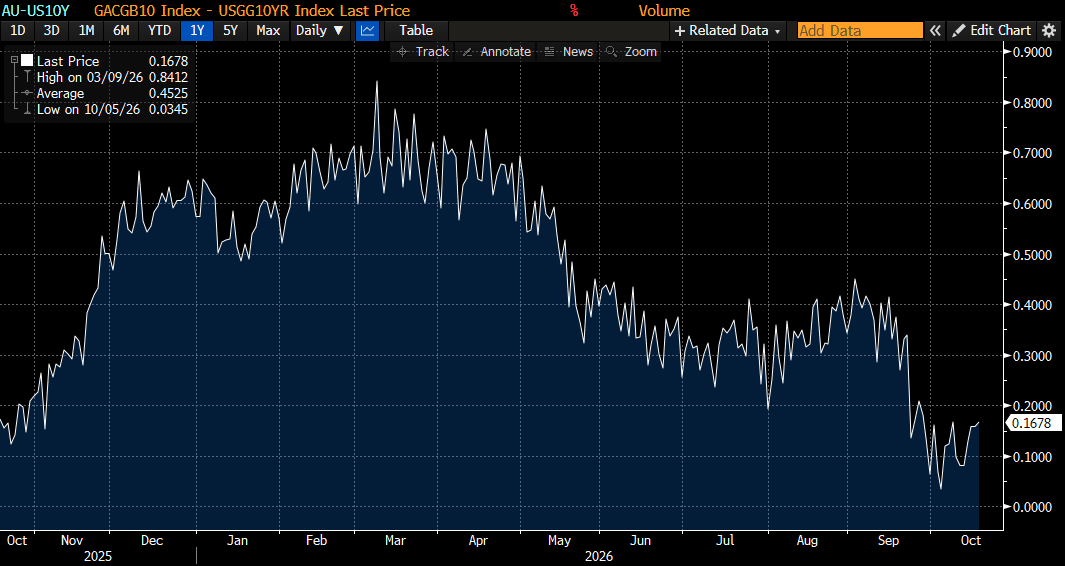
- Cash ACGBs are slightly richer with the AU-US 10-year yield differential at +17bps. The current differential of +17bps sits near the bottom of its 12-month range.
- The bills strip has twist-flattened, with pricing -2 to +1 across contracts.
- RBA-dated OIS pricing shows tightening across all meetings, with the probability of a 25bp hike rising from 27% for November to 78% by February 2027 and 91% by June 2027.
- Tomorrow, the local calendar will be empty.
- This week, ACGB supply will be in line with the recent average weekly issuance of $2000mn. The AOFM plans to sell A$1000mn of the 4.25% 21 October 2036 bond on Wednesday and A$1000mn of the 1.00% 21 November 2031 bond on Friday.
Bloomberg Finance LP


