ASIA STOCKS: Tech Plays Rebound, Japan Banks Hit Post BoJ
Asian equity markets are mostly firmer, post a positive US lead from Thursday (which shrugged off a ...
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
BUND TECHS: (U6) Trades Through Key Support
- RES 4: 125.74 High Jul 10125.68
- RES 3: 125.51 High Aug 5 and a key resistance
- RES 2: 125.20/51 50-day EMA / High Aug 5
- RES 1: 124.75 20-day EMA
- PRICE: 123.91 @ 05:46 BST Aug 19
- SUP 1: 123.60 Low Aug 18
- SUP 2: 123.72 0.764 proj of the Jun 30 - Jul 8 - 10 price swing
- SUP 3: 123.09 1.000 proj of the Jun 30 - Jul 8 - 10 price swing
- SUP 4: 123.00 Round number support
A bear threat in Bund futures remains present and this week’s bearish extension reinforces this theme. The contract continues to trade below the 50-day EMA - currently at 125.20. A clear breach of the EMA is required to signal a possible reversal. Key support and the bear trigger at 124.03, the Jul 23 low, has been breached and support at 123.77, the May 18 low, has been pierced. A continuation would open 123.09 next, a Fibonacci projection.
AUSSIE BONDS: Richer After WPI & RBA Hauser Remarks, Jobs Report Tomorrow
ACGBs (YM +3.0 & XM +5.0) are stronger after WPI data.
- Q2 wages rose 0.8% q/q to be up 3.2% y/y, as expected and in line with Q1 but 0.1pp below the RBA's projection.
- Deputy Governor Hauser participated in a fireside chat in Brisbane and reiterated that if inflation doesn't moderate then rates will need to be increased again. The three main upside inflation risks stem from the impact on input costs and uncertainty from the persistent Middle East conflict, effect of AI investment on demand and prices (eg. chips) and Australia's weak supply/productivity growth.
- RBA thinks that pessimistic consumer confidence isn't feeding into spending due to households having material financial buffers. The RBA is projecting productivity growth of 0.7% in 2026 and 2027 which implies an economic growth speed limit of 2% - anything above that rate would drive inflation higher.
- Cash US tsys are 1-2bps richer in today's Asia-Pac session after yesterday's modest rally.
- Cash ACGBs are 3-5bps richer with the AU-US 10-year yield differential at +36bps.
- RBA-dated OIS pricing shows modest tightening across all meetings, with the probability of a 25bp hike rising from 18% for September to 68% by December 2026.
- Tomorrow, the local calendar will see the July Employment Report.
BONDS: NZGBS: Richer But Slight Underperformance Vs. $-Bloc
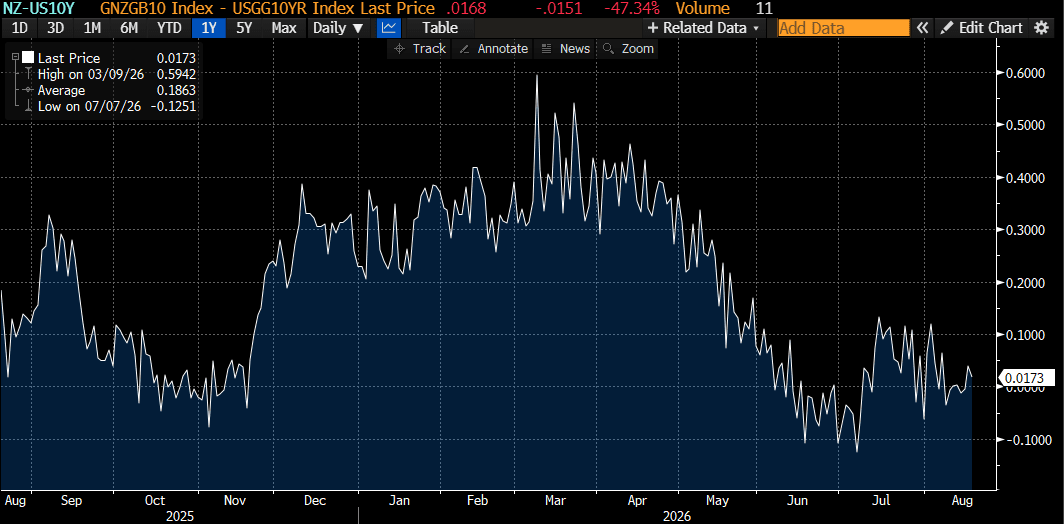
NZGBs closed 4bps richer, with the NZ-US and NZ-AU 10-year yield differentials 1bp higher.
- Cash US tsys are 1-2bps richer in today's Asia-Pac session after yesterday's modest rally.
- NZ producer input prices rose 2.9% q/q in Q2. Increase reflects prices paid for electricity, fuel and raw materials by local producers. – (BBG)
- Swap rates are 2-4bps lower, with the 2-year rate at 3.62%. We have flagged previously that 4.0% looked to be a target given the expected peak OCR. That target is starting to look like a stretch unless the recent paring in the expected peak halts (3.65% to 3.39%).
- RBNZ-dated OIS pricing closed little changed across meetings. 24bps of tightening is priced for September, while February 2027 assigns 64bps.
- Tomorrow, the local calendar will be empty, ahead of Trade balance and Q2 Retail Sales Ex Inflation on Friday.
- On Thursday, the NZ Treasury plans to sell NZ$250mn of the 2.00% May-32 bond, and NZ$200mn of the 4.50% May-35 bond.
Bloomberg Finance LP


