US DATA: Strong Capital Goods Orders Point To Continued Biz Investment Momentum
Sep-25 13:10
September's preliminary durable goods report came in on the strong side in the core metrics, indicat...
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
US DATA: PCE Flat, But Accelerating Services Spending Offsets Goods Pullback
Aug-26 13:09
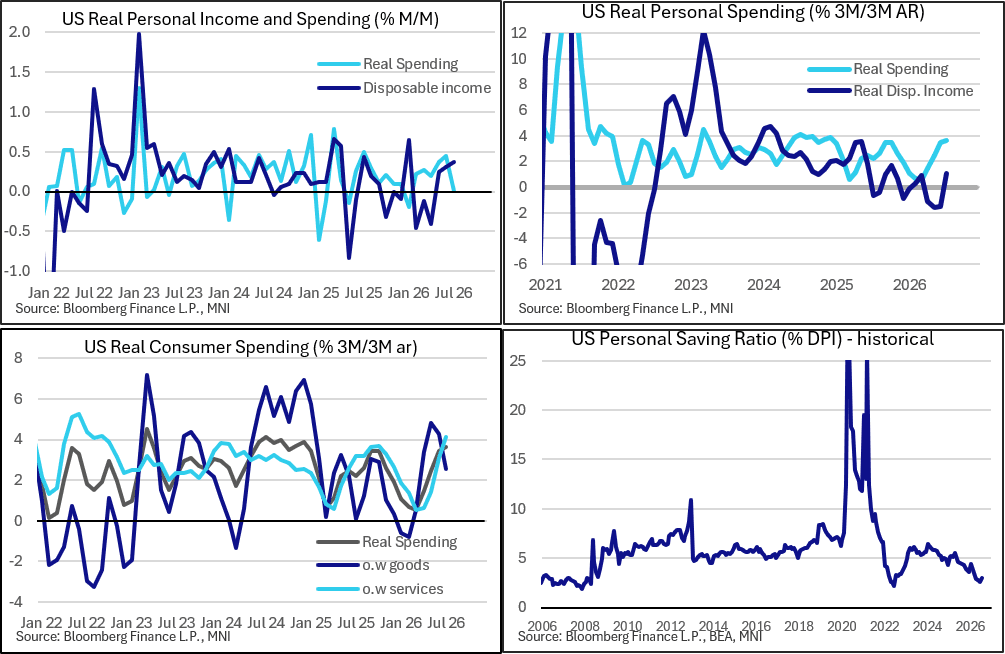
July's Personal Income and Outlays release contained few major surprises in the headline aggregates vs the prevailing consensus, with disposable income improving on steady employee compensation (with an added boost from lower taxes), and a notable pullback in goods consumption more than offset by steady-to-accelerating services spending. There's been a strain on the consumer from the rise in inflation in recent months but underlying spending doesn't appeared to have suffered too greatly.
- Real personal spending came in flat M/M in July (in line with 0% consensus, prior unrevised from +0.4%), the softest performance since January, though the quarterly-equivalent (3M/3M annualized) growth rate actually picked up to 3.6% from 3.4% in June (and thus for Q2 as a whole) on account of the 0.4% M/M readings the two prior months.
- Real goods consumption fell the most in 14 months on an unrounded basis, at -0.6% M/M after very strong readings in 4 of the prior 5 months (as had been telegraphed by the weak retail sales reading for the month), leaving the quarterly growth rate at 2.5% vs 4.3% for Q2 / June. But that's being offset by consistently strong real services purchases: at 0.3% M/M, growth in this spending category was at or above that level for the 4th consecutive month, and is now rising at a 4.1% quarterly clip, the best since September 2022. By way of comparison, real goods spending is up 1.3% Y/Y, but services are up 2.5%, with overall spend up 2.1%.
- Our "discretionary" services spending metric (services Ex Healthcare, Insurance, Utilities) rose for a 6th consecutive month at 0.3%, with the quarterly pace rising 2.6%, fastest since November 2025.
- On the other side of the report, income growth beat expectations, with nominal personal income rising 0.4% M/M (0.2% consensus, prior unrevised from 0.2%). That's largely down to rising employee compensation, which is the lion's share of overall income: it rose 0.3% M/M and hasn't had a down month in the last 46, with the quarterly rate of growth a still-healthy 3.5%.
- Note that this is still only keeping pace with PCE inflation, though consumers' bottom lines have been helped by lower taxes: having shrunk by 0.3% in July and 0.1% in June (the first back-to-back falls since mid-2023), it meant that real disposable income managed to grow by the most since January's tax reductions hit, at +0.4% M/M. On a quarterly basis, real disposable income is now rising 1.0%, the fastest since October 2025 and the first positive reading outright since March.
- There is some caution required here: real disposable income growth continues to lag real spending and is up just 0.5% on a Y/Y basis, and ex-current transfer receipts (from government) it's down 0.4% Y/Y.
- The household savings rate ticked up to a 4-month high 3.0% from a 4-year low 2.6% in June, but we don't take too much signal from this metric on a month-to-month basis given typically large revisions.
STIR: Sticky Premium Anchors SFI M7/M8 Spread
Aug-26 13:06
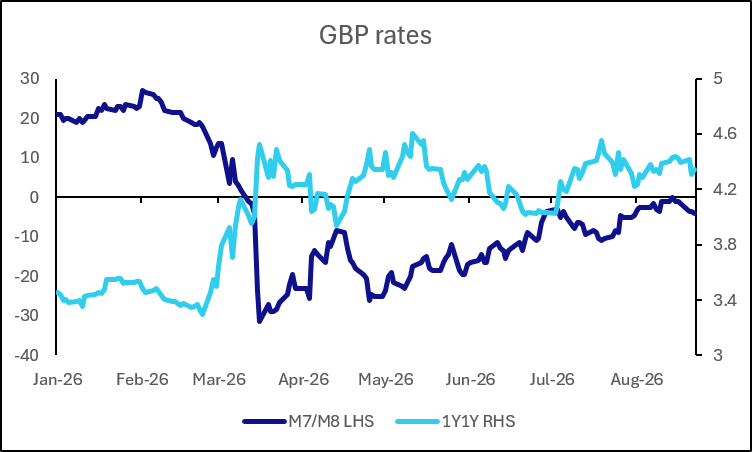
- Having risen from late July levels around -12bp and flirted with parity - as we suggested at the time - the forward red/green M7/M8 SFI spread has edged back into negative territory near -3bp and looks anchored for now.
- Markets still discount just over two additional BOE hikes by next June and, while GBP 1y1y OIS remains elevated ~4.35%, its high gas beta makes it structurally difficult to fade.
- Tighter financial conditions have bought the MPC time to digest the energy shock and imply any additional tightening faces a steep hill to climb. However, as long as geopolitical risks remain unresolved, a residual tightening premium will likely persist, limiting how much further the M7/M8 spread can re-widen from here.
- Domestically, last week’s CPI and labour market data landed broadly in line with consensus. The prints did little to shift expectations around the MPC’s reaction function and are unlikely to trigger a hawkish migration among key swing voters - we have consistently flagged a high bar for a September move.
SOFR OPTIONS: BLOCK: Dec'26 SOFR Ratio Call Spread
Aug-26 13:02
- 5,000 SFRZ6 96.00/96.37 1x3 call spds, 9.25 net ref 96.03 at 0854:13ET
Trending Top

Sep-25 14:32
Sep-25 14:21

