ASIA STOCKS: Sea of Green for Asia's Major Bourses
After two days of significant falls, calm has returned in Jakarta as the new finance minister preaches fiscal discipline whilst setting an aggressive growth target. In Korea, the KOSPI is strong again as the President indicates he is considering removing the proposed tax on capital gains on stocks. The bourses in China continue to power on as news that domestic insurers allocation to equity has hit their highest in 3-years. All major bourses were up today in a strong day across the region.
- The Hang Seng led the way for the China bourses, up +1.19%, the CSI 300 up +0.22%, the Shanghai Comp +0.17% and the Shenzhen Comp +0.15%.
- The NIKKEI bounced back from yesterday's falls and is up +0.71%.
- The TAIEX in Taiwan is up +1.45% for six days of gains as strong portfolio inflows return.
- The KOSPI is the best regional performer today, up +1.60%.
- The Jakarta Composite bounced back and is up +0.95% whilst the FTSE Malay KLCI is up +0.15%.
- The NIFTY 50 is up +0.54% for six consecutive days of gains.
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
STIR: RBA Dated OIS Little Changed Ahead Of Tomorrow’s RBA Decision
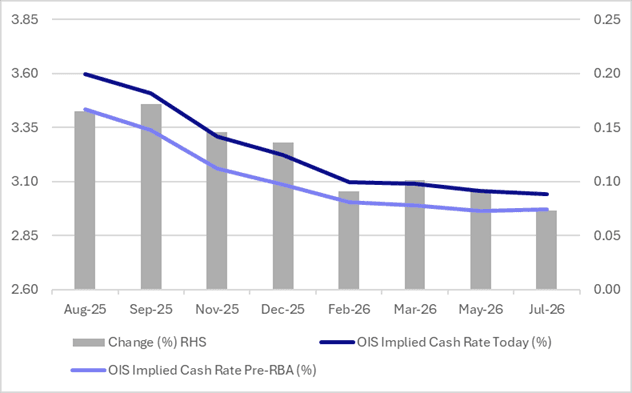
At the time of writing, RBA-dated OIS pricing is little changed on the day across meetings ahead of tomorrow’s RBA Policy Decision.
- A 25bp rate cut this week is given a 97% probability, with a cumulative 62bps of easing priced by year-end (based on an effective cash rate of 3.84%).
- Notably, pricing remains 7-16bps firmer than levels before the July 8 RBA Meeting.
Figure 1: RBA-Dated OIS – Current Vs. Pre-RBA (July)
Source: Bloomberg Finance LP / MNI
BONDS: NZGBS: Subdued Data Light Start To Week
NZGBs closed little changed, with benchmark yields flat t 1bp higher, after a subdued start to the trading week.
- Cash US tsys were closed during today’s Asia-Pac session, with Japan out for a holiday.
- Swap rates closed unchanged.
- With the next RBNZ meeting approaching (August 20), this week contains a number of high frequency releases that the MPC monitors and should give a sense for how the economy began Q3.
- July card spending is out Wednesday and while it is off its lows, growth has remained soft. There could be some payback in the month following the 0.5% m/m rise in June.
- On Friday, July monthly price series are released including food, travel, electricity and rents. Food and power price inflation have been trending higher while petrol and rents have been moderating.
- The July BNZ manufacturing PMI also prints on Friday. It returned to contractionary territory in May after five months signalling growth in the sector. In June, the pace of decline moderated with the index at 48.8 after 47.4.
- RBNZ dated OIS pricing closed unchanged across meetings. 23bps of easing is priced for August, with a cumulative 41bps by November 2025.
- On Thursday, the NZ Treasury plans to sell NZ$200mn of the 3.00% Apr-29 bond and NZ$250mn of the 2.75% Apr-37 bond.
NZD: Asia Wrap - NZD/USD Consolidates On A 0.59 Handle
The NZD/USD had a range of 0.5944 - 0.5962 in the Asia-Pac session, going into the London open trading around 0.5955, -0.02%. Risk has traded a little higher this morning, E-minis +0.20%, NQU5 +0.20%. NZD/USD bounced nicely off its 0.5850 support last week but depending on your view I would suspect sellers could return on any bounce back toward 0.6000/0.6050. For the moment firmly back in the 0.5850-0.6100 range looking for a catalyst to break and give clearer direction, US CPI tomorrow is an important input.
- "NZ'S LUXON: SEEING A TWO-SPEED ECONOMIC RECOVERY IN NZ, LAST THREE MONTHS HAVE BEEN CHALLENGING FOR ECONOMY. EXPECT FUTURE INTEREST RATE CUTS" - BBG
- MNI NZ: July Data Releases Ahead Of August RBNZ Meeting. With the next RBNZ meeting approaching (August 20), this week contains a number of high frequency releases that the MPC monitors and should give a sense for how the economy began Q3. July card spending is out Wednesday and while it is off its lows, growth has remained soft. There could be some payback in the month following the 0.5% m/m rise in June. On Friday, July monthly price series are released including food, travel, electricity and rents. Food and power price inflation have been trending higher while petrol and rents have been moderating.
- Kelly Eckhold(Westpac NZ) on LinkedIn - “Something to keep an eye on is the possibility that the reciprocal tariffs NZ got lumped with last week get removed by the courts. Sounds very possible as Trump is operating beyond his legal authority.”
- Options : Closest significant option expiries for NY cut, based on DTCC data: 0.5920(NZD583m), 0.5930(NZD646m), 0.5960(NZD301m). Upcoming Close Strikes : 0.5825(NZD300m Aug 14). - BBG
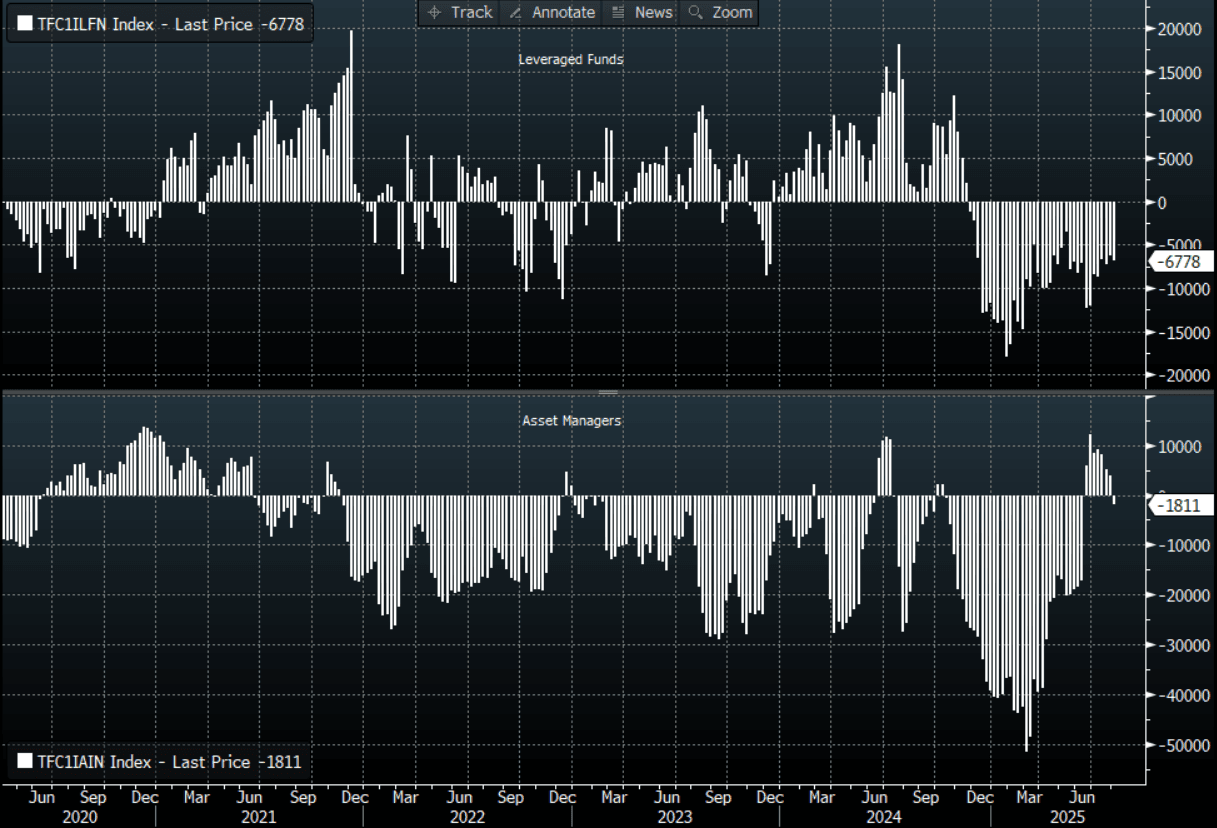
- CFTC Data shows Asset Managers have cut their longs completely and started to rebuild a short in the NZD -1811(Last +3903), the Leveraged community added to their shorts slightly -6778(Last -6250).
- AUD/NZD range for the session has been 1.0929 - 1.0960, currently trading 1.0940. The Cross continues to trade sideways after stalling towards the 1.1000 area once more. The range looks to be 1.0850-1.1000 for now.
Fig 1: NZD CFTC Data
Source: MNI - Market News/Bloomberg Finance L.P


