US STOCKS: S&P - Finds Demand Toward 7600 As NFP Approaches
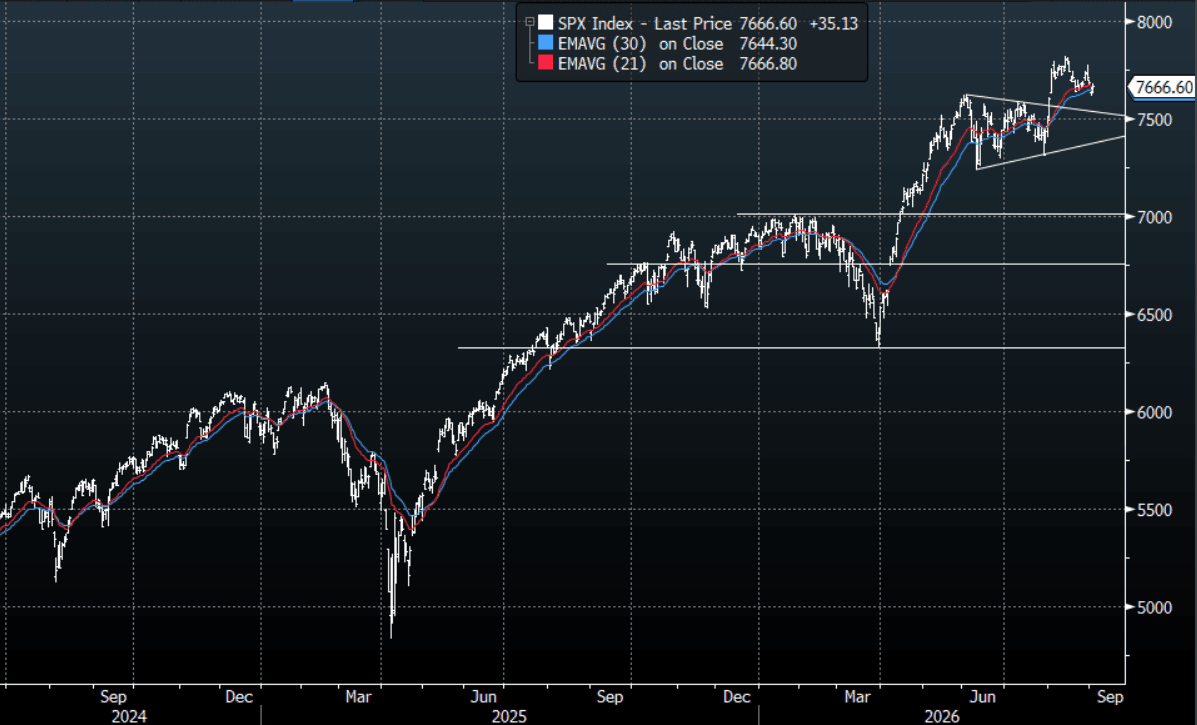
The S&P(ESU6) range overnight was 7618.50 - 7691.25, SPX closed +0.46%, Asia is currently trading around 7675. The market stabilised toward the 7600 area and drifted higher just as risk seemed to be faltering. The explosion higher in Global Bond Yields has started to trigger some concerns and the surge in Oil has just been adding to those headwinds. Overall the stock market is appearing to hold up pretty well considering these moves though there are now some clear red flags appearing. The NFP print later this week could also be an important input as the market wrestles with whether Warsh will be able to hike rates or not. While the S&P(SPX) holds above 7250-7300 the bulls remain in control though it continues to show signs of potentially reverting back toward the mean. On the day, the price looks like 7600-7750 should capture it for now as we look toward NFP and then August CPI for any clues it can provide toward a potential US hike.
- MoneyShow on X: “David Rosenberg argues that investors are getting a distorted picture of the U.S. economy by focusing almost entirely on the AI boom. While AI has become a major driver of market optimism, Rosenberg points out that it represents only a small portion (7%) of overall GDP. Meanwhile, areas like housing, commercial construction, and the broader consumer economy are showing signs of strain.”
- Neil Sethi on X: “Tell me what August CPI is. For a Fed that doesn’t rely on any one report it seems like it all comes down to that one report.”
- EndGame Macro on X: “This is a labor market showing classic late cycle deterioration. Hiring is slowing before layoffs explode. Breadth is narrowing. Smaller employers are barely contributing. Economically sensitive industries are contracting while health care, leisure and very large employers keep the aggregate number above zero. The headline is +38,000. The structure underneath it is considerably weaker, and against the broader consumer, credit, CRE and bankruptcy backdrop, the margin for error is getting very small.”
- Guy Berger on X: “My preview of the August jobs report - the tiny labor market recovery of 2026 has petered out. So far, it's a slowing or stall, not a backslide. For Friday, the most likely outcome: double digit employment gains & a slight unemployment increase.” https://x.com/EconBerger/status/2095277506102444416?s=20
- The S&P 500 Index Average True Range(ATR) for the last 10 Trading days: 57 Points
Fig 1: S&P 500(SPX) Index Daily Chart
Source: MNI - Market News/Bloomberg Finance L.P
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
CNH: USD/CNH - Fails To Extend Below 6.7500, Back To Familiar Range
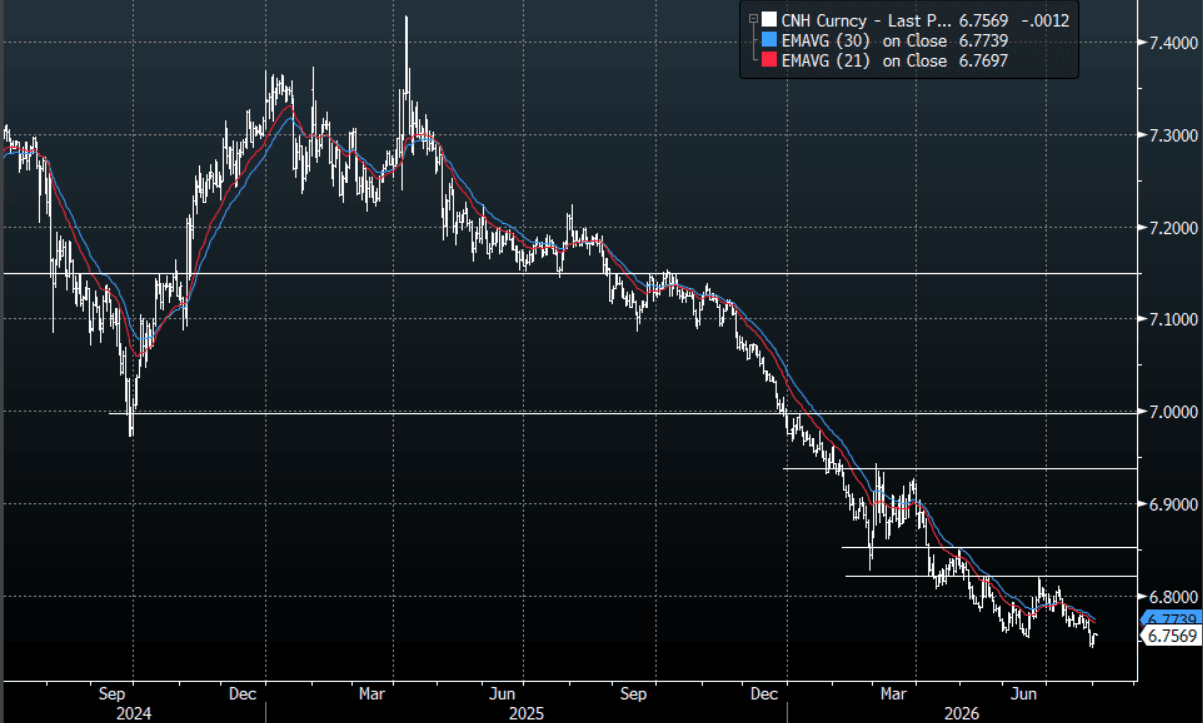
The USD/CNH overnight range was 6.7502 - 6.7593, Asia is currently trading around 6.7565. The pair found some demand below 6.7500 and failed to expand below there after making new lows for the year. The PBOC pushing back against the CNY strength would have contributed. The Yuan continues to outperform and the US Dollar pullback from the USD/JPY intervention just adds to its tailwinds. The price is back within its recent 6.7500-6.8200 range and it looks like we might have to do some work before it extends. The market remains firmly bullish overall on the Yuan but a sustained break below 6.7500 is needed to see the move lower regain its momentum targeting the 6.6700-6.7000 area.
- Bloomberg - “China’s growing trade surplus has revived an old debate: Should Beijing simply let the yuan appreciate? Two camps agree on the diagnosis but disagree on the cure.” https://blinks.bloomberg.com/news/stories/TJ7JL5T96OSN
- Brad Setser: “The World Should Not Ignore China’s Undervalued Currency” https://www.cfr.org/articles/the-world-should-not-ignore-chinas-obviously-undervalued-currency
- USD/CNY Options : Closest significant option expiries for NY cut, based on DTCC data: none. Upcoming Close Strikes : 6.7840($1b Aug 6) - BBG
- The USD/CNH Average True Range for the last 10 Trading days: 109 Points
Fig 1 : USD/CNH Spot Daily Chart
Source: MNI - Market News/Bloomberg Finance L.P
NEW ZEALAND: Q2 Jobs Data Likely To Show Ongoing Excess Capacity
Q2 labour market data including wages are published Wednesday. Q2 filled jobs and Bloomberg consensus suggest that employment may record the fourth consecutive quarter of growth but it’s still likely to be muted with only a 0.1% q/q increase expected bringing the annual rate up to 0.7% from 0.4%. The unemployment rate is forecast to rise 0.1pp to 5.4%. This is consistent with ongoing excess capacity in NZ which is helping to limit firms’ pricing power and workers’ wage demands, which could allow the RBNZ not to hike at every meeting, especially if Q2 disappoints expectations.
- There are a range of forecasts for employment including amongst the domestic banks. Both ASB and BNZ expect a higher than consensus 0.2% q/q rise but BNZ is forecasting 0.8% y/y while ASB believes it will rise to 1.0% y/y. ANZ is below consensus projecting a flat quarter & 0.6% y/y and Kiwibank expects jobs to fall 0.1% q/q with the annual rate only 0.5%.
- The first indication for Q3 will be July filled jobs on 28 August.
- Unemployment rate forecasts range from 5.3% to 5.5%. Kiwibank believes it will be steady at Q1’s 5.3%, while BNZ & Westpac forecast it to rise 0.1pp to 5.4% (in line with Bloomberg consensus) and ASB & ANZ expect it to be higher at 5.5% driven by supply of labour outpacing demand.
- The participation rate is projected to hold at 70.4%.
- Q2 private wage growth is forecast to rise 0.6% q/q up from Q1’s 0.5%, capped by ongoing excess labour supply. Forecasts range from 0.5% to 0.7% q/q.
JGBS: Futures Stronger Overnight With US Tsys on ME Optimism
In post-Tokyo trade, JGB futures closed stronger, +15 compared to settlement levels, after US tsys finished 5-6bps richer after extending yield lows ahead of the NY open amid brief optimism an agreement over Hormuz Strait passage could be near.
- Oil prices are off their Monday lows but still down sharply after the US paused planned strikes on Iran to allow negotiations to take place.
- "The BOJ may skip a rate hike in September after the action, SocGen strategists said." - BBG
- “Japan's LDP is set to push ahead with plans to suspend the sales tax on food items, despite opposition from a former PM and other officials over how the tax cut would be funded." – BBG
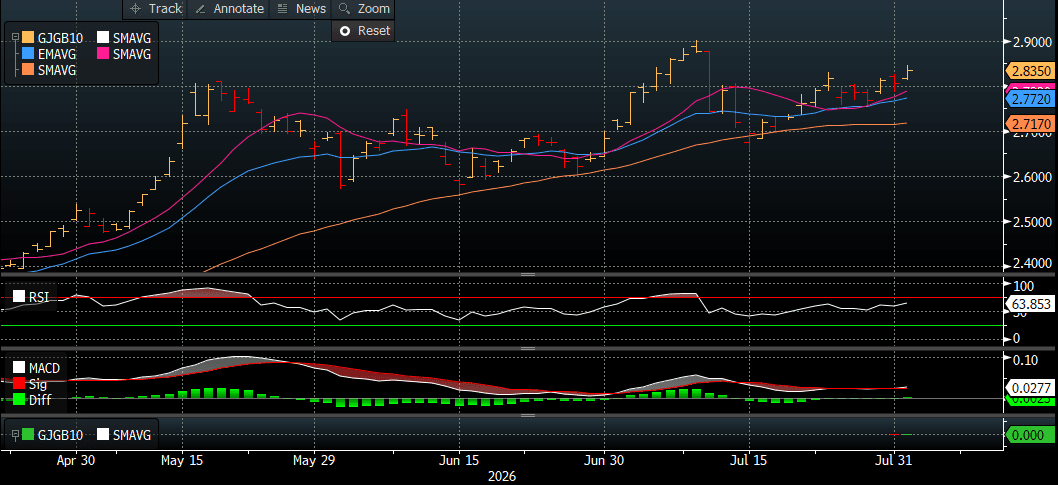
- (Bloomberg) “Tuesday’s 10-year JGB auction is unlikely to excite investors, with the tenor sitting outside the sweet spot for curve-flattening trades and yields sitting below the 3% area. Moves in the JGB curve since the GPIF appointed three firms in May to trade Japanese government bonds on its behalf suggest the focus is firmly on the super-long end. That offers little support for today’s 10-year sale, especially after July’s tepid demand and with yields only about 10bps higher since then.”
- Today, the local calendar will see Monetary Base data alongside 10-year supply.
Bloomberg Finance LP


