US STOCKS: S&P - Drifts Lower As Oil & Yields Push Higher
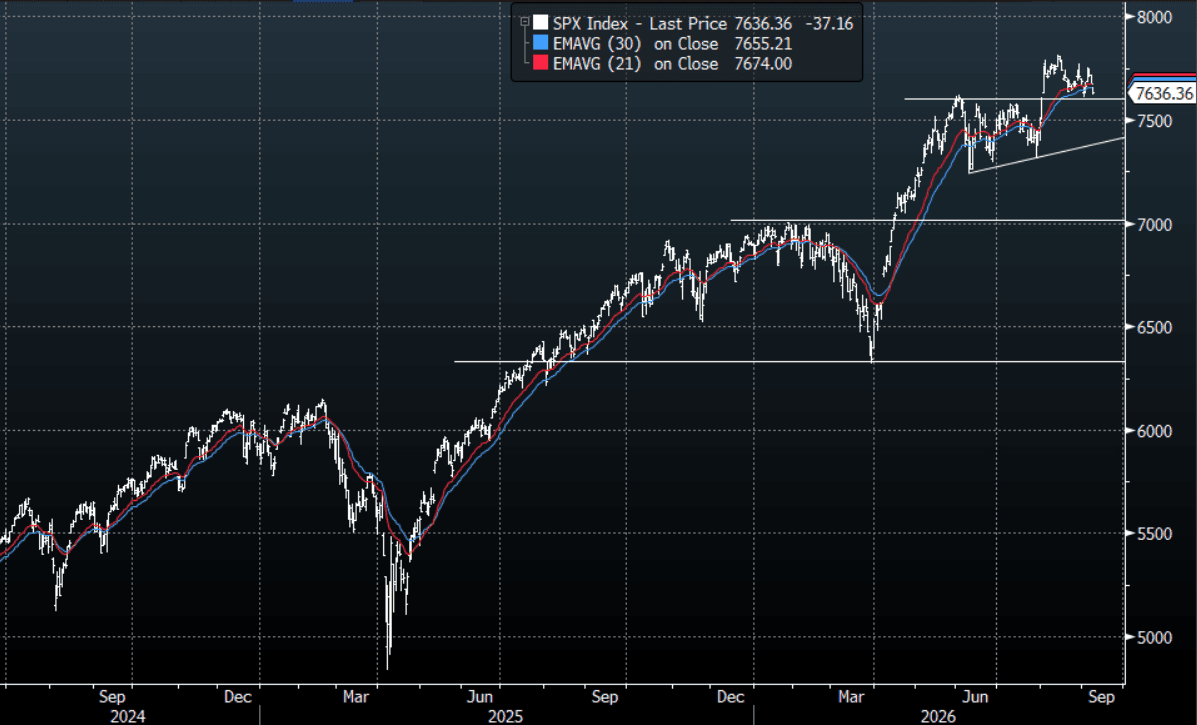
The S&P(ESU6) range overnight was 7628.75 - 7691.00, SPX closed -0.48%, Asia is currently trading around 7653, +0.12%. Oil continues to surge higher as the flare-up in the Middle-East is at risk of expanding. Risk seems to be reluctantly drifting lower but the move seems underwhelming considering Oil is again flirting with $100 and US yields spiked after being disappointed with the buyback. It seems the market has become immune as Middle-East fatigue sets in. I suspect this changes when and if the data turns. A strong NFP print saw Equities top out and drift lower but after Waller's dovish tilt last week the US inflation data coming up will be pivotal as the market wrestles with whether Warsh will be able to hike rates or not. While the S&P(SPX) holds above 7250-7300 the bulls remain in control and they are attempting to build a base from which to reassert its uptrend. On the day, the price looks like 7600-7800 should capture it for now as we look toward the August CPI for any clues it can provide toward a potential US hike. The more a potential hike gets walked back the more the Stock market should like it. The market needs a catalyst, an inline reading on inflation and we could continue to chop sideways unfortunately.
- Robin Brooks on X: “Today is a bad day for global bond markets. The problem with trying to artificially cap long-term yields - as with Treasury buybacks - is that yields jump if markets think buybacks are too small. This tells you the underlying upward pressure is intense…”
- Andy Constan on X: “Since announcement the annualized 132BN buying of long duration treasuries by the Bessent Treasury is roughly the equivalent of a 25bp rate cut. What say you Fed?”
- The S&P 500 Index Average True Range(ATR) for the last 10 Trading days: 56 Points
Fig 1: S&P 500(SPX) Index Daily Chart
Source: MNI - Market News/Bloomberg Finance L.P
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
US STOCKS: S&P - Stalls Toward 7800 As Oil Spikes
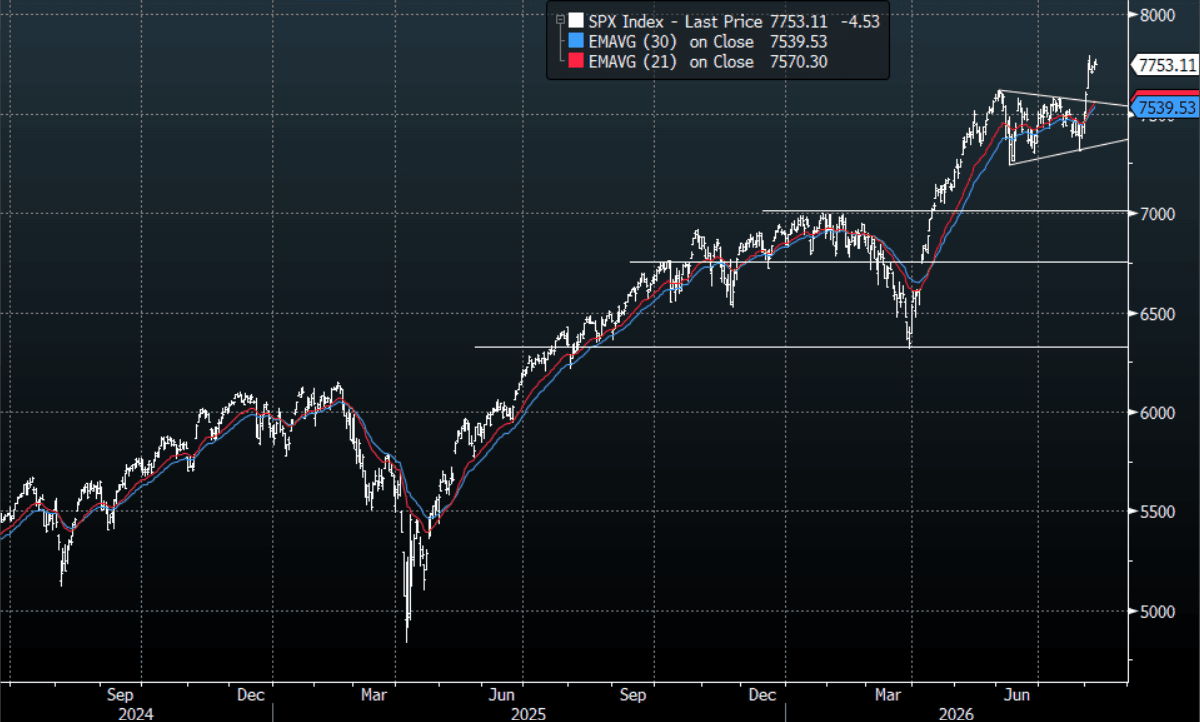
The S&P(ESU6) range overnight was 7764.50 - 7798.00, SPX closed -0.06%, Asia is currently trading around 7775. The market stalled toward the 7800 area and drifted lower as Oil spiked amid some realisation that the Strait is still not open and might not be anytime soon. The reaction in Stocks and FX in particular has been muted, perhaps its just exhaustion from being chopped up and the willingness to express any bearish views has been beaten out of them. The debacle in the Middle-East though continues to be drawn out, how Trump spins this as a win is anyone's guess. Oil is breaking higher(+5.05%) squeezing a short market but the market continues to punish the Equity bears so until the data starts to turn lower I suspect the market will continue to position for the trend to remain higher. While the market continues to hold above 7250-7300 on the SPX the bulls remain in control and the price action looks extremely constructive. Though having moved almost 7% in just a few days I would not be surprised to see a period of consolidation and perhaps even a reversion back to the mean. On the day, the first support is now back toward 7670-7700 and then the 7550-7600 area in the ESU6 contract.
- Kurt S. Altrichter on X: “The Fed aims at one inflation number, and that number just turned into the problem. Core PCE, the gauge the Fed built its 2% target around, spent years reading cooler than every other inflation measure. Pimco shows it has now flipped to read the hottest of them all. So the Fed is steering by the one dial running highest, which sets up a hawkish mistake, and the new chair is already floating a change to how inflation gets measured. When the umpire starts arguing about the strike zone mid-game, quit trusting the called strikes and watch what crosses the plate: your cost of living.”
- MNI US CPI Preview: July Rebound Could Test Fed Patience. Download Full Report Here
- Heading into the July CPI report, MNI’s median of sixteen unrounded analyst estimates is for 0.12% M/M headline inflation (after -0.42% in June) and 0.21% core (after -0.02%). Both headline and core are seen easing a tenth in Y/Y terms to 3.4% and 2.5% respectively, with some risk of core rounding lower.
- For Fed officials who have downplayed the importance of any single month of data, July will still be an important guidepost on inflation trends after June’s surprisingly strong pullback, which included the lowest % M/M headline CPI since April 2020 with core seeing its first negative print since May 2020.
- The S&P 500 Index Average True Range(ATR) for the last 10 Trading days: 77 Points
Fig 1: S&P 500(SPX) Index Daily Chart
Source: MNI - Market News/Bloomberg Finance L.P
NATGAS: European Prices Exceed EUR60 As Storage Levels Remain Very Low
European gas prices soared on Monday as Iranian and US conditions make an imminent reopening of the Strait of Hormuz seem some way off. These demands are likely to take time to work through and find a compromise, if one can be found, with a time frame possibly beyond the start of the heating season. The needed increase in global energy supplies the free movement of vessels through the Gulf would bring seems elusive for now.
- Dutch TTF rose 11.3% breaking above EUR 60 to EUR 61.83, the highest since 24 July. It is now up 4.7% in August adding to the costs of refilling ahead of winter, which is likely to hurt the European economy. Storage is only 59.1% full, over 10pp below the same time last year and 17pp below the 5-year seasonal average.
- Europe remains very vulnerable to other supply disruptions and there have been ongoing supply reductions at Norway’s Ormen Lange field, according to Bloomberg.
- Iran said it won’t reopen the Strait even with an agreement with Oman unless the US ceases its threats, pays reparations and ends sanctions as well as all attacks on its militias cease.
- In response, US President Trump demanded compensation for those killed and hurt by Iran’s conflicts. He now seems prepared to allow economic difficulties in Iran to intensify rather than force a compromise militarily.
- US gas rose 4.4% to $2.778 on Monday, after a high of $2.806, but is little changed on the month. It continues to be driven by domestic developments with the rally due to forecasts for warmer weather and thus higher expected cooling demand.
- There is also higher demand for gas for LNG exports as seasonal maintenance finishes reducing domestically available supplies. Inventories remain above average levels though and supply from new West Texas pipelines is expected before year end, according to Bloomberg.
JGBS: Futures Weaker Overnight As US Yields & Oil; Push Higher
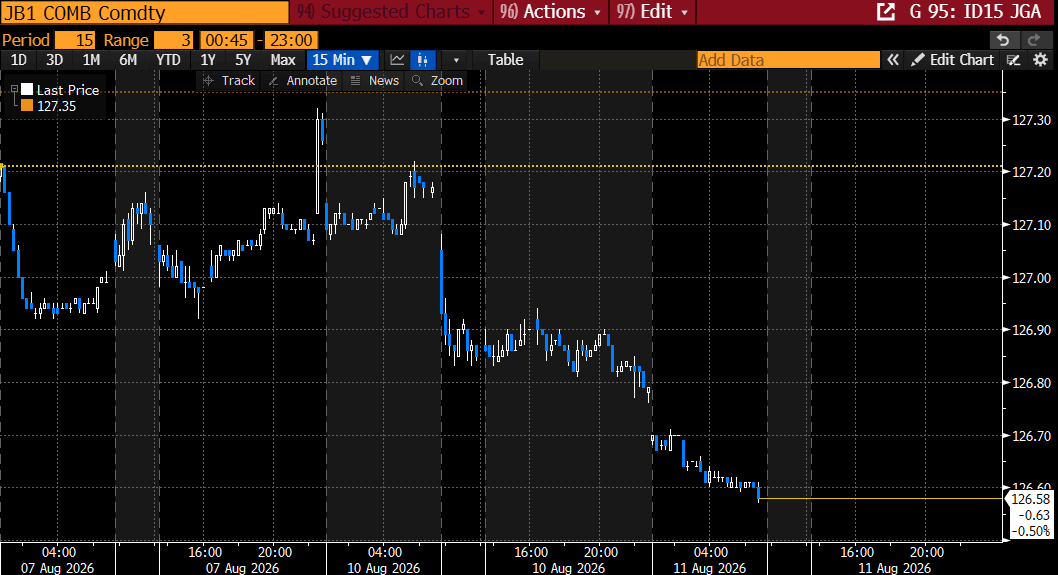
In post-Tokyo trade, JGB futures closed weaker, -32 compared to settlement levels, after US tsys finished near late session cheaps on Monday, benchmark yields 5-6bps higher, as hopes of an imminent US/Iran deal to open the Strait of Hormuz withered.
- Oil was over 5% higher on Monday giving up most of its August gains as the finalisation of an Iran-Oman deal on the Strait of Hormuz remained elusive with both Iran and the US making it conditional on certain demands.
- Iran has said it won't reopen the Strait even with an agreement with Oman unless the US ceases its threats, pays reparations and ends sanctions as well as all attacks on its militias in Lebanon, Iraq, Yemen and Gaza cease.
- (Bloomberg) “BOJ Governor Kazuo Ueda’s strong signal for a September interest rate hike was the decisive factor behind the coordinated intervention in the yen by Japan and the US, Kyodo reports, citing unidentified Japanese government officials.”
- "Spending plans will provide a long-term boost for the currency, Growth Strategy Minister Minoru Kiuchi said. Markets are closed Tuesday." - BBG
- Today, the local calendar will see Money Stock and Machine Tool Orders data alongside 10-year Inflation Linked supply.
Bloomberg Finance LP


