US DATA: Robust Core PPI Inflation In Two-Month Post-Shutdown Update
Jan-14 13:56
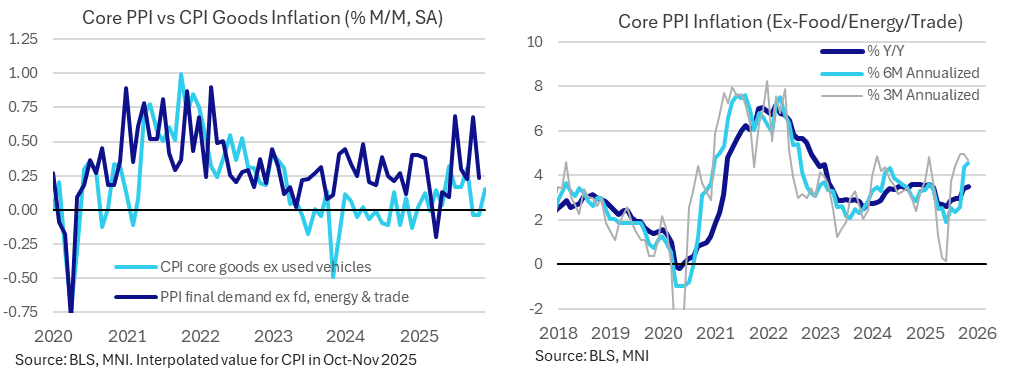
The two-month release for PPI inflation in Oct and Nov saw strong core inflation back in October before returning to more typical monthly rates in November. Recent run rates point to a further acceleration in the Y/Y ahead, with the six-month at its strongest since Aug 2022. The BLS notes a long lag in asking for specific pricing details, especially for the October values, which we guess could increase some volatility, but no material impact on response rates.
- PPI final demand increased 0.25% M/M (cons 0.2) in Nov after 0.12% M/M in Oct and a firmly upward revised 0.59% M/M in Sept (0.31 originally reported).
- As such, October beat expectations at 2.95% Y/Y (cons 2.7), although there is a large difference in the analyst sample with 44 estimates for the M/M vs 19 for the Y/Y.
- Core PPI (PPI ex food, energy & trade services) increased 0.23% M/M (cons 0.2) in Nov after a strong 0.68% M/M in Oct. September was also revised up slightly to 0.23% M/M (0.15% originally reported).
- It saw the core PPI Y/Y far stronger than expected in November at 3.50% Y/Y (cons 2.9) after 3.38% in Oct and 2.96% in the previously published data for September. Core PPI has previously peaked at 3.6% Y/Y in late 2024 and early 2025, and prior to that was last stronger in early 2023.
- Recent run rates are hotter at 4.7%/4.6% annualized on a three- and six-month basis. Tthe three-month rate has at least cooled from two months at 5.0% annualized but the six-month is at its strongest since Aug 2022.
- The volatile imputed trade services category explains some of the relative weakness here in the overall PPI category, at -0.8% M/M in both Nov and Oct.
- The recent strength in core PPI M/M inflation stands out against latest readings for CPI core goods – see charts below.
- BLS on the impact of the federal government shutdown on today's release: “The Federal government shutdown in October and November significantly delayed the transmission of Producer Price Index (PPI) price-update requests. October price-update requests, asking for information as of the October 14 pricing date, were sent to PPI survey respondents on November 19. Price-update requests for November data, asking for information as of the November 11 pricing date, were sent to PPI survey respondents on December 3. The response rates for the October and November data reflected in this release are within the normal range, and no modifications to PPI methodology or procedures were necessary.”
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
US TSY FUTURES: BLOCK: Mar'26 2Y Sale
Dec-15 2025 13:54
- -5,000 TUH6 104-11.62, post time bid at 0845:14ET, DV01 $199,000.
- The 2Y contract trades 104-11.5 last +1.75
GLOBAL POLITICAL RISK: Week Ahead 15-21 December
Dec-15 2025 13:41
Download Full Report Here
(MNI) London – All timings are subject to change.
Monday 15 December
- Ukraine: German Chancellor Friedrich Merz holds a bilateral meeting with Ukrainian President Volodymyr Zelenskyy in Berlin to discuss economic links and the status of the war. In the evening, European heads of government and state, and EU and NATO leaders, will join for a broader conversation regarding the nascent peace plan framework, as well as the 5+ hours of talks between Ukrainian and US delegations over the weekend that are due to continue into the morning. The German government has confirmed the US delegation is invited to attend, but at the time of writing it is unclear if this will be taken up.
US TSYS: Post-Empire Mfg React
Dec-15 2025 13:38
- Treasuries bounce back near late overnight highs after Empire Mfg data came out lower than expected - Mar'26 10Y contract trades 112-13 to -13.5 (+7.5-8), 10Y yield -.0234 at 4.1606%.
- A bearish theme in Treasuries remains intact and short-term gains appear corrective. The rally last Thursday topped out at 112-23, meaning resistance at the 20-day EMA, currently at 112-21, remains intact. A continuation lower would refocus attention on key short-term support at 111-29, the Dec 10 low.
- Clearance of this level would confirm a resumption of the bear leg and signal scope for an extension towards 111-19, a Fibonacci projection.


