US TSY OPTIONS: Recent Nov'26 10Y Put Tree Sale - Net Long Vol
Oct-15 16:17
* -40,000 TYX6 104/104.75/105.5 put trees, 13 net vs. 105-16.5/0.17%...
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
SWITZERLAND: Cross-Country STIR Moves Keep CHF's Funder Narrative In Play
Sep-15 16:13
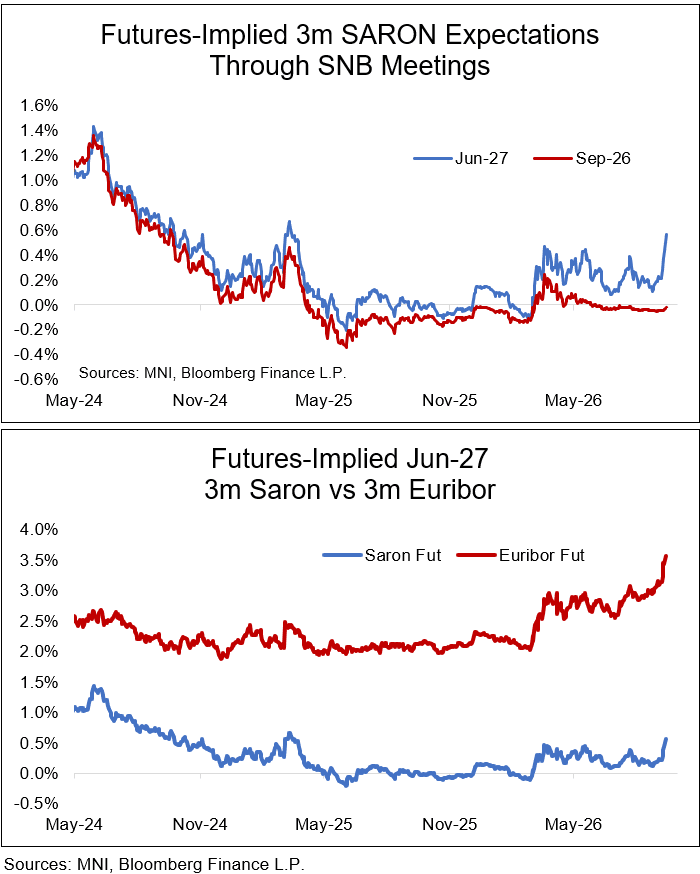
Cross-country STIR moves keep the funder narrative of CHF in play, despite the recent hawkish shift in SARON futures and the upside surprise in August inflation. Indeed, USDCHF today tested 0.8207, the cycle high posted in late July. A break here would put spot at the highest levels since June 2025.
- SNB's Schlegel tilted hawkish and, most importantly, mimicked Tschudin in omitting the phrasing "inflationary pressure virtually unchanged since the last meeting". The slides instead read: "Inflation has risen recently, though in Switzerland it remains within the range of price stability [...] The rise in inflation in Switzerland was primarily driven by petroleum products".
- The comments follow the upward surprise in Swiss August CPI (0.81% Y/Y vs. Exp. 0.5%, 0.35% July), the highest rate since September 2024. As flagged by Schlegel, however, the uptick since February was exclusively driven by energy and fuels (increasing 0.69pp in contribution to Y/Y headline in Aug vs Feb, while headline accelerated 0.68pp over the same timeframe).
- In response, Jun-27 SARON futures yesterday closed at their lowest levels since March 2025, implying a SARON 3m of 0.56% (vs. a policy rate of 0.0%) - a major hawkish shift.
- Despite this higher August print, however, Q3 average inflation to date is still printing roughly 0.1pp below the 0.7% June SNB f'cast for the quarter, and even when considering the hawkish moves in CHF STIR, rate differentials against the Eurozone have widened: The Jun-27 3m EURIBOR / SARON spread crossed 300bps last week, a record high for the Jun-27 expiry.
- An SNB report released yesterday meanwhile highlights that inflation differentials to Switzerland widen in global high-inflation environments. This implies that should higher energy prices persist, the CHF funding narrative remains firmly in play, as the interest rate sensitivity of the SNB remains lower than the one of its peers.
BONDS: EGBs-GILTS CASH CLOSE: Curves Steepen With Intrigue At Both Ends
Sep-15 16:10
European curves steepened Tuesday, though longer-end yields closed off intraday highs.
- Gilts led a pullback in yields from overnight highs after the Telegraph reported that the BoE will halt APF sales on longer dated instruments.
- UK labour market data was mixed though we continue to note this has been de-emphasised somewhat by the MPC recently and indeed on the day BoE-dated OIS was little changed, showing ~7bp of tightening for Thursday's decision announcement.
- After picking up from session lows through mid-afternoon London trade, EGB yields pulled back led by the front-end in response to the MNI Policy Team's latest sources piece, "MNI SOURCES: ECB Likely To Wait Till December Before Next Hike" which saw the implied probability of an October hike quickly pull back ~3bps or so to 13bps.
- On the day the German curve twist steepened, with the UK's bear steepening. We note 10Y Bund yields hit fresh cycle highs (3.573%) before fading slightly; UK 10s remained within the prior session's ranges though posted a fresh post-2007 high close.
- Periphery/semi-core EGB spreads widened modestly.
- UK inflation data will be Wednesday's early highlight (MNI UK CPI and labour market preview here), with the Federal Reserve decision taking centre stage after the European cash close.
Closing Yields / 10-Yr EGB Spreads To Germany
- Germany: The 2-Yr yield is down 0.6bps at 3.257%, 5-Yr is up 1.7bps at 3.351%, 10-Yr is up 2bps at 3.538%, and 30-Yr is up 3.4bps at 3.892%.
- UK: The 2-Yr yield is up 0.2bps at 4.891%, 5-Yr is up 1bps at 4.964%, 10-Yr is up 2.1bps at 5.388%, and 30-Yr is up 3.1bps at 5.925%.
- Italian BTP spread up 1.3bps at 88bps / Spanish up 0.7bps at 47.2bps
SOFR OPTIONS: BLOCK: Nov'26 SOFR Call Buy
Sep-15 16:00
- +8,000 SFRX6 96.25 calls, 1.25 at 1155:48ET, adds to some +30,000 bought earlier


