POWER: German Afternoon Renewable Forecast
Sep-27 2024 14:20
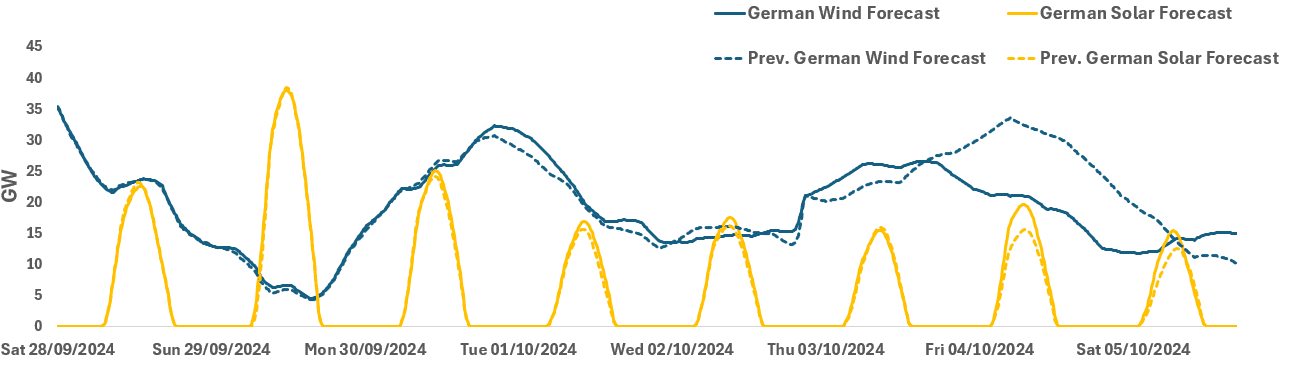
See the latest German renewables forecast for base-load hours for the next seven days from this afternoon, including the midday change. German wind will be the lowest on 2 Oct at a 22% load factor – likely lifting costs to the highest over the weekday.
German: Wind for 28 Sept-5 Oct:
- 28 September:22.89GW (-175MW),
- 29 September: 8.77GW (+216MW),
- 30 September: 23.63GW (-384MW),
- 1 October: 23.35GW (+549MW),
- 2 October: 14.49GW (+372MW),
- 3 October: 24.42GW (unchanged),
- 4 October: 20.61GW (unchanged)
- 5 October: 13.41GW
German: Solar for 28 Sept-5 Oct:
- 28 September: 6.50GW (-157MW),
- 29 September: 10.95GW (unchanged),
- 30 September: 6.95GW (unchanged),
- 1 September: 4.53GW (unchanged),
- 2 October: 4.85GW (unchanged),
- 3 October: 4.11GW (unchanged),
- 4 October: 5.42GW (unchanged),
5 October: 3.81GW
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
SWEDEN: Tomorrow’s Activity Data To Be Eyed For 50bp Rate Cut Potential
Aug-28 2024 14:19
- Tomorrow’s Swedish data will be closely watched for signals of deteriorating economic conditions, seemingly a necessary condition for 50bp Riksbank rate cuts per Monday’s minutes. However, we think only a large downside surprise in both Q2 GDP and the Economic Tendency Indicator would be needed to start tempting the Executive Board away from 25bp cuts at each of the remaining meetings this year.
- Consensus for tomorrow’s Q2 GDP print stands at -0.8% Q/Q, in line with last month’s flash indicator. However, we caution that the flash estimate can sometimes be revised quite heavily. For example, the flash Q1 ’24 estimate of -0.1% Q/Q was revised to 0.7% in the final release.
- The August Economic Tendency Indicator, which provides a more forward-looking view than GDP, will as usual be eyed for an update on sentiment and expected prices/employment metrics across industries.
STIR: SFR call spread
Aug-28 2024 13:56
SFRV4 95.00/94.87ps, bought for 0.25 in 3k.
OPTIONS: Shift in USD Vols Makes This DXY Move Distinct from December's
Aug-28 2024 13:51
- As markets roll into September, the front-end of the G10 FX vol curve is seeing further support as contracts capture potential policy pivots from the Fed, ECB, SNB and BoE.
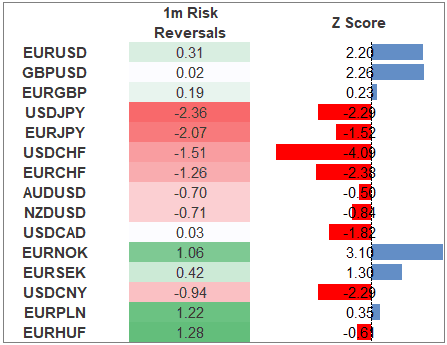
- Vols are further biased against the greenback, with EUR, GBP and JPY 1m risk reversals posting a Z-score north of 2 points in favour of USD puts. This is more extreme in the USD/CHF curve, in which 1m risk reversals cleared 1.5 points in favour of puts today for the first time since the onset of COVID in March 2020.
- This makes the USD weakness this month distinct from the USD-selling phase into end-Dec'23, which proved short-lived and was not accompanied by a significant leg lower in USD call vol.
- Back in December, front-end USD vols remained broadly inline with the rolling average, aiding the ~5% rally in the USD Index and wholly erasing two months of weakness.
Figure 1: G10 FX vols build bias in favour of USD puts over September
- Currency options trade rebounded yesterday after Monday's holiday-thinned trade, with over $100bln notional traded via the DTCC. The USD Index's fresh pullback low of 100.514 will have helped stimulate the decent hedging activity noted against MXN, NZD and ZAR relative to recent averages.
- Through the US open today, markets are somewhat quieter, however hotspots of hedging activity remain in HKD, CHF and KRW.


