NEW ZEALAND: Polls Suggesting Hung Parliament, Opportunity May Decide
With a month to go until NZ's 7 November election the outcome remains highly uncertain with the poll...
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
USD: BBDXY - Poor Price Action After A Strong NFP Print
The BBDXY range Friday night was 1189.32-1193.18, Asia is currently trading around 1189. The US Dollar tried to bounce on the stronger NFP but the move was very quickly reversed. A dovish Waller last week has tipped the broader US Dollar complex over the edge and made the upcoming inflation data this week pivotal. Without that I suspect we might have seen more of a reaction from such a strong payroll print. The so-called “debasement trade” continues to build with Gold and Bitcoin both holding their gains and trading well bid. The price action looks decidedly worrying for the USD. The currency has broken below its pivotal 1195-1200 area and it held comfortably below there at the first time of asking. On the day, I will be watching to see if this move can now gather momentum and build into something more substantial. We might have to wait for the inflation data later in the week before the market truly starts adding to positions, a low print and the USD bears could return en masse.
- MNI US DATA: A Strong Payrolls Report All Around At First Glance Private payrolls were comfortably stronger than expected as they increased a seasonally adjusted 127k (cons 50k) after a two-month upward revision of 37k.
- Robin Brooks on X: “The debasement trade will be the single biggest trade of coming years, driven by giant, out-of-control deficits. This means the Dollar will fall versus EM and gold and other precious metals will keep rising. We're only just getting started on this thing...”
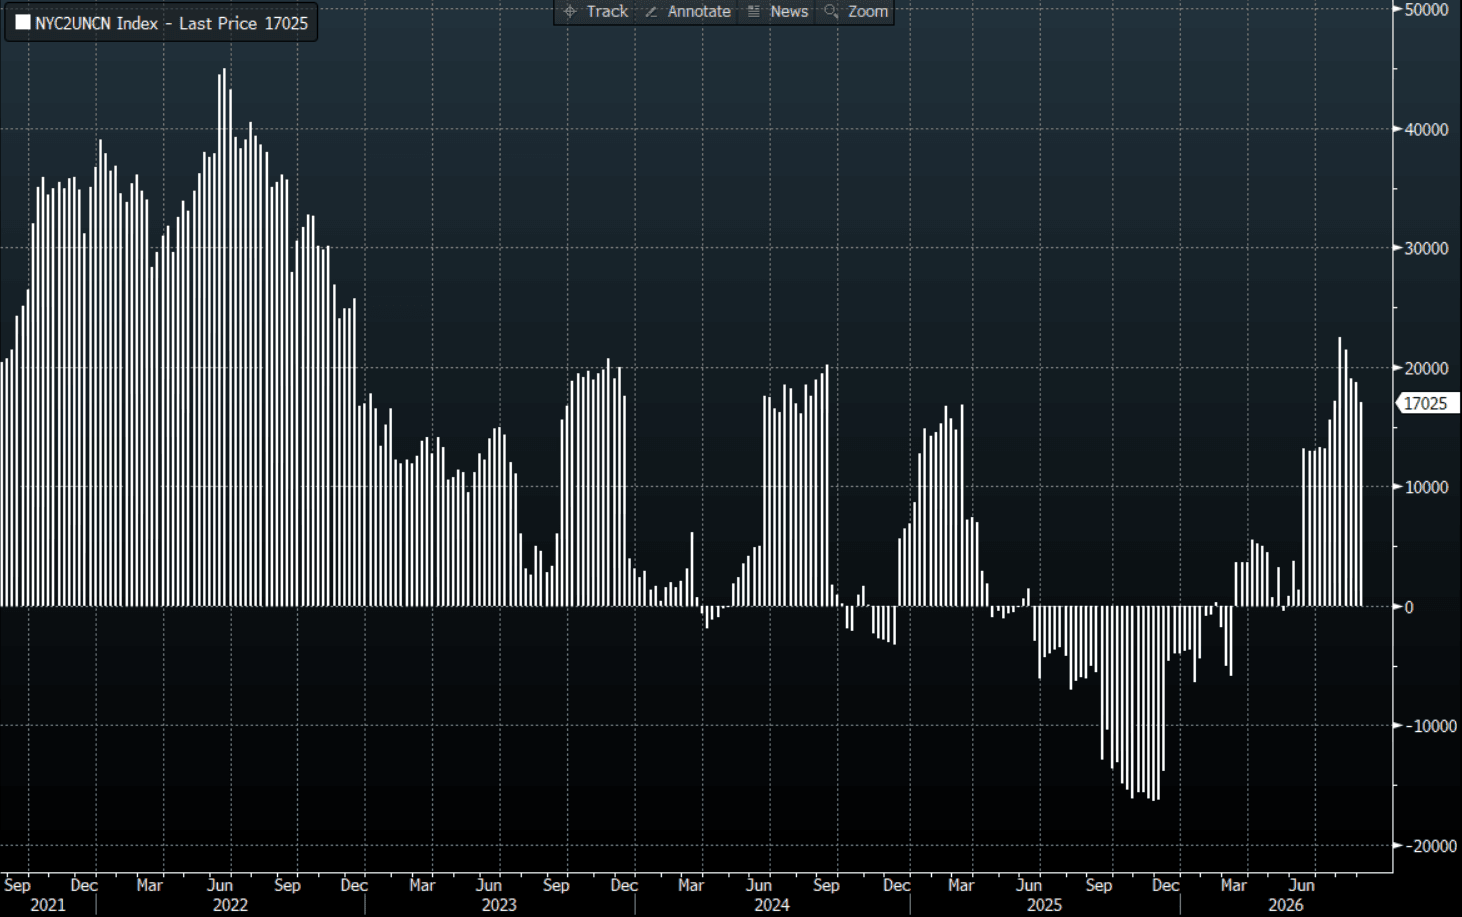
- CFTC Data up to 01/09/2026 shows the market again walking back its core long USD’s, +17 025(Last +18 682).
- The BBDXY Average True Range for the last 10 Trading days: 3.97 Points
Fig 1: USD CFTC Data
Source: MNI - Market News/Bloomberg Finance L.P
US STOCKS: S&P - Strong NFP Sees A Slight Pullback
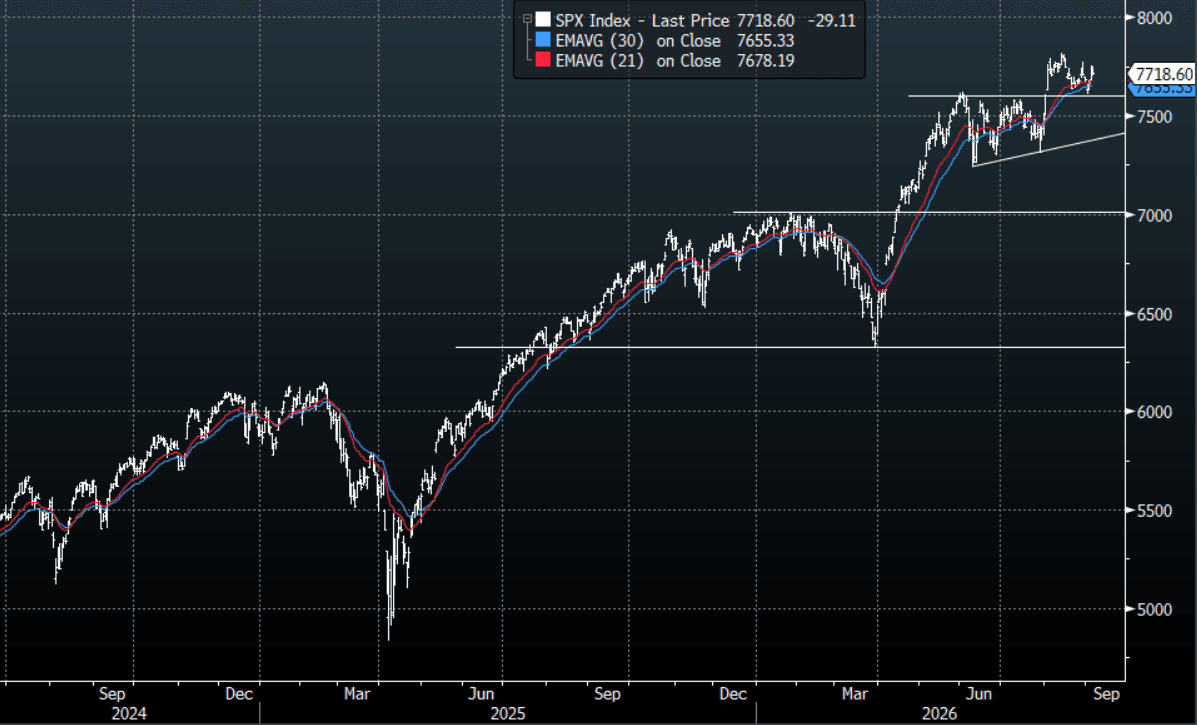
The S&P(ESU6) range overnight was 7711.75 - 7764.00, SPX closed -0.38%, Asia is currently trading around 7720. A strong NFP print saw Equities top out and drift lower but after Waller's dovish tilt last week the CPI coming up will be pivotal as the market wrestles with whether Warsh will be able to hike rates or not. While the S&P(SPX) holds above 7250-7300 the bulls remain in control and they are now looking to reassert its uptrend. On the day, the price looks like 7600-7800 should capture it for now as we look toward the August CPI for any clues it can provide toward a potential US hike. The more a potential hike gets walked back the more the Stock market should like it.
- “The swift deterioration of a loan in Blue Owl’s retail private credit fund to near-zero is bringing to the fore doubts about marks in a $1.8 trillion market.” - BBG https://blinks.bloomberg.com/news/stories/TKQQSHT96OSI
- Kurt S.Altrichter on X: “The Fed just started printing again. After two years of shrinking its balance sheet, the Fed hit the brakes on QT and turned it back up. Total assets bottomed near $6.5 trillion and are rising again. Money is the only thing that moves inflation, so forget the tariff and energy noise. The Fed just restarted the one lever that does, and that liquidity floods back into stocks, gold, and hard assets while the dollar loses ground.”
- Milk Road Crypto on X: “Lyn Alden gives less than 1% odds that the bond market will be able to impose fiscal discipline on Congress. "No point is Congress going to say, 'Oh, the 10-year is over 5%... maybe we should majorly reform Social Security and Medicare.' It's just not going to happen." Nearly 100% of the time, highly indebted governments in their own currency end with financial repression - inflating the debt away.”
- The S&P 500 Index Average True Range(ATR) for the last 10 Trading days: 58 Points
Fig 1: S&P 500(SPX) Index Daily Chart
Source: MNI - Market News/Bloomberg Finance L.P
JGBS: Futures Higher Overnight Friday, US Tsys Weaker On NFP Beat
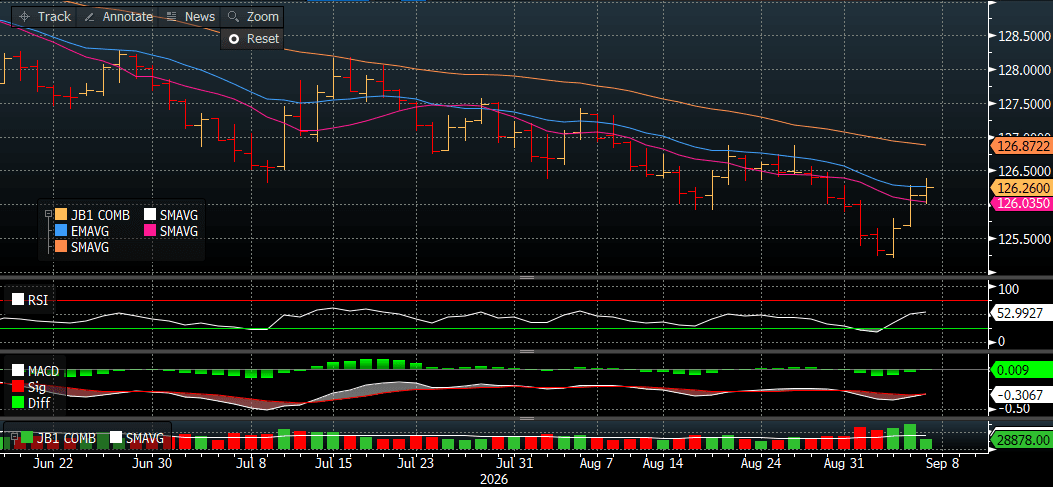
In post-Tokyo trade on Friday, JGB futures closed stronger, +12 compared to settlement levels, despite US tsys finishing weaker, albeit near midrange for the day, as rates gradually pared the initial sell-off on stronger than expected August Jobs gains.
- Nonfarm payrolls increased 162k (cons 55k) with a 55k two-month update revision, with the government adding 35k (bouncing from -50k in Jul) along with a two-month update revision of 18k. Private payrolls were comfortably stronger than expected as they increased a seasonally adjusted 127k (cons 50k) after a two-month upward revision of 37k.
- Fed entered Blackout at midnight on Friday ahead of its policy meeting later this month. CPI and PPI top the bill in the US this week.
- President Donald Trump on Friday demanded the Federal Reserve lower interest rates or else he will cut off trade with countries which the U.S. maintains trade deficits.
- "Japan said progress was being made on a $550 billion investment initiative set up as part of a trade deal with the US last year. "We'll continue working closely," Trade Minister Ryosei Akazawa told reporters in Washington late Friday." – BBG
- Today, the local calendar will see Leading and Coincident Index data.
Bloomberg Finance LP


