OIL: Oil End of Day Summary: Crude Rises
Crude prices are seeing some support from disruption to Tengiz output alongside a weaker dollar today while the market continues to monitor geopolitical developments.
- WTI FEB 26 up 1.5% at 60.32$/bbl
- Reuters reports that Kazakhstan’s Tengiz oil field could be halted for another 7-10 days after shutting down on Sunday.
- Crude appears to be monitoring developments that could alter the market surplus with focus on global supply while a US-EU trade war could reduce global growth and thus energy demand adding to the surplus.
- The IEA publishes its updated report and forecasts on Jan. 21 having previously projected a record surplus in 2026.
- Crude oil stockpiles in key regions in early January were well above year ago levels and the five-year seasonal high with the surplus to 49.6mbbl, BNEF shows.
- The US government plans to allow a wider group of trading companies, to purchase Venezuelan crude: Bloomberg.
- A shift in Venezuelan crude exports from China to the United States could further lift already high oil tanker rates: Fitch.
- The last tankers carrying sanctioned Venezuelan crude to Asia are set to arrive in the coming days, effectively ending China’s access to a source of cheap oil that has helped sustain its refining sector, according to Bloomberg.
- Russia’s oil exports fell to the lowest since August in the four weeks to Jan. 18, Bloomberg reports.
- China's crude oil imports from top supplier Russia fell 0.7% year on year in December while imports from transshipment hub Malaysia and Indonesia fell while UAE supply surged: GACC data.
- Iraq will export a total of 223k b/d of Kirkuk crude in February, up by 21% on the month: Reuters.
- The ports of Zueitina, Brega, Es Sider and Ras Lanuf have temporarily halted operations: Bloomberg.
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
AUSSIE 10-YEAR TECHS: (H6) Marked Lower
- RES 3: 95.982 - 76.4% retracement Sep’24 - Nov’24 downleg
- RES 2: 95.960 - High Apr 7 (cont.)
- RES 1: 95.900 - High Oct 17
- PRICE: 95.160 @ 15:32 GMT Dec 19
- SUP 1: 95.120 - Low Dec 10
- SUP 2: 95.087 - 2.0% Lower Bollinger Band
- SUP 3: 94.276 - 1.0% 10-dma envelope
Aussie 10-yr futures remain well toward the bottom of the recent range, having taken out all major support levels in the process. With 95.275 cleared, prices are pushing to new contract lows, opening vol-band support through 95.087 and into 94.276. Any recoveries need to break back above 95.900 to signal near-term bullish traction.
AUDUSD TECHS: Corrective Phase Still In Play
- RES 4: 0.6759 High Oct 11 ‘24
- RES 3: 0.6723 High Oct 21 ‘24
- RES 2: 0.6707 High Sep 17 and a key resistance
- RES 1: 0.6661/86 High Dec 16 / 10
- PRICE: 0.6608 @ 15:56 GMT Dec 19
- SUP 1: 0.6593 Low Dec 18
- SUP 2: 0.6566 50-day EMA
- SUP 3: 0.6517 Low Nov 27
- SUP 4: 0.6466/21 Low Nov 26 / 21
The trend condition in AUDUSD remains bullish and the latest pullback appears corrective. The move down is allowing a recent overbought condition to unwind. Support at the 20-day EMA, at 0.6598, has been pierced. The 50-day average is at 0.6566. The area between the two averages represents a key short-term support zone. A resumption of gains would refocus attention on key resistance at 0.6707, the Sep 17 high and bull trigger.
LOOK AHEAD: US Macro Week Ahead: Long-Awaited Q3 GDP Plus Labor Updates
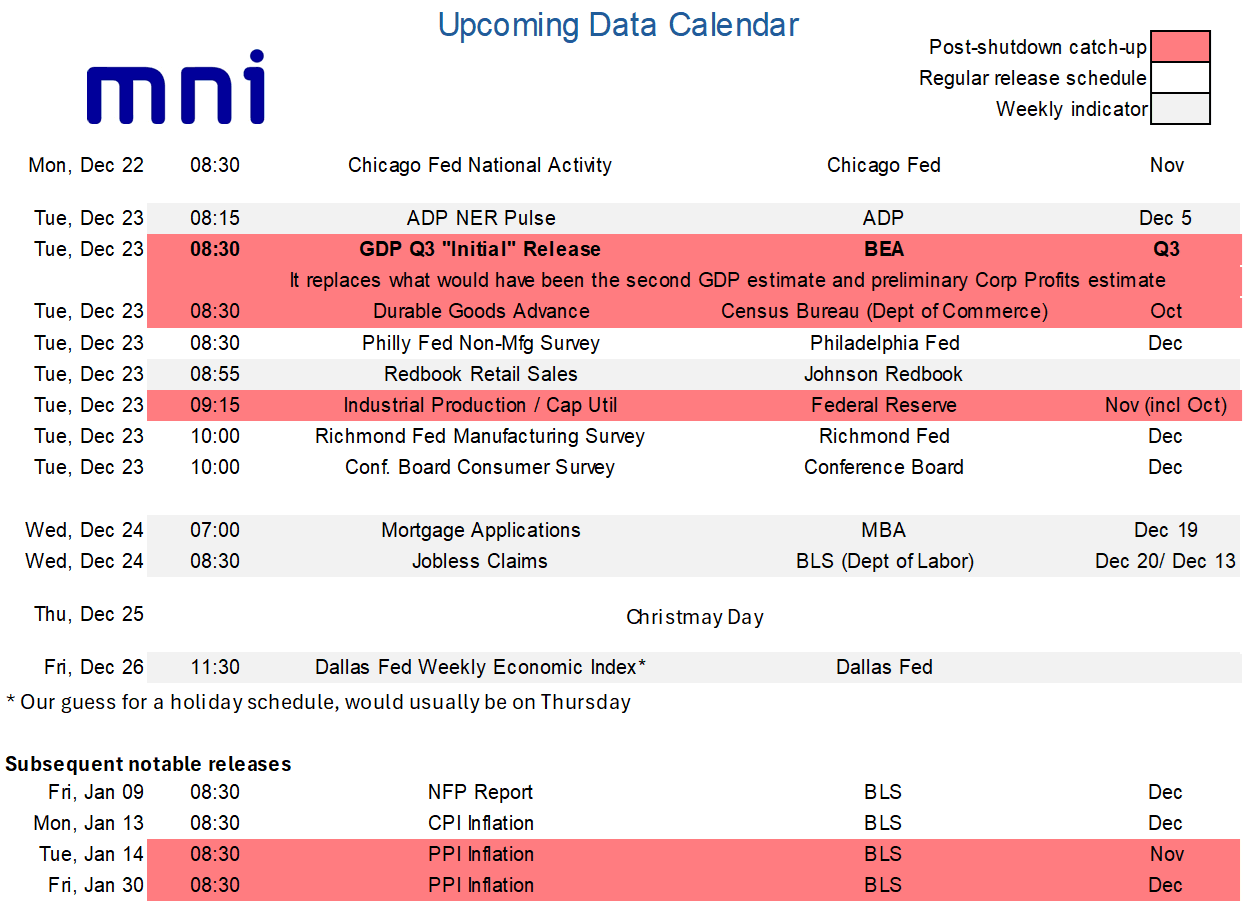
- The week ahead sees a slimmed down data schedule after a particularly busy few weeks, including distorted NFP and CPI reports in the week just gone. There are still some important releases though, with the highlight being the long-awaited “initial” Q3 GDP release on Tuesday.
- This report will replace what would have been the second GDP and the preliminary corporate profits estimates, with the extended tracking window of the Atlanta Fed’s GDPNow pointing to strong real GDP growth of 3.5% annualized after an average 1.6% in 1H25 (-0.65% in Q1 before 3.84% in Q2).
- Expect continued close attention on private demand, best seen by Powell’s preferred PDFP category, which is currently tracking at ~2.4% annualized for similar to the 2.4% averaged in 1H25 (1.9% Q1 before 2.9% in Q2).
- Tuesday also sees updates for the weekly ADP tracker in the four weeks up to Dec 5, getting closer to the reference period for the monthly report, after last week’s further improvement. It’s followed by useful updates for Q4 GDP tracking with durable goods for October and industrial production for both October and November, before the Conference Board consumer survey for December with its closely watched labor differential having stalled at subdued levels but not deteriorated further since September.
- Note as well that Wednesday then sees weekly jobless claims a day early ahead of Christmas Day, with continuing claims capturing the December payrolls reference period. There is currently minimal Fedspeak scheduled and we suspect this will remain the case ahead of Christmas, likely confined to media appearances if any.