BONDS: NZGBS: Richer But Well Off Bests, NZ-US10Y Diff Sharply Higher
NZGBs closed 2-5bps richer but well off session bests. NZGBs were 7-10bps richer earlier in the sess...
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
GLOBAL: President Trump via Social Media
JPY: USD/JPY - Disappointed Market Challenging 157-159
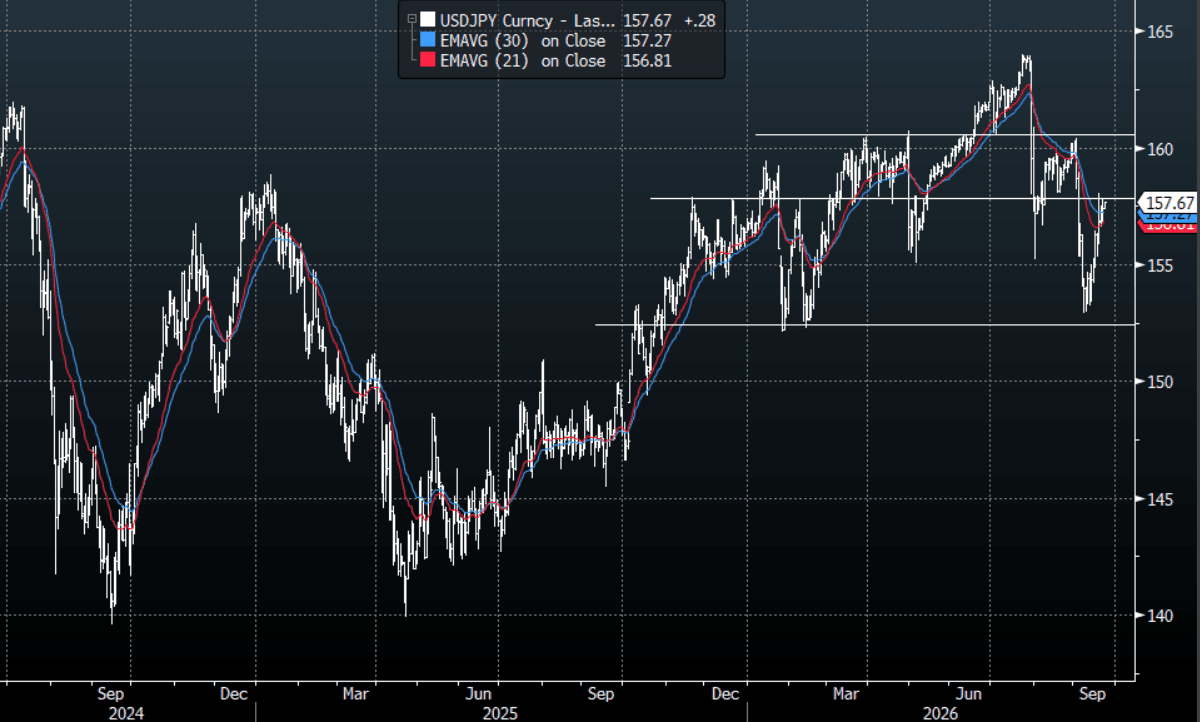
The USD/JPY range today has been 157.34-157.67 in the Asia-Pac session, it is currently trading around 157.65, +0.16%. The pair has stalled toward 158.00 with the market wary of intervention after reports the BOJ might have conducted a rate check around that level on Friday night. All in all though last week was not great for the Yen and those potential green shoots that had just started to take root, CFTC data showed the market turning long for the first time(ouch). A dovish hike thanks to the Takaichi appointments and a BOJ that will not give a signal to the timing of the next hike, while the Fed comes out hawkish is not a recipe to encourage those buyers to add to positions. The 149-152 area has now proved to be solid support again. The market is now punishing those Yen longs and back testing the 157.00-159.00 area which technically looks important now. The BOJ was probably also reminding the market it is around as Japan enjoys a three-day holiday which could further impact liquidity.
- “Sanae Takaichi urged the UN to remove references to Japan and Germany as “enemy states” in her maiden speech at the General Assembly.” - BBG
- “Trump and Takaichi agreed to closely coordinate on issues related to China just days before Xi’s trip to Washington, a Japanese government spokesman said.” - BBG
- Options : Close significant option expiries for NY cut, based on DTCC data: 152.00($733m), 156.00($1.21b), 157.00($1.23b). Upcoming Close Strikes : 155.00($2.01b Sept 25), 156.00($1.94b Sept 24), 157.50($1.52b Sept 24) - BBG.
- The USD/JPY Average True Range(ATR) for the last 10 Trading days: 110 Points
Fig 1 : USD/JPY Spot Daily Chart
Source: MNI - Market News/Bloomberg Finance L.P
AUD: AUD/USD - Trades Heavy Toward 0.7100
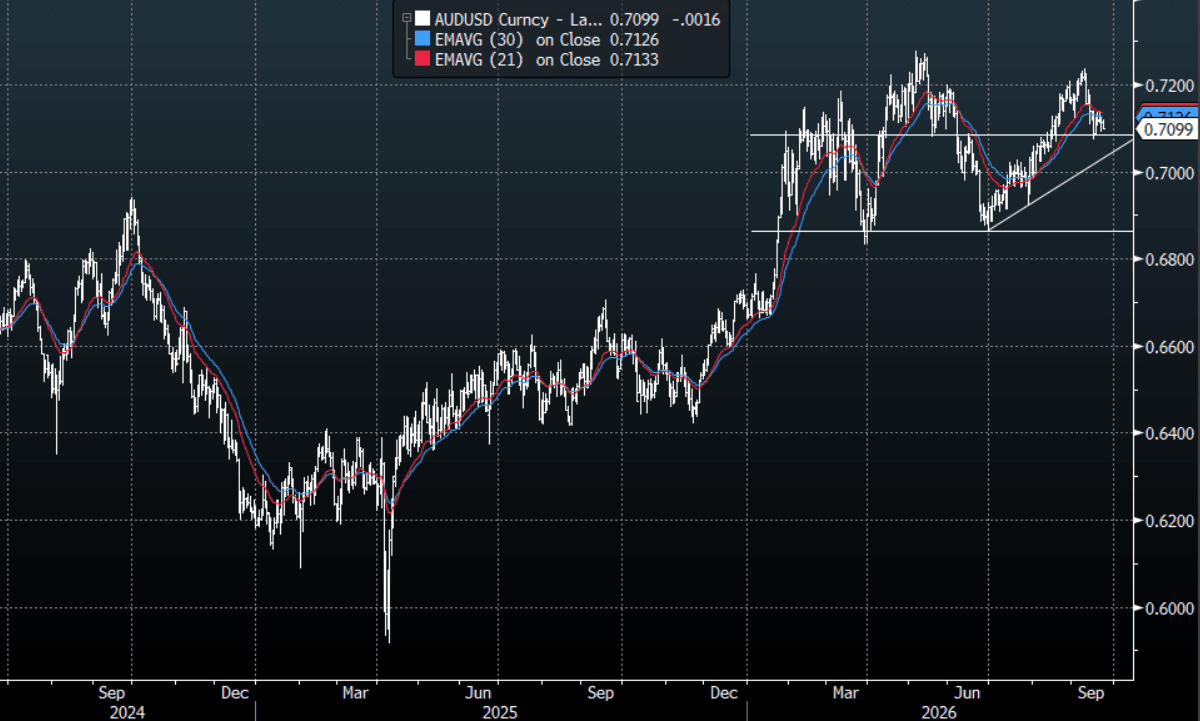
The AUD/USD has had a range today of 0.7101-0.7121 in the Asia- Pac session, it is currently trading around 0.7100, -0.21%. The pair continues to consolidate just above 0.7100 albeit with an offered tone unable to get any upward momentum as of yet. Risk continues to trade on the front foot, with Oil falling again on Trump reporting a productive meeting with Iran. Yet currencies continue to trade with a heavy tone, there is a clear disconnect and the relationship between Risk and the US Dollar seems to be diverging. How long does that last ? What is telling us ? The AUD has been a favoured long while risk trades on the front foot, in the current environment I would have expected it to be performing better. On the day, while the support between 0.7050-0.7100 holds the Bulls will continue in their attempt to reassert its uptrend. The AUD has found rallies being faded toward the 0.7130-0.7160 area initially. A sustained break above there and the bulls could potentially wrest back control but a sustained move back below 0.7000-0.7050 would start to become problematic.
- MNI: Payback Expected For July’s Weak Employment Outcome, Data Volatile. August jobs print on Thursday and are expected to unwind July's loss of 15.8k rising 20k with the unemployment and participation rates holding steady at 4.5% and 66.9% respectively. The data are volatile and so 3-month averages are needed to gauge the trend. They have signalled a gradual easing in labour market conditions, which the RBA has welcomed in its fight to return inflation to target. Governor Bullock said this week that the current unemployment rate at 4.5% is still a "bit tight" but if it edged towards 5%, it could be high enough to ease price pressures.
- MNI - AU Q3 Cost/Prices Ease On Q2 But Rise In September, Confidence Weak: While the preliminary September S&P Global composite PMI eased to 50.8 from 52.7, there was a pickup in Q3 signalling GDP growth may have improved in the quarter. Q3 averaged 52.2 up from Q2's 49.8, which was impacted by geopolitical uncertainty and jump in fuel prices. However, Q3 services PMI was also higher than Q1 and Q4 signalling resilience. Cost growth rose to its highest for Q3 driven by services but importantly selling price inflation also increased implying increased cost pass through but both measures are below Q2's highs. The RBA will continue to watch second-round effects from higher fuel costs as it worries upside inflation risks are "materialising". The market has a 86% chance of a hike on 29 September.
- Options : Closest significant option expiries for NY cut, based on DTCC data: 0.7050(AUD715m), 0.7125(AUD628m), 0.7180(AUD578m). Upcoming Close Strikes : 0.7100(AUD1.08b Sept 28), 0.7150(AUD792m Sept 25), 0.7160(AUD703m Sept 24) - BBG
- The AUD/USD Average True Range for the last 10 Trading days: 34 Points
Fig 1: AUD/USD spot Daily Chart
Source: MNI - Market News/Bloomberg Finance L.P


