BONDS: NZGBS: Holding 2-4Bps Firmer, RBNZ To Consult On OMOs
Benchmark NZGB yields how around 2-4bps higher for Wednesday trade. Outside of early yield moves, which followed US gains from Tuesday trade, we have seen quite steady trends through the rest of trade today. The 2yr yield rests at 2.96%, while the 10yr is just above 4.33%, up around 4bps. The 2/10s curve is a touch steeper at +137bps. The 2yr swap rate is down a touch to 2.745%.
- US Tsy futures are a touch weaker so far today, while cash yields are little changed ahead of key inflation data (both this evening and on Thursday).
- The data calendar just had net migration figures for July, not a market mover. We were up +2k and showing some signs of stabilization, with annual migration up to +13k. Still, we are coming from a low base, so further recover is likely needed for this to benefit the economy more broadly.
- The RBNZ announced: "We are consulting on how we conduct Open Market Operations and are seeking input on design considerations for a Committed Liquidity Facility. This consultation builds upon previous work, including speeches and Bulletins given as part of the Liquidity Management Review. Respondents to the consultation may choose to comment on one or both parts of the consultation and whichever questions are relevant to them. This consultation is open until 31 October."
- The data calendar is empty tomorrow, with Friday delivering the Aug PMI, along with card spending figures.
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
US TSYS: Futures Trade Slightly Higher
The TYU5 range has been 111-25+ to 111-29+ during the Asia-Pacific session. It last changed hands at 111-29, up 0-02+ from the previous close.
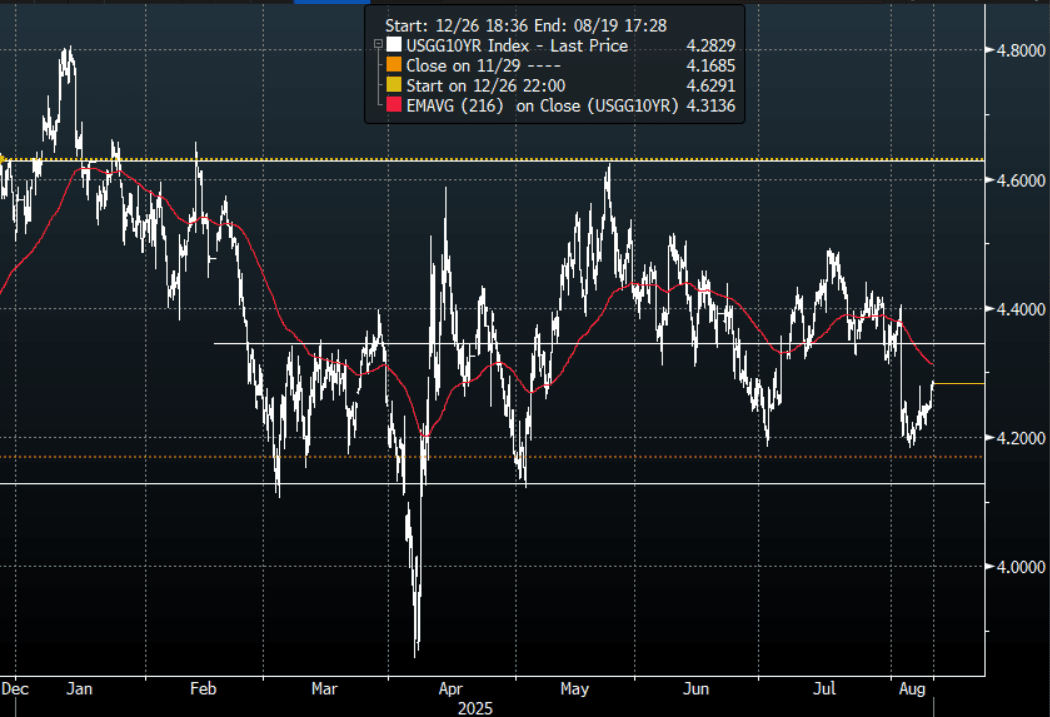
- The 10-year yield had a powerful move lower in reaction to the NFP data, breaking below its 4.30% pivot within the wider range 4.10% - 4.65%. This now turns momentum lower in yields and you could expect buyers of treasuries on bounces back towards 4.30/35% now looking to initially test the 4.10% area.
- Bob Elliott on X: “Used car prices have been a big negative on CPI for the last 3m. A notable difference from the broad trend of underlying used car prices going from a significant disinflationary pressure to a modestly inflationary one over the last year or so.”
MNI DATA - Tuesday’s CPI report headlines the US economic calendar with analysts expecting core CPI inflation to gain momentum in July as the acceleration in core goods inflation continues. We’re starting to get into larger tariff impacts on core goods but the largest could be reserved for Aug-Sep by some estimates. We are currently tracking unrounded core CPI estimates at around 0.32% M/M after the 0.23% in June at what would be the strongest M/M print since January.
Fig 1: 10-Year US Yield 2H Chart
Source: MNI - Market News/Bloomberg Finance L.P
CHINA: Bond Futures Down in Morning Trade
- China's bond futures have begun the week with falls in Monday's morning session.
- After finishing last week up by +0.16, the 10Yr bond future has given all of that back in this morning's session, falling -0.16 to 108.45.
- Having trade last week above the 20-day EMA (of 108.56) the sell off this morning sees the 10Yr track below all major moving averages.
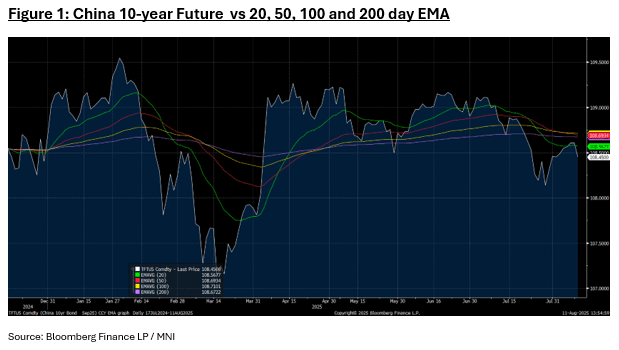
- The 2-year future is lower by -0.01 at 102.35, having traded near to the 20-day EMA of 102.37 before turning lower again.
- The 10YR Government bond has seen yields climb +1.5bp to 1.71%
MNI EXCLUSIVE: Limited PPI Impact From China's Supply Reforms
A leading commodities expert shares her view on China's supply reforms.
On MNI Policy MainWire now, for more details please contact sales@marketnews.com


