US: "*NVIDIA SAYS NEW AGREEMENTS WITH SAMSUNG ELECTRO MECHANICS" - BBG
"*NVIDIA SAYS NEW AGREEMENTS WITH SAMSUNG ELECTRO MECHANICS" - BBG "*NVIDIA NO LONGER SHIPPING LICE...
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
AUSSIE 10-YEAR TECHS: (Z6) Remains Above Its Recent Lows For Now
- RES 3: 95.425 - High Mar 2 (cont)
- RES 2: 95.270 - High Jun 26 (cont)
- RES 1: 94.825 - High Oct 15
- PRICE: 94.740 @ 15:50 BST Oct 16
- SUP 1: 94.515 - Low Sep 15 & Sep 28
- SUP 2: 94.490 - Lower 3.0% Bollinger Band
- SUP 3: 93.674 - 1.0% 10-dma envelope
A dominant bearish condition in Aussie 10-yr futures remains intact. The contract has recently cleared 94.780, the Mar 23 / 30 low. This strengthens a bear theme and maintains the medium-term sequence of lower lows and lower highs. Scope is seen for an extension towards 94.490, a vol based support. On the upside, a reversal higher would refocus attention on the bull trigger at 95.270, the Jun 26 high.
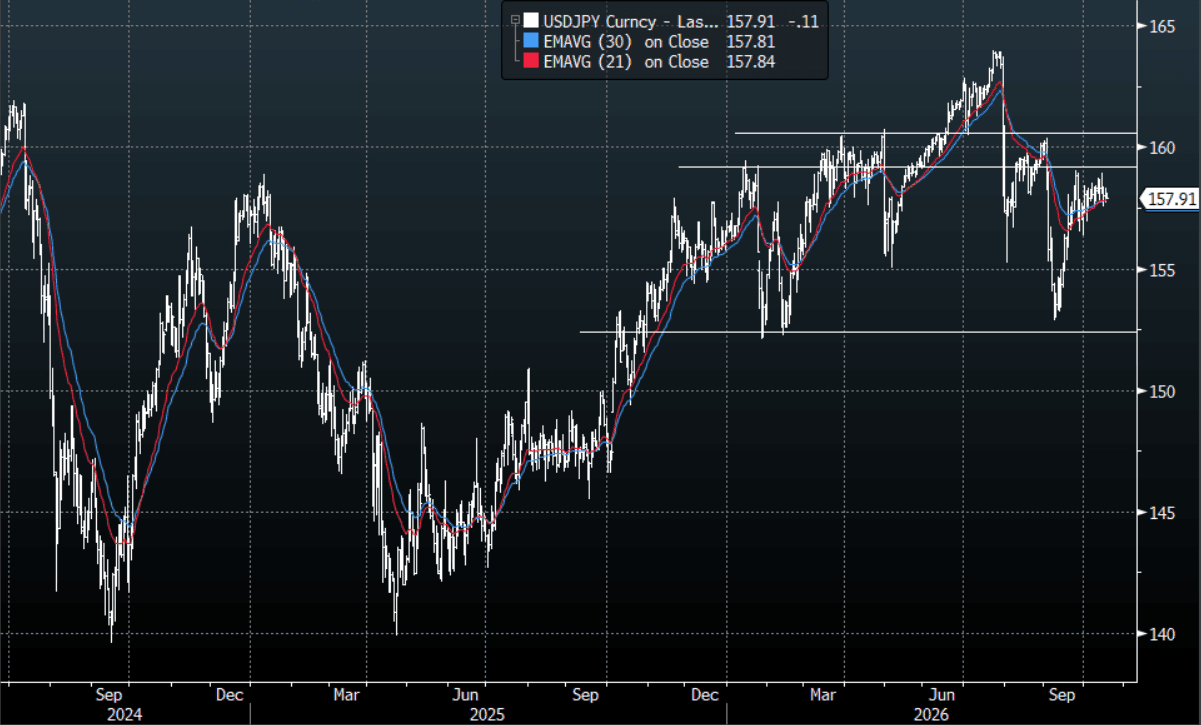
JPY: USD/JPY - Continues To Tread Water Around 158.00
The USD/JPY range Friday night was 157.70-158.34, Asia is currently trading around 157.90. The pair continues to chop around the 158.00 handle without any clear direction. The mounting headwinds for risk seem to eventually be starting to take their toll as we saw stocks move lower on Friday night and the VIX spike. The news that Trump is talking up a peace deal between Russia and Ukraine could provide a slight reprieve first thing this morning though. The leveraged market has been looking to rebuild Yen shorts after the BOJ dropped the ball, though Asset managers seem content that the long Yen trade can still develop. The 159.00-160.50 area technically looks quite important now and I suspect the BOJ/MOJ will be doing what they can to keep it below there. The first support is around 157.50 and then the 156.00-156.50 area.
- “Sanae Takaichi signaled she plans to attend the APEC leaders summit in China next month if parliament allows, amid deteriorating relations between the two countries. The PM’s government is mulling a corporate tax hike to fuel defense spending, Sankei reported.” - BBG
- CFTC Data up to 13/10/2026 shows Asset Managers slightly paring back their newly built Yen longs, +66 524(Last +68 749). The Leveraged community is back rebuilding a short after a very brief and unsuccessful attempt at going long, -37 820(Last -30 379).
- Options : Close significant option expiries for NY cut, based on DTCC data: 156.00($407m), 157.15($430m). Upcoming Close Strikes : 157.50($1.43b Oct 22), 160.00($1.76b Oct 22), 160.50($1.22b Oct 22) - BBG.
- The USD/JPY Average True Range(ATR) for the last 10 Trading days: 70 Points
- Data/Event : Tertiary Industry Index MoM
Fig 1 : USD/JPY Spot Daily Chart
Source: MNI - Market News/Bloomberg Finance L.P
US TSYS: Futures Re-Open Stronger after Friday's Modest Twist-Steepener
TYZ6 is dealing at 105-23, +0-07 from closing levels in today's Asia-Pac session.
- MNI Techs (TYZ6): Key support and the bear trigger is 103-28+, the Oct 1 low. Clearance of this level would resume the downtrend.
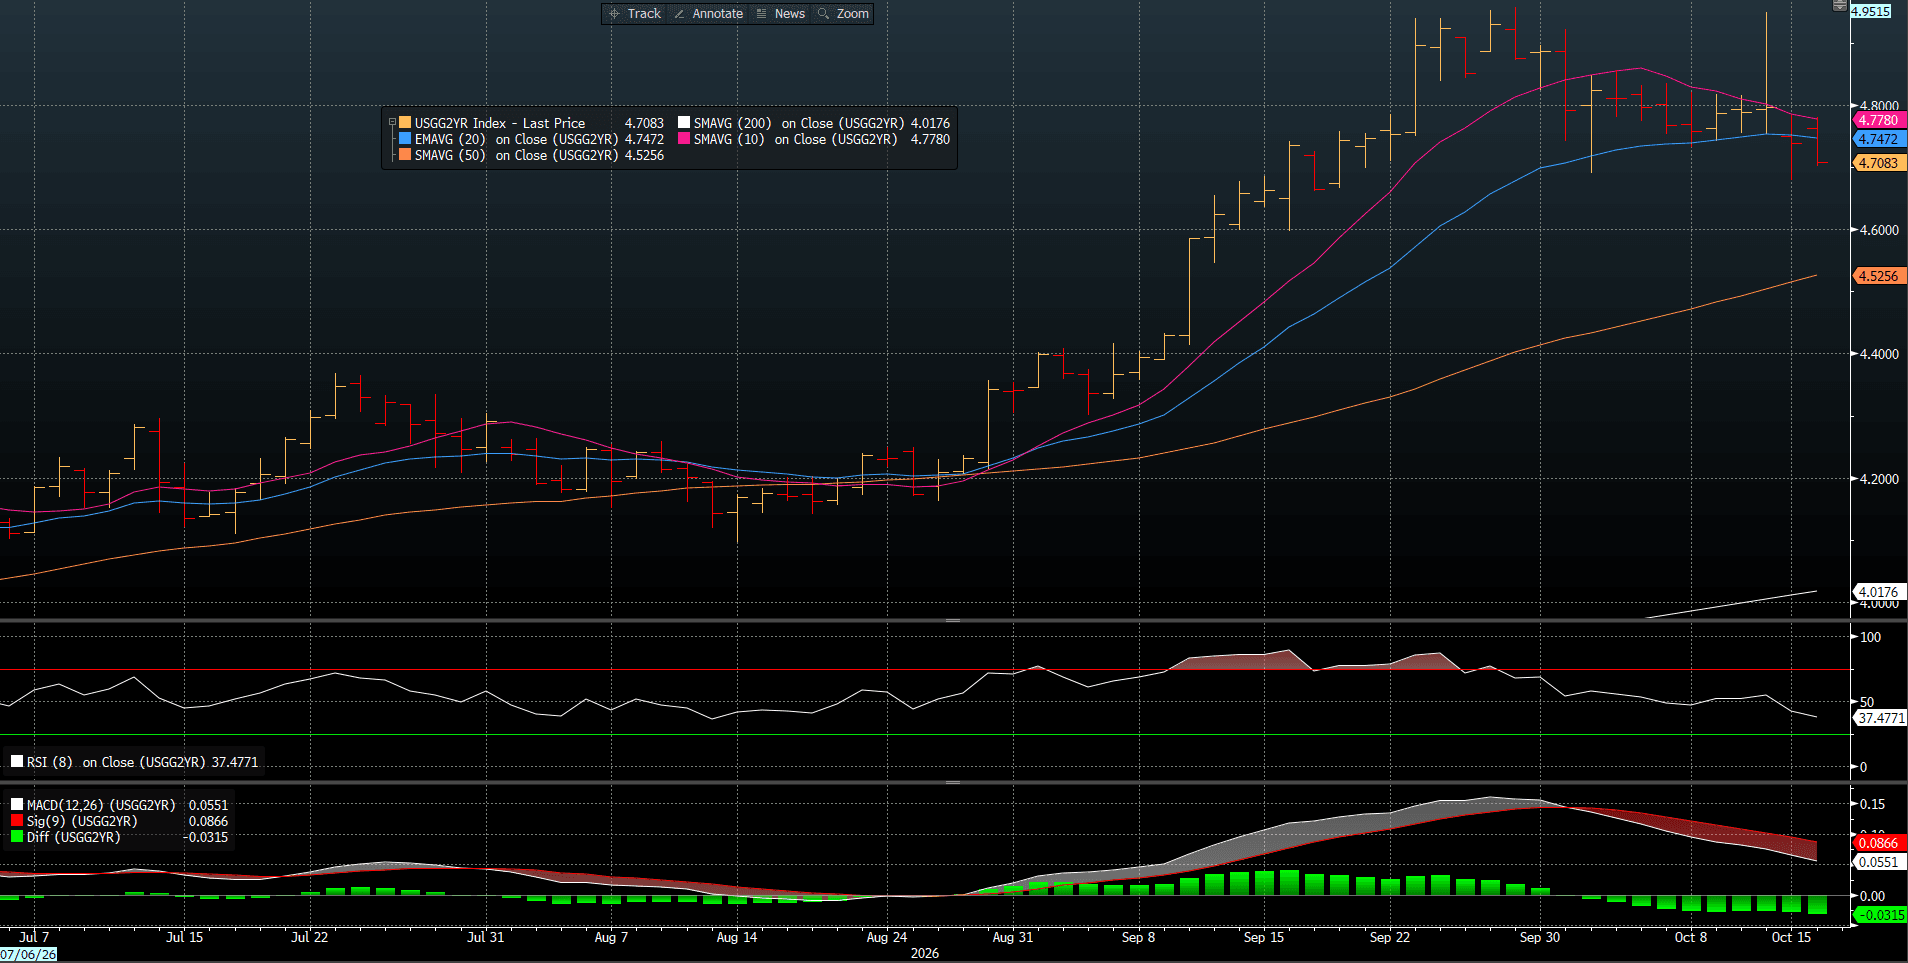
- Cash bonds finished Friday’s session showing a modest twist-steepening, with benchmark yields 3bps lower to 2bps higher.
- Markets were buffeted by a renewed surge in crude prices and weaker stocks amid ongoing concern re: stretched AI-tied tech valuations (tech-heavy Nasdaq -2.3% late Friday). The Federal Reserve entered media blackout late Friday through October 29 - the day after the next FOMC announcement.
- WTI Crude ended higher, surmounting $100/bbl for the first time since Sep 18, extending gains amid escalation risk in the Middle East, while there is additional support from the filing of a bill in Congress to block US loosening of restrictions on Russian diesel. However, the severity of the move appears to exaggerate the likely impact from the Russia bill alone, given Congress is out of session.
- Look ahead: Canada September Inflation and BOC Quarterly Business Survey on Monday. New Zealand Q3 CPI on Thursday, Japan Sep CPI on Friday is expected to firm relative to the Aug outcome, as well as EU October flash PMIs.
Bloomberg Finance LP


