RATINGS: Moody's Upgrades Portugal To A2
Moody's upgraded Portugal's sovereign rating to A2 from A3, with stable outlook (had been stable). M...
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
JPY: USD/JPY - Groundhog Day Around 158.00, Are There Signs Of Repatriation?
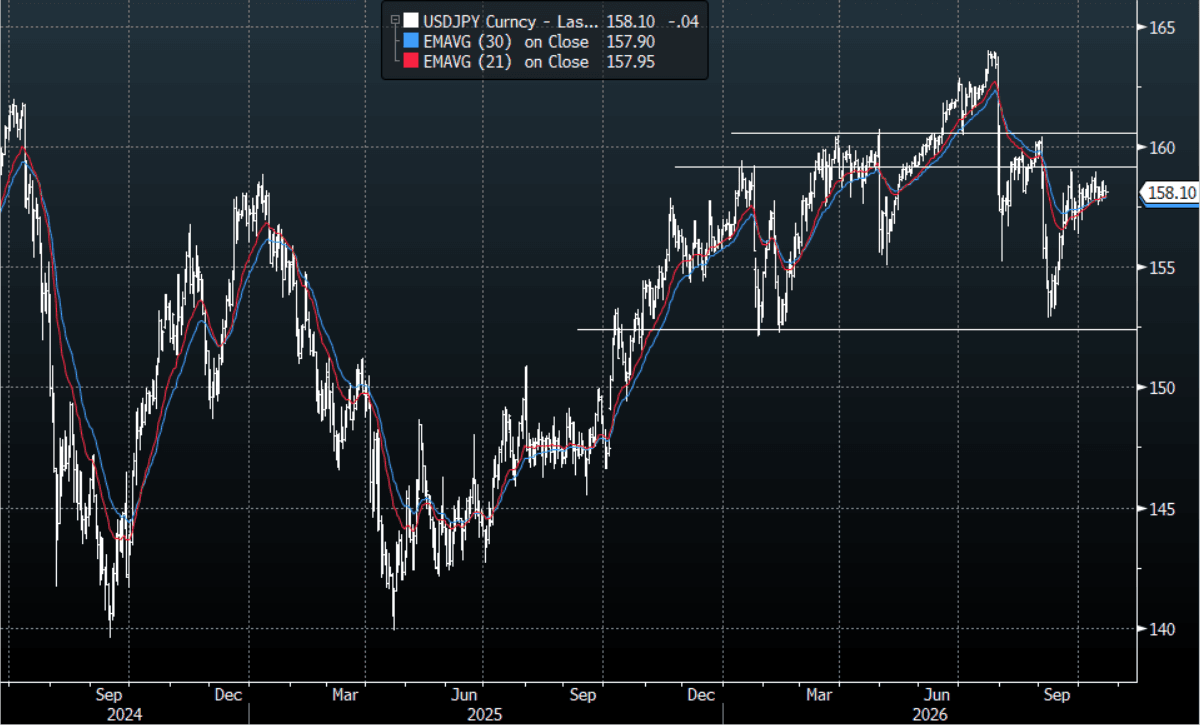
The USD/JPY range overnight was 157.84-158.34, Asia is currently trading around 158.11. It's Groundhog day as the pair continues to chop around the 158.00 area, unable to get any momentum higher as the US Dollar continues to struggle. The leveraged market has been looking to rebuild Yen shorts after the BOJ dropped the ball, though Asset managers seem content that the long Yen trade can still develop(The Crosses are exhibiting some signs of exhaustion) as signs of repatriation are starting to emerge. Though positioning is now much lighter. The 159.00-160.50 area technically looks quite important now and I suspect the BOJ/MOJ will be doing what they can to keep it below there. The first support is around 157.00-157.50 a sustained move below there is needed to perhaps get some green shoots for the Yen.
- “Japanese life insurers signaled they will maintain or increase purchases of domestic bonds in the second half of the fiscal year, offering a potential source of support for future government debt auctions.” - BBG
- Speevr Research: “Yen Repatriation: The Tide Is Turning. From 2014 to 2025, Japan bought foreign securities worth about 2% of GDP a year. In 2026 the tide is turning. Banks are selling foreign bonds and capital flow has turned to a small net inflow.” - Takuji Okubo.”
- Options : Close significant option expiries for NY cut, based on DTCC data: 157.80($110m), 158.00($1.26b).
- The USD/JPY Average True Range(ATR) for the last 10 Trading days: 64 Points
- Data/Event : Weekly Investment Flows, Machine Tool Orders
Fig 1 : USD/JPY Spot Daily Chart
Source: MNI - Market News/Bloomberg Finance L.P
STIR: RBNZ-Dated OIS Little Changed Of Q3 CPI, 85% Chance Of Oct Hike Priced
RBNZ-dated OIS pricing is little changed ahead of Q3 CPI data.
- The result will likely be decisive for the RBNZ's 28 October decision. A print above the 3.8% median consensus would reinforce the case for a hike; a softer outcome could see the RBNZ pause, consistent with the optionality signalled by Conway.
- Its sector factor model measure of core will also be released Thursday. It has held at or within target for 7 quarters and printed at 2.7% in Q2.
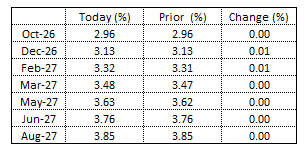
- RBNZ-dated OIS pricing closed slightly softer across meetings. 21bps of tightening is priced for October, while February 2027 and August 2027 assign 56bps and 110bps, respectively.
Figure 1: RBNZ-Dated OIS – Current Vs. Yesterday
Source: Bloomberg Finance LP / MNI
NEW ZEALAND: Q3 CPI Due, Headline Expected Back Under 4%y/y, Q4 Risks Eyed
The focus today will be on the Q3 CPI data which is forecast to rise 0.8% q/q with the annual rate moderating 0.3pp to 3.8%, slightly lower than the RBNZ’s August projection of 3.9%. Its sector factor model measure of core will also be released Thursday. It has held at or within target for 7 quarters and printed at 2.7% in Q2. RBNZ Chief Economist warned that there were upside risks to Q4 given oil prices and a weaker NZD. This is also echoed by some sell-side viewpoints, with some key snippets outlined below.
- BNZ: "September’s price data add to upside inflation risk. Our Q3 inflation forecast now matches RBNZ. With some signs of cost passthrough appearing. Upside risk to Q4 inflation lifts further. Increasing risk of inflation persistence. Given that today’s data (referring to last Friday's Sep monthly price data) is for the final month of Q3, it has relatively less influence on that quarter’s inflation. However, it is enough to nudge our Q3 forecast up a tick to +0.8% q/q and +3.9%. Q4 annual inflation is shaping up to be significantly higher than the RBNZ’s 3.9% projection in its September MPS."
- Kiwibank: "Domestically we have inflation data coming out later this week. Our inflation prediction is at the high end of the spectrum for the September quarter. We’re expecting it to come out at 4%, just narrowly lower than the June quarter. But we’re quietly hoping we’re wrong. A 3.8% would have us jumping for joy (3.8% was our call for the September quarter back in July)."
- ASB: "We expect Q3 CPI to print 0.8% q/q and 3.9% y/y, broadly in line with the RBNZ’s September MPS pick. NZ annual CPI inflation is likely to end this year at around 4.5%. We also expect the inflation profile for 2027 will be considerably firmer than the RBNZ’s September MPS expectations. Our OCR forecasts are under review. At this current juncture, the risks are meaningfully skewed to an OCR above 3.25% in 2027."
- Westpac: "We estimate that New Zealand consumer prices rose by 0.7% in the September quarter, with a moderation in fuel costs balanced against increases in council rates, building costs and food prices. The annual inflation rate is expected to drop back to 3.7% (down from 4.1% in the year to June). Measures of core inflation are expected to remain firm, with some closely watched measures expected to rise to the top of the RBNZ’s target band. Our forecast is a little below the RBNZ’s last published forecast for 3.9% annual inflation.


