MNI EXCLUSIVE: MNI: Watered-Down EU Deal Points To Resistence To Draghi Plan
Apr-19 2024 08:47
MNI speaks to European officials about the outlook for competitiveness reforms-- On MNI Policy MainWire now, for more details please contact sales@marketnews.com
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
GERMAN DATA: PPI - Energy Deflation Waning But Broad-Based Disinflation Elsewhere
Mar-20 2024 08:32
German Producer Prices for February came in below expectations at -4.1% Y/Y (vs -3.8% cons; -4.4% prior) and -0.4% M/M (vs -0.1% cons; +0.2% prior).
- Looking at the individual categories, there was broad-based disinflation, particular in consumption goods (+0.4% Y/Y vs +1.1% prior) and non-durable goods (+0.2% Y/Y vs 1.1% prior).
- Durable goods inflated +1.5% Y/Y (vs +1.6% prior), investment goods inflated +2.8% Y/Y (vs 3.0% prior), and intermediate goods deflated 3.8% Y/Y (vs 3.7% prior). In all of these categories, the yearly rates were the lowest in the current inflation cycle.
- Only the yearly rate in the energy category inclined, coming in at its highest level since May 2023 at -10.1% Y/Y (vs -11.7% prior), driven by waning base effects. Excluding energy, producer prices inflated +0.1% M/M in February but decreased 0.8% Y/Y, Destatis notes.
- The fact that most categories continue to print lower yearly growth rates can be seen as good sign in terms of mid-term disinflation in consumer prices.
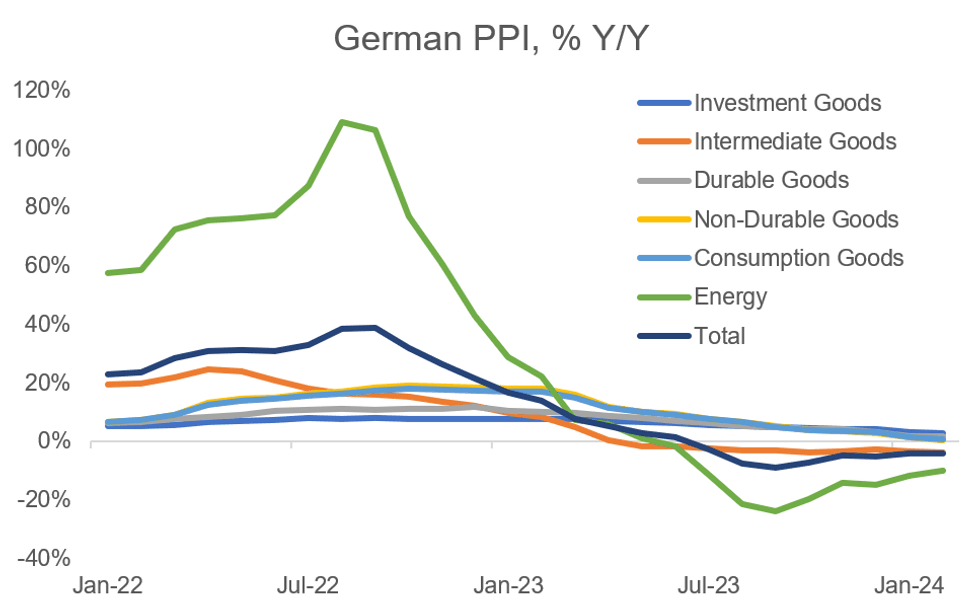 MNI, Destatis
EQUITIES: BNP single stock Option
Mar-20 2024 08:28
Single stock Bank Option, BNP:
- BNP (19/12/25) 52p, sold at 4.90 in 3k.
GILTS: Firmer On CPI
Mar-20 2024 08:21
Core global FI rallies further on the gilt open as participants digest UK CPI, futures last +43 at 99.16 (98.97-99.22 range).
- The Mar 14 high (99.35) presents initial resistance.
- More meaningful resistance seen at the Mar 12 high (100.37).
- Gilt yields 5-6bp lower, 10s settle around 4.00%.
- SONIA futures & BoE-dated OIS around pre-gilt open levels.
- Overnight the XpertHR wage growth measure printed at the lowest level seen since late ’22, along with flagging expectations for a moderation in pay growth in ‘24 vs. ’23 (see earlier bullet for more details there).
- Elsewhere, some comments from Chancellor Hunt have increased speculation re: October General election timing.
- Hunt also pointed to a pre-election fiscal event, which was already widely expected.
- Wider fiscal comments from Hunt and shadow Chancellor Reeves lacked much in the way of meaningful detail, given the above expectations.
- Domestic focus now moves to tomorrow’s BoE decision. See our full preview of that event here.


