MNI US Payrolls Preview: Temporary Boosts To Be Looked Through

Apr-01 16:34By: Chris Harrison and 1 more...
EmploymentPayrollsFederal ReserveUS+ 1
Hidden PDF
Executive Summary
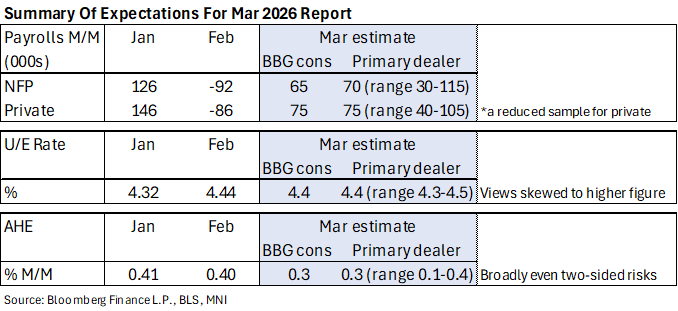
- Nonfarm payrolls are seen increasing by 65k in March (dealer median 70k) after two heavily conflicting reports with a far weaker than expected -92k in Feb but also a particularly robust 126k in Jan.
- March will have been boosted by a return of 32k striking workers from Feb, almost all in healthcare, whilst there might have been a moderate boost from warmer weather.
- Private payrolls growth is expected at 75k, which stripping out that post-strike boost is close to the 34k averaged over the six months to February.
- A usually dovish Fed Governor Waller has shifted to more of a “wait and see” approach on inflation risk grounds from the US-Israel-Iran war but also research pointing to zero breakeven payrolls growth.
- On a related note, the household survey’s unemployment rate is expected to hold at 4.4% with risk unsurprisingly seen tilted to a 4.5% print – it was 4.44% in February.
- This u/e rate has broadly plateaued in recent months: average the mixed Jan and Feb reports and the 4.38% sat between the caveated 4.47% in Q4 (government shutdown disruption) and 4.34% in Q3.
- The reference period around the 12th of the month falls after the start of the US-Israel-Iran war, although we suspect any material impact will take longer to feed through.
- This report will be published on Good Friday for the first time since 2021. Markets will have condensed hours with Treasuries closing at 1115ET (futures)/1200ET (cash), whilst equity futures close just 45 minutes after the publication at 0915ET and with cash equities closed all day.
- Fed pricing remains highly sensitive to fluid Iran-related headlines but currently sees almost 10bp of cuts in 2026. We suspect greater sensitivity will be seen to a downside surprise.