MNI US Macro Weekly: Weighing The Costs Of Conflict

Mar-27 19:55By: Tim Cooper and 1 more...
USFederal Reserve
Hidden PDF
Executive Summary
- Almost a month in, the macro consequences of the war in the Middle East remain challenging to weigh for market participants and Fed officials alike. Incoming data, while obviously stale to at least some degree, show continued inflation pressures and a nascent uptick in consumer price expectations, but activity appeared to remain relatively robust through March.
- Activity data showed something of a split, with manufacturing surveys (flash PMIs and regional Feds) remaining resilient while services softened more noticeably, as higher energy costs linked to the Middle East conflict pushed price pressures higher.
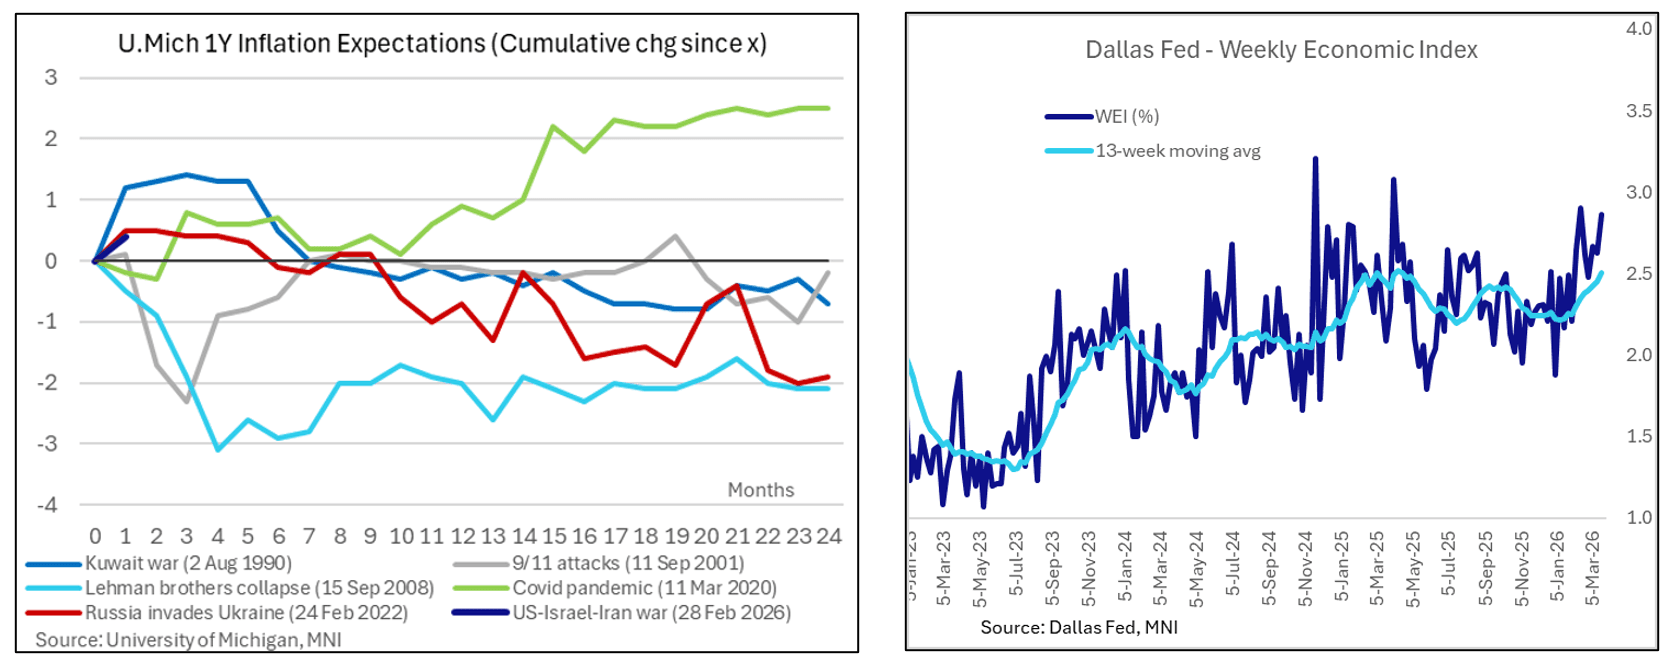
- Indeed, inflation readings largely firmed, led by a surge in February import prices—especially capital goods and industrial supplies— even before the Mideast shock, while consumer surveys showed a meaningful jump in short‑term inflation expectations but relatively stable longer‑term expectations.
- But the labor market remains mostly resilient, with jobless claims staying very low and continuing claims improving further, even as payroll indicators continue to point to only modest underlying job growth.
- Growth tracking cooled slightly but stayed solid, as GDPNow was trimmed on construction weakness, but with firm real‑time retail sales indicators and a pickup in the Dallas Fed’s Weekly Economic Index.
- Markets and policymakers grappled with war‑driven uncertainty, as market‑implied Fed policy rates swung sharply during the week, while Fedspeak emphasized patience, higher inflation risks from energy prices, and a still‑fragile labor market constraining hawkish follow‑through.
- This week has ranged from pricing in almost 25bp of Fed hikes to end-2026 on Monday shortly before President Trump’s post on a five-day pause in strikes on Iranian energy infrastructure to pricing out any hikes later that day. Since then, despite another announced pause in strikes, oil prices have surged and Friday briefly saw 20bp of hikes priced again only to then heavily pare this increase to just 5bp.
- Looking ahead, next week brings key tests of the outlook with March nonfarm payrolls, ISM manufacturing, retail sales, JOLTS, and consumer confidence all due, along with an appearance by Fed Chair Powell.