MACRO ANALYSIS: MNI US Macro Weekly: The Chips Are Down, But The Jobs Are Up
We've published our US Macro Weekly - PDF here: https://mni.marketnews.com/3XaajaR * Fed rate hike ...
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
CANADA DATA: Ivey PMI Consistent With Other Surveys Showing A Mixed September
The Ivey Purchasing Manager's Index dipped in September, mirroring various private sector surveys in the month including the S&P Global PMI (manufacturing 6-month low) and the CFIB small business barometer (5-month low). Overall, economic activity in September was mixed at best, with the flare-up in the US-Canada trade conflict (talks collapsed on Aug 21) showing nascent signs of taking a toll.
- The fall in the Ivey PMI to 58.2 came from a 52-month high 64.3 in August, though that was still an elevated figure and the subcomponent details weren't quite as poor as the headline deterioration suggests.
- Employment ticked up to a 32-month high 56.5 from 55.0, with supplier deliveries falling 2.3 points to 39.2 (6-month low) and inventories pulling back 3.1 points from August's 52-month high 61.4.
- It's possible the survey captured some inventory build ahead of Canadian retaliatory tariffs on the US, with the pullback in supplier deliveries suggesting slower supply chains (the Ivey reading is based on month-end data).
- The main cause for concern was the jump in prices: at 82.8 (80.4 prior) it was the highest in 53 months, which looks largely energy-related.
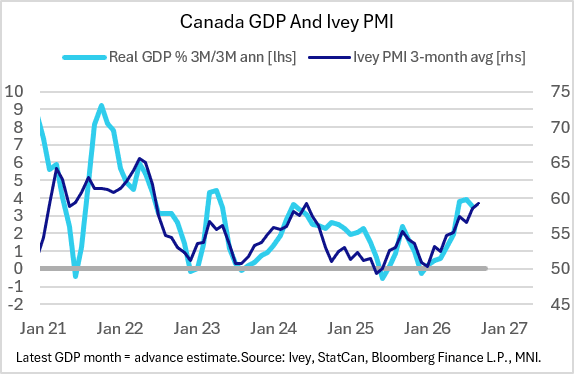
- The 3-month moving average, having been boosted by the outsized August reading, continued to climb to the best levels since mid-2022, historically consistent with real GDP growth above 3% (Q/Q annualized) though it looks to have peaked in Q3.
US TSYS: Sep FOMC Minutes Hike Firm & Unanimous
- Treasuries look to finish mixed Wednesday, curves twisting steeper (2s10s +3.157 at 50.917) well before the Sep FOMC minutes release.
- The minutes to the FOMC's September meeting largely confirmed what we already took away from the decision release and related materials. As Chair Warsh said after the meeting, the hike was a "firm, unanimous decision", and the minutes confirm that "all participants" supported the move, judging "that this would support a timelier return of inflation to the Committee’s 2 percent goal."
- Tsys were slow to react but crude climbs (WTI appr $89.25) in reaction to latest headline purporting the WH looking to Pentagon for strike options against Iran. TYZ6 trades -1.5 at 104-14 - off 104-17.5 high.
- Early oil decline: IEA members expressed support for accelerating the stock releases announced in March, “with a view to completing them as soon as possible.” The governing board of the IEA is expected to decide the details of the release at a meeting on Oct 14-15.
- Inflation expectation components within the NY Fed’s consumer survey continued their uptrend seen since the start of the year for shorter-term periods. That's especially so for the 1Y at its highest since 2023 having surpassed peaks seen earlier in the US-Iran war and after 2025 tariff announcements. 5Y expectations remain firmly anchored at 3% however.
- Consumer credit growth remained mixed but subdued overall in August, with a 21-month worst 4.2% M/M (SAAR) drop in revolving credit alongside a 4.1% rise in non-revolving. That meant a 1.9% overall credit growth rate, down sharply from 4.1% in July and a 3-month low.
USDCAD TECHS: Bulls Build Momentum
- RES 4: 1.4739 Multiyear high - 03 Feb ‘25
- RES 3: 1.4415 High 01 Apr ‘25
- RES 2: 1.4328 1.764 proj of the Jan 30 - Mar 31 - May 1 price swing
- RES 1: 1.4294 High Oct 05
- PRICE: 1.4247 @ 15:55 BST Oct 07
- SUP 1: 1.4135/4102 Low Sep 28 / 20-day EMA
- SUP 2: 1.4020 50-day EMA
- SUP 3: 1.3859 Low Sep 14
- SUP 4: 1.3732 Low Aug 21 and the bear trigger
USDCAD continues to build, hitting new highs Monday. Tuesday’s partial fade is seen as corrective and the underlying bull theme holds for now. This puts price through 1.4248, the Jun 24 and 25 high and key resistance, as well as 1.4264, a Fibonacci projection. 1.4328 now draws focus as the next upside level before 1.4415. First key support to watch lies at 1.4102, the 20-day EMA.


