MNI US Macro Weekly: CPI To Say If Disinflation Given A Chance

Sep-04 19:57By: Chris Harrison
USPayrollsISM Manufacturing IndexISM Services Index+ 2
Hidden PDF
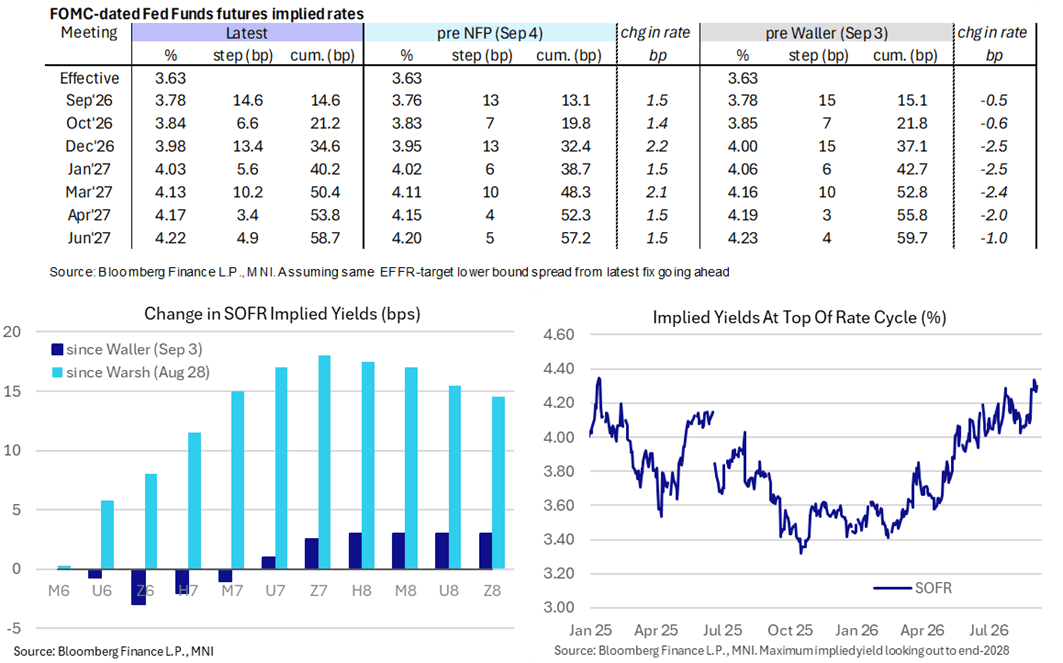
- The week’s main two drivers, certainly of front-end rates, have been a dovish Fed Governor Waller on Thursday before much stronger than expected payrolls growth in August on Friday even if still modest wage growth helped limit the impact of the latter.
- Fed Governor Waller reiterated his reaction function, but his reading of recent data was notable and drove a dovish reaction as he pointed to "finally seeing some signs of disinflation" and that he wants to “give disinflation a chance”.
- He is inclined to support holding policy at this month’s FOMC decision if August data shows continued progress, although it may not take much inflation acceleration to support a tighter policy.
- It was the last major update ahead of the FOMC media blackout and softened the hawkish stance from Fed Chair Warsh the week before at Jackson Hole even if the latter still carries weight.
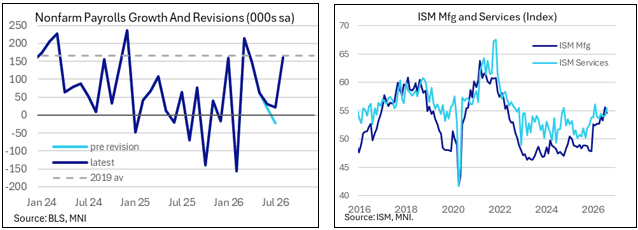
- Payrolls growth saw a strong beat in August (NFP 162k vs 55k consensus, private payrolls 127k vs 50k consensus) along with reasonable upward revisions that limited the extent of the July weakness. The unemployment rate remained at a low 4.1% as expected, as did wage growth at a contained 3.1% Y/Y.
- There were also notable business surveys even if they didn’t elicit much market reaction.
- The ISM manufacturing index was softer than expected in August at 54.6 but still the second highest since 2022 after recent strong increases. Prices paid meanwhile held steady at 71.1 off the recent peak but hold above highs seen in 2025 after tariff announcements, whilst respondents in computer & electronic product sectors note supply chain similarities with the COVID-19 period.
- The ISM services report saw almost a clean slate of upside surprises in August across the headline index and main components, with only employment surprising lower and even then at least increasing on the month. The 55.4 for the overall index is its highest since 56.1 in February (prior to which it was last higher in Oct 2024) after what had been a narrow range of 53.6-54.5 since the start of the US-Iran war.
- The August Beige Book was similar to July’s, with the highlight probably a slight cooling in the price pressures. There was only marginally softer economic activity in terms of the number of Districts reporting slight to moderate growth (still a clear majority).
- External trade details meanwhile revealed a historically strong surge in capital goods imports in July was indeed AI-related.
- Fed Funds futures are back to pricing a 25bp hike on Sept 16 as slightly more likely than not with 14.5bp priced vs 12.5bp after Waller’s remarks.
- The upcoming week’s focus is firmly on PPI (Thu) and CPI (Fri) inflation reports for August. Consensus looks for core CPI to round to 0.2% M/M again after the 0.22% M/M in July, with some initial unrounded estimates we’ve seen in a 0.22-0.25% M/M range, whilst headline CPI inflation could come in at 0.4% M/M with a bounce in energy prices along with firmer food inflation after a soft July.
Trending Top

Oct-16 08:20
Oct-16 05:49

