MNI US Inflation Insight: Limited Comfort For Hawks

Aug-13 17:31By: Chris Harrison and 1 more...
CPICore PCEFederal ReserveUS
Hidden PDF
Executive Summary
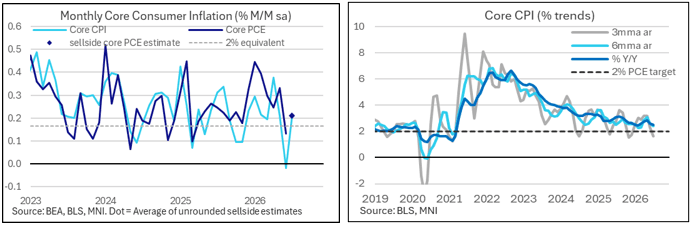
- July's CPI report showed core pressures close to expectations across the board, with core at 0.215% M/M vs a median expectation of 0.21% as core goods prices were a little on the high side whilst core services were slightly softer with the largest miss coming from lodging.
- Core goods inflation of 0.20% M/M was supported by underlying strength with median core goods inflation of 0.32% M/M by our calculations but it is just one month after a tepid five months.
- Headline CPI meanwhile was a little softer than expected at 0.07% M/M vs a median unrounded estimate of 0.12% on the back of softer energy and groceries-led food inflation.
- In Y/Y terms, core moderated further from 2.59% to 2.48% as expected, marking its softest since 2.46% in Feb and before that Mar 2021. Recent trends are softer at 1.65% annualized (3mths) and 2.4% (6mths).
- Headline CPI nearly surprised lower with an unrounded 3.36% Y/Y (consensus 3.4) as it eased from 3.53% after a stronger pullback from the recent peak of 4.25% in May in energy-driven moves.
- July's PPI report didn't further the argument for a hike at the upcoming September Fed meeting, but neither did it show convincing enough signs of disinflation to assuage hawks that current policy rates are sufficient to bring overall inflation back to target.
- Core PPI (ex-food/energy/trade services) rose 0.35% M/M after 0.11% M/M in June and rising at still-robust rates: 5.2% 3-month moving average annualized rate, 5.1% 6mma ar, 4.7% Y/Y. While we've probably seen the peak in producer price pressures, progress is only slow.
- Core PCE tracking has cooled marginally over the course of the CPI and PPI reports, currently around 0.21% M/M vs 0.23 pre-CPI, after a rare sub-target 0.13% M/M in June.
- This would translate to 3.25% Y/Y in July, off a recent high of 3.4% but stubbornly above the 2% target even after an estimated 0.2pp downward revision due with the methodological changes next month.
- PPI details included a surprisingly strong contribution from portfolio fees, adding 0.11p to monthly core PCE inflation after 0.01pp in June, with an offset from airfares and medical services. It’s possible that positive contribtions being concentrated in portfolio management, a lagged impact from strong equity gains in Q2, helped play into the rally in rates although further declines in oil clouded matters at the time.
- Removing risk of a sharper acceleration in inflationary pressures in July after an overwhelmingly set of soft June reports has seen Fed September hike pricing trimmed to 9bp vs closer to 12bp in the run up to CPI or a cumulative 24bp of hikes to year-end vs 28bp prior.