MNI US CPI Preview: Potential Fed Decider

Sep-09 19:26By: Tim Cooper and 1 more...
InflationUS
Hidden PDF
Executive Summary
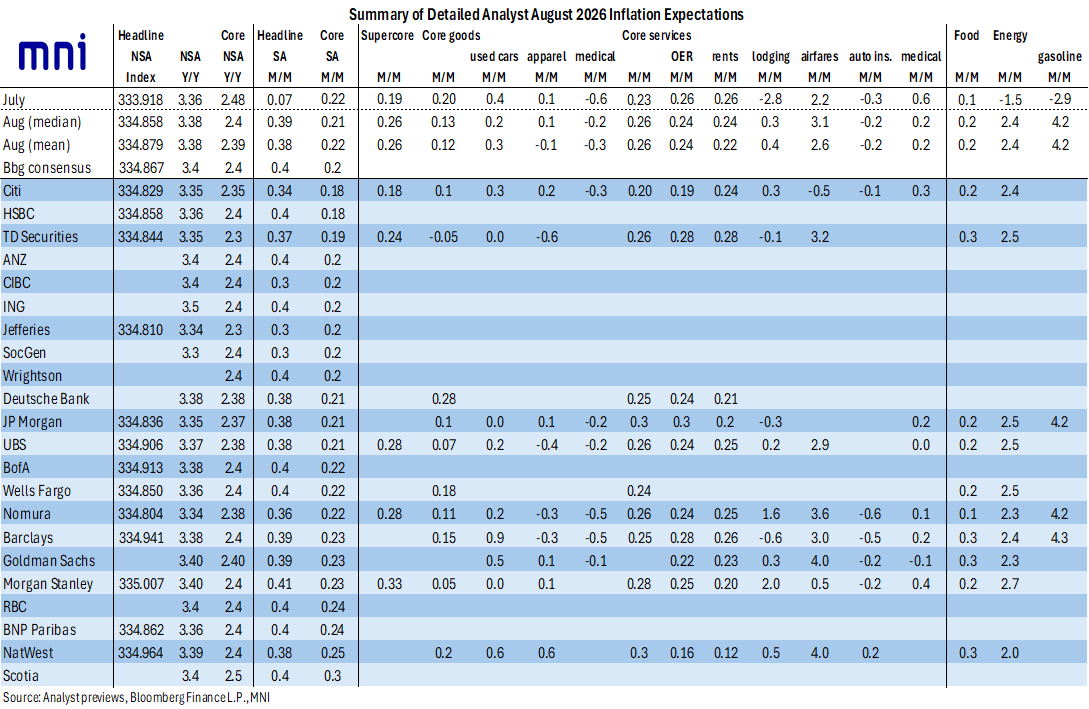
- In a crucial release ahead of next week’s Fed decision, MNI’s unrounded median of analyst estimates for August’s CPI report out Friday sees 0.22% M/M for core and 0.39% for headline.
- Mixed drivers are expected for core CPI components, with travel-related items sequentially stronger than in July but weakness across a variety of other areas. Lodging is seen rising slightly after two notably weaker-than-expected months, and airfares are seen increasing strongly.
- Medical care services CPI is seen moderating with medical care goods falling outright, apparel dipping, and used cars rising at a slower pace than in July. OER is seen around 0.25% and primary rents around 0.22%, while tech-related inflationary pressure is likely more limited after July’s strength.
- Headline is expected to be boosted by an energy bounce along with firmer food price inflation. Energy is seen rising circa 2.5% M/M after (-1.5% in July, on the back of a 4+% seasonally adjusted rise in gasoline. Food is seen rising 0.2% M/M, with some risk skewed to a 0.3% print after a surprisingly soft July.
- The August inflation reports could tip the scales for next week’s FOMC decision which is currently weighted slightly in favor of a 25bp hike going into this inflation round.
- Chair Warsh downplayed recent softer inflation prints in his Jackson Hole speech, saying his “standard” is that the Fed “must be confident that underlying inflation is moving to our objective, clearly and at sufficient speed. Otherwise, we have work to do.” But Gov Waller is “finally seeing some signs of disinflation” and wants to “give disinflation a chance, we can wait one meeting” if CPI and PPI show continued progress.
- Very crudely, a 0.2% M/M core CPI print will come down to rounding and details; 0.3% could be enough to persuade a sufficient share of the FOMC to hike, whereas 0.1% would likely see more officials come around to Waller’s approach.
- A consensus-like 0.2% core print may therefore be unlikely to settle the debate on its own, leaving the details, making the PPI-to-PCE translation and market-based core PCE implications unusually important.
- Prior to Thursday’s PPI release, an early median of analysts sees core PCE at 0.21% M/M, moderating from 0.25% in July; market-based core PCE is seen below that, at least for now.
- Market pricing is around recent hawkish extremes: Fed funds futures see 15.5bp of hikes priced for next week, a cumulative 23bp for October and 37bp by year-end, with a cumulative 63bp by June 2027.
Trending Top

Oct-16 08:20
Oct-16 05:49

