US: MNI POLITICAL RISK - Trump Intensifies Pressure On Ukraine
Oct-12 12:05
Access Full Report Here: Hidden PDF * President Donald Trump has "Executive Time" at 08:00 ET 13:00...
Want to read more?
Find more articles and bullets on these widgets:
Historical bullets
FED: MNI Fed Preview-Sept 2026: Time To Get To Work
Sep-11 21:34
We have published our preview of the September FOMC meeting - Download Full Report Here
- Persistently above-target inflation readings will lead the FOMC to hike rates for the first time since 2023 at its September meeting, with the Fed funds rate range rising 25bp to 3.75-4.00%.
- While there may be a dissent or two in favor of a hold, overall we think Chair Warsh will lead the Committee to take action given evidence that disinflation has stalled, recalling his Jackson Hole declaration that “we must be confident that underlying inflation is moving to our objective, clearly and at sufficient speed. Otherwise, we have work to do.”
- We don’t think the outcome will be altogether hawkish however. The 25bp hike is largely priced and there doesn’t appear to be significant appetite at this stage for a major hiking cycle, even among Committee hawks.
- As such we think the Dot Plot will reflect a core Committee view that two or at most three hikes will be sufficient to return policy to a restrictive enough stance to get inflation converging to target at a reasonable pace before cuts can resume by 2028.
- That’s more dovish than current market pricing which shows both an 80% implied probability of a 25bp hike at this meeting and a follow-up priced by December, with just under 100bp tightening total to the peak over the coming year.
- Warsh is once again very unlikely to offer forward guidance on future meetings. Even if as is likely he downplays the signal from the Dot Plot’s indication of just one more hike this year, his inflation-fighting rhetoric is unlikely to go any further than his Jackson Hole speech, limiting the scope for surprising hawkish takeaways from the meeting.
MNI’s separate preview of sell-side analyst summaries to follow on Monday Sept 14
US INFLATION: MNI US Inflation Insight: Firm Core Prices Seal Deal For Hike
Sep-11 20:55
We've published our review of the August inflation round - Download Full Report Here
- While August’s inflation data didn’t show a major acceleration in underlying pressures, nor will they have offered comfort to Fed participants who are looking for more decisive indications of progress toward the 2% target.
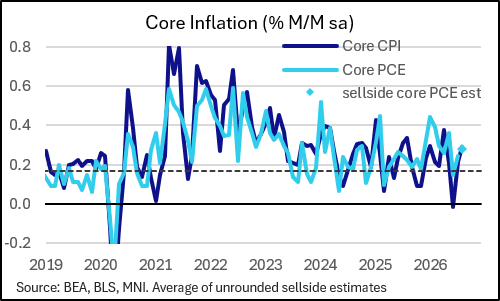
- Core CPI rose 0.29% M/M, above the 0.22% consensus and July’s 0.22%. The upside surprise was driven by supercore inflation, with core goods coming in on the soft side of expectations.
- Headline CPI was broadly in line with consensus. The monthly acceleration reflected a rebound in energy prices, while food inflation remained relatively tame. Grocery prices were flat, but food away from home remained on the warm side and indicative of continued service-sector price pressures.
- The main upside drivers in core were arguably outliers: a record increase in wireless telephone services, a rebound in lodging, and less-negative car insurance. Housing was softer than expected, while medical services were relatively benign.
- Some aspects were somewhat less concerning than the core reading suggested: median and trimmed-mean measures were softer, while dispersion measures showed some moderately encouraging developments.
- However, inflation remained broad and elevated by pre-pandemic standards, and supercore trends picked up from softer prior readings.
- The PPI report showed more moderate pipeline pressures compared to July, but run rates remained elevated amid continued energy passthrough. PCE-relevant components—including airfares and parts of healthcare -- looked on the firm side.
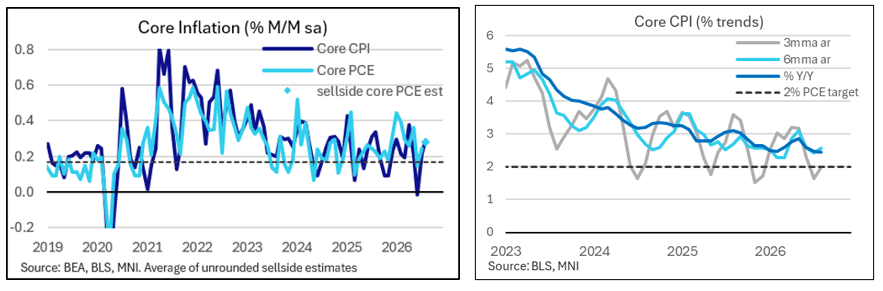
- As a result, core PCE tracking moved into the 0.25–0.30% M/M area (vs 0.21-0.22% coming into the inflation round), with consensus clustered in the high 0.20s. That would translate roughly into a 2.7-2.8% core PCE run rate on a 3-month annualized basis, with Y/Y continuing to run well above 3%.
- Gov Warsh and most of the FOMC are unlikely to be convinced that this represents anything close to a resumption of disinflationary progress. Accordingly, the data were enough to see market-implied pricing for a September Fed hike firm to well over 80%, from under 60% prior to PPI.
US DATA: Core PCE Tracking In 0.25-0.30% Area
Sep-11 20:32
Analyst estimates for August core PCE picked up again after Friday's CPI data. Prior to the release, an early median of analysts had seen core PCE at 0.24-0.25% M/M, similar to 0.25% in July; it had been around 0.21-0.22% pre-PPI; consensus now appears to be clustered in the high 0.20s.
- Barclays: 0.25% (was 0.22% pre-CPI, 0.23% pre-PPI)
- Goldman Sachs: 0.26% (0.24% pre-CPI, was 00.22% pre-PPI)
- Nomura: 0.278% (0.245% pre-CPI, was 0.205% pre-PPI).
- BofA: 0.30% (was 0.26% pre-CPI, 0.24% pre-PPI)
- TD: 0.32% (0.24% pre-CPI, was 0.18% pre-PPI)
- Mizuho: 0.3% (under old methodology and 0.4% under new methodology)