MNI Fed Preview-Sept 2026: Time To Get To Work

Sep-11 21:32By: Tim Cooper
USFederal Reserve
Hidden PDF
EXECUTIVE SUMMARY
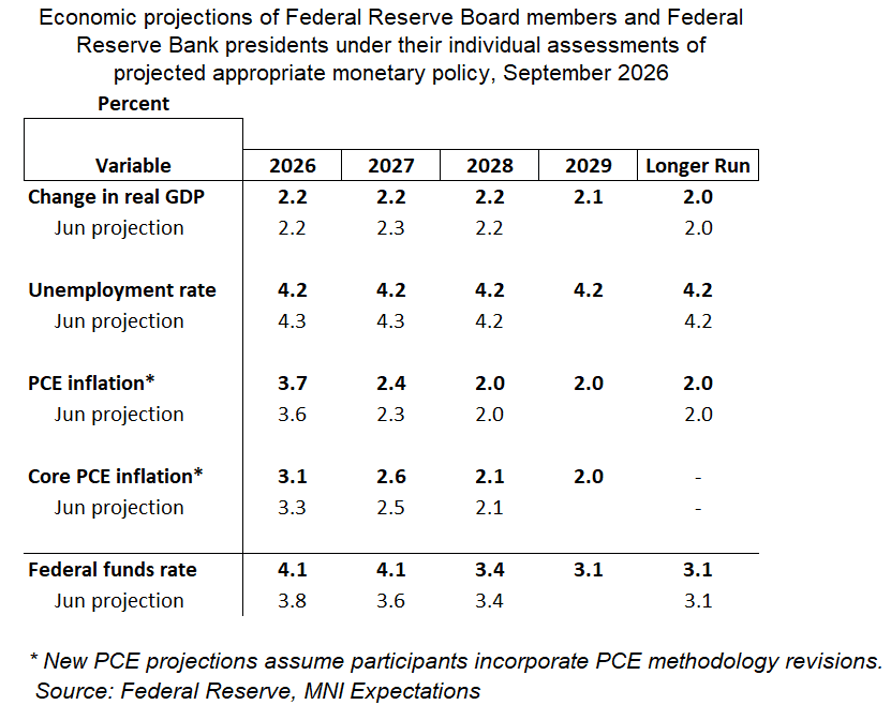
- Persistently above-target inflation readings will lead the FOMC to hike rates for the first time since 2023 at its September meeting, with the Fed funds rate range rising 25bp to 3.75-4.00%.
- While there may be a dissent or two in favor of a hold, overall we think Chair Warsh will lead the Committee to take action given evidence that disinflation has stalled, recalling his Jackson Hole declaration that “we must be confident that underlying inflation is moving to our objective, clearly and at sufficient speed. Otherwise, we have work to do.”
- We don’t think the outcome will be altogether hawkish however. The 25bp hike is largely priced and there doesn’t appear to be significant appetite at this stage for a major hiking cycle, even among Committee hawks.
- As such we think the Dot Plot will reflect a core Committee view that two or at most three hikes will be sufficient to return policy to a restrictive enough stance to get inflation converging to target at a reasonable pace before cuts can resume by 2028.
- That’s more dovish than current market pricing which shows both an 80% implied probability of a 25bp hike at this meeting and a follow-up priced by December, with just under 100bp tightening total to the peak over the coming year.
- Warsh is once again very unlikely to offer forward guidance on future meetings. Even if as is likely he downplays the signal from the Dot Plot’s indication of just one more hike this year, his inflation-fighting rhetoric is unlikely to go any further than his Jackson Hole speech, limiting the scope for surprising hawkish takeaways from the meeting.
MNI’s separate preview of sell-side analyst summaries to follow on Monday Sept 14